Category: Financial Education

  • How Compound Interest Can Make You Rich Even If You Start Small

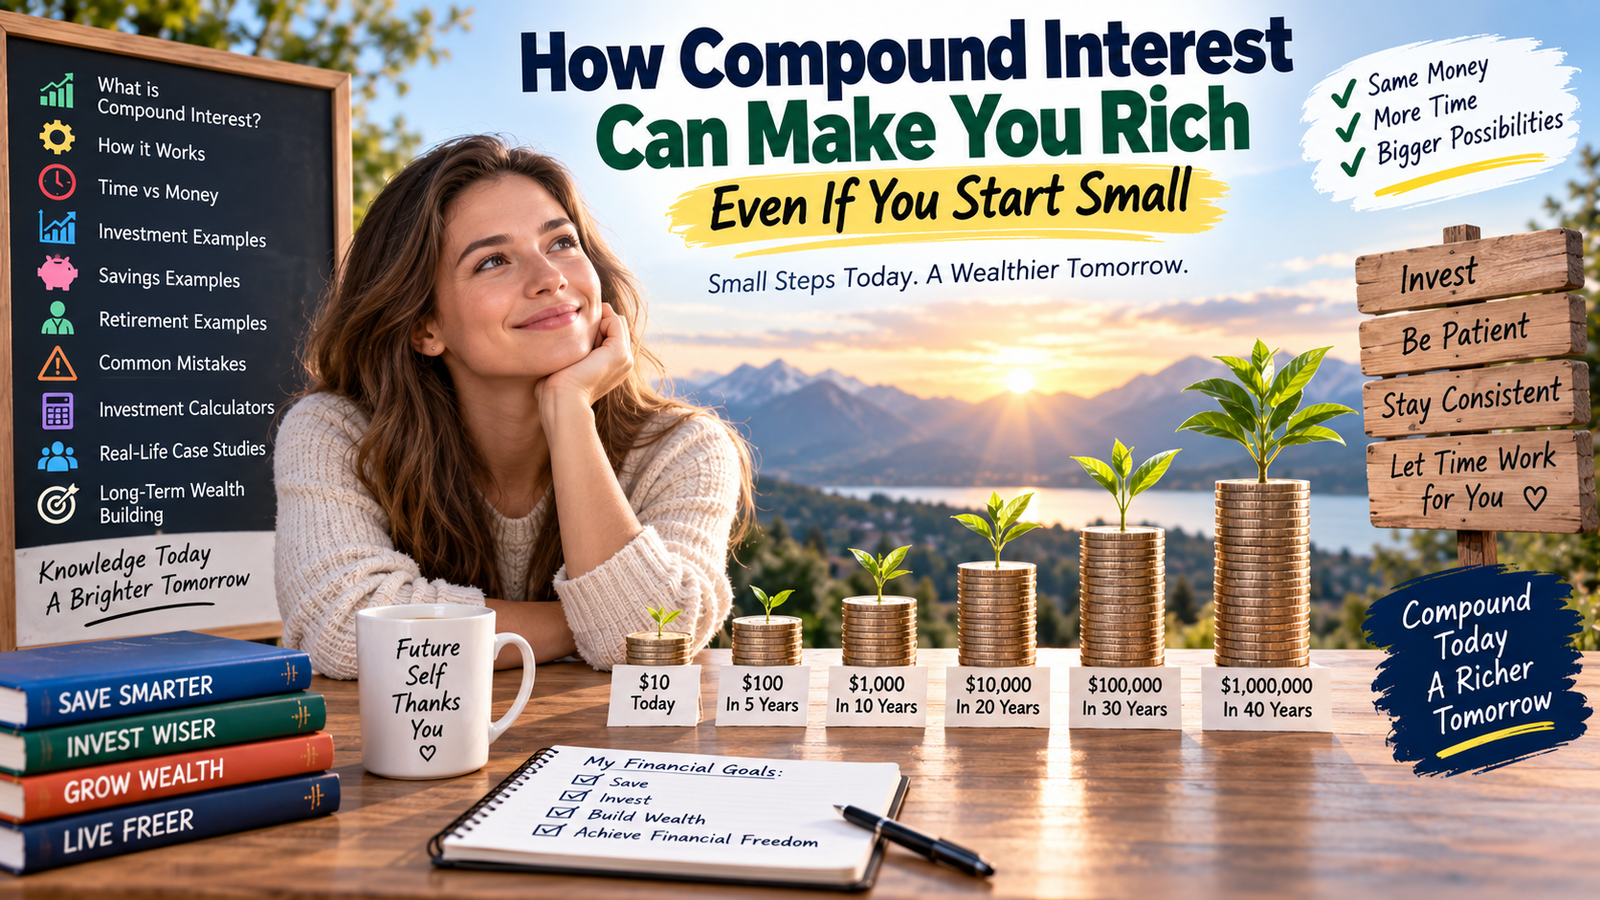
    How Compound Interest Can Make You Rich Even If You Start Small

    How Small Savings and Investments Can Grow Into Significant Long-Term Wealth Through Time and Consistency

    Introduction

    You Don’t Need to Start Rich to Build Wealth

    One of the biggest misconceptions about wealth building is that you need a large amount of money before investing becomes worthwhile.

    You don’t.

    Starting with $10, $50, $100 or $500 may seem insignificant when compared with the large investment portfolios discussed in financial media. But when money is invested consistently and allowed to grow over many years, something powerful can happen: compound growth.

    Compound interest means you can potentially earn returns not only on the money you originally saved or invested, but also on previous interest or investment returns.

    This creates a snowball effect.

    At first, progress can appear frustratingly slow. As time passes, however, the growth generated by your accumulated money can become increasingly important.

    The U.S. Securities and Exchange Commission’s Investor.gov provides a compound-interest calculator that demonstrates how savings can potentially grow over time, while the Consumer Financial Protection Bureau provides educational resources for establishing stronger saving habits.

    The lesson is simple:

    You don’t necessarily need a large starting amount. You need consistency, reasonable returns, and—most importantly—time.

    What Is Compound Interest?

    Compound interest is interest calculated on your original principal plus previously accumulated interest.

    Imagine depositing $1,000 into an account earning a hypothetical 5% annually.

    After the first year:

    $1,000 × 5% = $50

    Your balance becomes:

    $1,050

    If the money remains in the account, the second year’s interest is calculated on $1,050 rather than only the original $1,000.

    At 5%, that would produce:

    $52.50

    Your balance becomes:

    $1,102.50

    The extra $2.50 may appear insignificant.

    But over many compounding periods, the difference can become much larger.

    Investor.gov explains the concept through its educational material on compound interest, and its compound interest calculator allows investors to test different hypothetical scenarios.

    The fundamental principle is:

    Your money can potentially begin earning money on money it previously earned.

    How Does Compound Interest Work?

    A simplified annual compounding formula is:

    Future Value = Principal × (1 + Rate)^Time

    Suppose you invest $5,000 and hypothetically earn 7% annually for 20 years without adding additional money.

    The calculation would be approximately:

    $5,000 × (1.07)^20 = $19,348

    Your original $5,000 would have potentially grown to approximately $19,348.

    That does not mean every investment will return 7%. Investment returns fluctuate and can be negative. The example simply demonstrates the mathematics of compounding.

    The Investor.gov compound-interest calculator lets readers experiment with principal, contributions, interest rates and time, while FINRA’s investing resources explain important concepts investors should understand before putting money at risk.

    Time vs. Money: Why Starting Early Can Matter More Than Starting Big

    One of the most important lessons about compound growth is that time can compensate for a relatively small beginning.

    Consider two hypothetical investors.

    Investor A: Starts at Age 20

    Investor A invests $200 every month from age 20 until age 60.

    Total contributions:

    $200 × 12 × 40 = $96,000

    At a hypothetical 7% annual return compounded monthly, the portfolio could grow to roughly $525,000.

    Investor B: Starts at Age 40

    Investor B also invests $200 monthly but starts at age 40 and continues until 60.

    Total contributions:

    $200 × 12 × 20 = $48,000

    At the same hypothetical return, the portfolio could grow to roughly $104,000.

    The difference isn’t simply because Investor A contributed more.

    Investor A’s earliest contributions had decades longer to potentially compound.

    This illustrates why the Investor.gov saving and investing resources encourage understanding long-term investing, while the FINRA investor education center provides resources for making informed investment decisions.

    Starting early can be more powerful than waiting until you have a large amount of money.

    Small Monthly Investments Can Become Significant

    Suppose someone begins investing $100 per month at age 25.

    Assume, purely for illustration, an average annual return of 7%.

    If that person continues for 40 years, their personal contributions total:

    $48,000

    Yet the hypothetical investment balance could eventually reach approximately $262,000.

    Increase the contribution to $300 monthly under the same hypothetical assumptions, and the eventual balance could approach approximately $787,000.

    Again, these are illustrations—not guaranteed investment outcomes.

    Actual results depend on market performance, investment fees, taxes, contribution timing and other factors.

    The lesson is not that 7% is guaranteed.

    The lesson is that:

    Small Amount + Consistency + Return + Time = Potentially Significant Growth

    Compound Growth in a Savings Account

    Compounding does not apply only to stock-market investments.

    Interest-bearing savings accounts can also compound.

    Suppose you deposit $10,000 into a savings account earning a hypothetical 4% annually and leave the interest in the account.

    After one year, approximately:

    $10,400

    After five years:

    $12,167

    After ten years:

    $14,802

    The exact result depends on the account’s rate and compounding frequency.

    Savings accounts generally offer lower expected returns than riskier investments, but they can be appropriate for emergency funds and shorter-term financial goals where protecting principal and maintaining liquidity are priorities.

    The CFPB savings resources provide information about developing savings strategies, while U.S. readers can learn about insured bank deposits from the Federal Deposit Insurance Corporation.

    Readers outside the United States should check the deposit-protection rules and regulated financial institutions in their own countries.

    Compound Growth and Retirement

    etirement planning is one of the clearest examples of why compounding matters.

    Imagine a 25-year-old contributes $250 monthly toward long-term retirement investments.

    At a hypothetical 7% annual return, continuing until age 65 could potentially produce approximately $656,000.

    Personal contributions would total only:

    $250 × 12 × 40 = $120,000

    Much of the hypothetical difference would come from investment growth and compounding.

    A person who waits until 45 has only 20 years before reaching 65. Achieving a similar result would require dramatically larger contributions or substantially different investment outcomes.

    The Investor.gov retirement toolkit provides educational resources for retirement investors, while FINRA’s retirement resources explain important considerations when preparing financially for retirement.

    The Rule of 72: A Simple Compounding Shortcut

    A popular mental shortcut called the Rule of 72 estimates how long an investment might take to double at a fixed rate.

    Divide 72 by the hypothetical annual return.

    For example:

    72 ÷ 6 = approximately 12 years

    At 6%, money would take roughly 12 years to double.

    At 8%:

    72 ÷ 8 = approximately 9 years

    This is only an approximation, but it illustrates the relationship between returns and time.

    Be careful, however: higher potential returns generally involve greater investment risk. Never select an investment simply because it advertises a high return.

    Investment Example: $50 Per Week

    Suppose you invest $50 every week.

    That is approximately:

    $2,600 per year

    Over 30 years, your direct contributions would total approximately:

    $78,000

    If those contributions achieved a hypothetical long-term return, compound growth could potentially make the final portfolio significantly larger than the amount personally contributed.

    This is why consistency matters.

    Many people wait for a future moment when they expect to have thousands of dollars available to invest.

    That moment may never arrive.

    Starting with manageable recurring contributions can be more effective than endlessly waiting for perfect financial circumstances.

    Savings Example: The Young Worker

    Consider Maya, age 22.

    She earns a modest salary and believes investing is only for wealthy people.

    She decides to begin with $25 per week.

    That equals approximately $100–$110 monthly.

    As her income rises, she gradually increases the amount.

    At 25, she contributes $150 monthly.

    At 30, she increases it to $250.

    At 35, she contributes $400.

    Her greatest advantage isn’t that she started wealthy.

    She didn’t.

    Her advantage is that she established the habit early and increased contributions as her financial capacity improved.

    Retirement Example: Starting at 25 vs. Starting at 35

    Consider two hypothetical people.

    Daniel Starts at 25

    He invests $300 monthly until age 65.

    At a hypothetical 7% annual return, his account could grow to approximately $787,000.

    Michael Starts at 35

    Michael invests the same $300 monthly until age 65.

    At the same hypothetical return, his account could grow to approximately $366,000.

    Daniel had only ten additional years.

    But those ten years gave his earliest contributions significantly more time to compound.

    This demonstrates one of the most important principles in long-term wealth building:

    The cost of waiting can be enormous.

    What If You Are Already 40, 50 or Older?

    Do not interpret the importance of starting early as meaning it is too late to start.

    Starting today still gives your money more time than starting five years from now.

    Someone beginning later can potentially compensate in several ways:

    • Increase contributions
    • Reduce unnecessary expenses
    • Extend the investment horizon
    • Increase income
    • Use appropriate retirement accounts
    • Avoid excessive investment fees
    • Develop additional income sources

    The best time to start may have been years ago.

    The next available opportunity is now.

    Compound Interest Can Also Work Against You

    Compounding has another side.

    Debt can compound too.

    If you carry expensive debt and repeatedly fail to pay it down, interest can accumulate on the outstanding balance.

    This is particularly dangerous with high-interest credit cards and certain short-term loans.

    Instead of your money generating more money for you, interest charges can transfer increasing amounts of your future income to lenders.

    The Consumer Financial Protection Bureau’s credit-card resources provide educational information about credit cards, while the CFPB debt collection and financial education resources can help consumers better understand debt-related issues.

    The goal is to put compounding on your side of the financial equation whenever possible.

    Common Compound-Interest Mistakes

    1. Waiting Until You Earn More

    People frequently say:

    “I’ll start investing when I earn more.”

    Then income rises—and expenses rise with it.

    Start with an affordable amount and increase it gradually.

    2. Expecting Unrealistically High Returns

    Be suspicious of anyone promising extremely high, guaranteed investment returns.

    The Investor.gov fraud resources explain common warning signs of investment fraud, while FINRA BrokerCheck allows U.S. investors to research investment professionals and firms.

    3. Constantly Withdrawing Investments

    Compounding needs time.

    Frequently withdrawing long-term investments interrupts the process and may create taxes, fees or missed growth opportunities.

    4. Ignoring Investment Fees

    Small percentage fees can have large long-term effects.

    The SEC’s Investor Bulletin on fees and expenses explains why investment costs deserve attention.

    5. Taking Too Much Risk

    Compounding cannot help if catastrophic losses destroy your capital.

    Diversification and appropriate risk management matter.

    Investor.gov provides an explanation of diversification, and FINRA offers broader investing guidance.

    Use Compound Interest Calculators Before Setting Goals

    You do not have to calculate decades of compound growth manually.

    Online calculators allow you to experiment with:

    Starting amount
    Monthly contribution
    Estimated return
    Investment period
    Compounding frequency

    The Investor.gov Compound Interest Calculator is a useful starting point.

    You can also explore Investor.gov’s broader collection of financial calculators.

    Try several scenarios.

    What happens if you invest $100 monthly instead of $50?

    What happens if you start five years earlier?

    What if you increase contributions by $50 every year?

    What happens if returns are lower than expected?

    Scenario planning can help transform an abstract financial goal into a practical monthly target.

    Real-Life Case Study 1: Starting Small

    Imagine Anna, age 21, can afford only $50 per month.

    She feels embarrassed because friends online discuss investing thousands.

    But Anna begins anyway.

    After receiving salary increases, she gradually moves from:

    $50 → $100 → $200 → $300 monthly

    Her first $50 contribution wasn’t important because it instantly made her rich.

    It was important because it established the behavior that could continue for decades.

    Her wealth-building engine started early.

    Real-Life Case Study 2: The High Earner Who Waited

    James earns considerably more than Anna.

    But he continually postpones investing.

    At 25, he says he’ll begin at 30.

    At 30, he buys a more expensive vehicle.

    At 35, he upgrades his lifestyle again.

    At 40, he finally begins investing aggressively.

    James may still build substantial wealth because his income allows larger contributions.

    But money invested at 40 does not have the same amount of time to compound before traditional retirement age as money invested at 20 or 25.

    High income is valuable.

    High income combined with time is considerably more powerful.

    Real-Life Case Study 3: The Consistent Family

    Consider a family that automatically saves and invests part of every paycheck.

    They don’t try to predict which investment will become the next global sensation.

    They establish emergency savings, manage expensive debt, contribute regularly to diversified long-term investments and increase contributions whenever household income rises.

    Some years markets perform strongly.

    Other years investments decline.

    They remain focused on their long-term financial plan rather than reacting emotionally to every headline.

    Their primary advantage is not prediction.

    It is discipline and consistency.

    How to Use Compound Growth for Long-Term Wealth Building

    Compound interest becomes most powerful when combined with several other financial habits.

    Start Early

    Give your money as much time as reasonably possible.

    Contribute Consistently

    Automate recurring savings or investments where appropriate.

    Increase Contributions

    Whenever income increases, consider increasing your contribution before lifestyle inflation absorbs the entire raise.

    Reinvest Returns

    Allowing interest, dividends or other investment returns to remain invested can support compounding.

    Diversify

    Avoid depending entirely on one company, industry or speculative asset.

    Keep Costs Reasonable

    Fees reduce the amount of money remaining in your portfolio to compound.

    Avoid Emotional Decisions

    Fear can cause investors to sell during downturns, while greed can encourage buying speculative investments after dramatic price increases.

    Protect Your Financial Foundation

    Maintain appropriate emergency savings so you are less likely to liquidate long-term investments whenever an unexpected expense occurs.

    The Long-Term Wealth Formula

    Sustainable wealth building can be summarized simply:

    Earn → Save → Invest → Reinvest → Compound → Increase Contributions → Repeat

    You don’t need to execute this perfectly.

    You need to continue doing it.

    The first years can feel slow because your contributions create most of the growth.

    Eventually, if investments perform positively over time, investment growth itself can become a much larger part of the portfolio.

    That is when the compounding snowball becomes easier to see.

    A Simple Action Plan to Start Today

    Step 1: Calculate how much you can realistically save every month.

    Step 2: Build an appropriate emergency reserve.

    Step 3: Address expensive consumer debt.

    Step 4: Learn the basics of diversified investing.

    Step 5: Choose regulated financial products appropriate to your country and circumstances.

    Step 6: Automate contributions where possible.

    Step 7: Reinvest investment income when appropriate for your goals.

    Step 8: Increase contributions as your income rises.

    Step 9: Review your progress annually rather than obsessing over daily market movements.

    Step 10: Give your strategy time.

    The process is not glamorous.

    But successful long-term wealth building often isn’t.

    Conclusion

    Start Small, but Give Your Money Time to Grow

    Compound interest teaches one of the most encouraging lessons in personal finance:

    Your starting amount does not have to determine your final destination.

    Someone beginning with $25 or $50 may not feel like an investor.

    But that small beginning establishes something extremely valuable—a habit.

    As income increases, $50 can become $100.

    $100 can become $250.

    $250 can become $500.

    Meanwhile, earlier contributions have more time to potentially generate returns, and those returns can potentially generate additional returns.

    That is the power of compounding.

    Do not mistake the examples in this article for guaranteed investment outcomes. Markets fluctuate, savings rates change, inflation reduces purchasing power, taxes and fees matter, and every investment carries some degree of risk.

    But the fundamental mathematics remains powerful:

    Start early.
    Save consistently.
    Invest intelligently.
    Reinvest.
    Increase your contributions.
    Be patient.

    You do not need to wait until you are rich to begin investing.

    Consistent saving and investing over a long enough period may be one of the ways you build wealth in the first place.

    Educational Disclaimer: This article provides general financial education and does not constitute individualized financial, investment, retirement, tax or legal advice. Hypothetical returns are illustrations only and are not guaranteed. Investments can lose value, including principal. Financial products, taxes and regulations vary by country.
  • Emergency Funds Explained: Why Every Family Needs One Before Investing

    Emergency Funds Explained: Why Every Family Needs One Before Investing

    How to Build an Emergency Savings Fund, Protect Your Family From Financial Shocks and Prepare for Investing

    Introduction

    Financial Security Should Come Before Financial Growth

    Most families want their money to grow. They want to invest, buy property, build businesses, prepare for retirement and create a better financial future for their children. But before focusing entirely on investment returns, there is another financial priority that deserves attention: building an emergency fund.

    An emergency fund is money specifically reserved for expenses you did not reasonably expect—such as job loss, urgent medical costs, essential vehicle repairs, emergency travel or major home repairs. The Consumer Financial Protection Bureau’s emergency-fund guide explains that even relatively small savings can help families recover more quickly from financial shocks, while FINRA’s guidance for new investors recommends putting basic financial needs—including emergency savings—in order before beginning to invest.

    That distinction is important because emergency savings and investments serve different purposes. Investments are generally intended to grow money over time and may fluctuate in value. Emergency savings should emphasize safety, accessibility and liquidity.

    This guide explains how much to consider saving, where to keep the money, how to build your first reserve, how to prepare for family and medical emergencies, and how to rebuild your fund after you use it.

    What Is an Emergency Fund?

    An emergency fund is a dedicated pool of money reserved for unexpected and necessary financial expenses, rather than routine monthly spending or planned purchases. According to the CFPB, common uses include car and home repairs, medical bills and loss of income. FINRA’s financial-hardship guidance similarly recommends keeping emergency money somewhere safe and readily accessible rather than exposing it to investment risk.

    An emergency fund is therefore different from money for a holiday, new television, wedding, planned school fees or routine annual insurance premium. Those predictable costs can be handled through ordinary savings or sinking funds. Emergency savings should be protected for genuine financial shocks.

    Think of your emergency fund as a financial shock absorber. It does not prevent bad things from happening, but it can reduce the damage when they do.

    Why Build an Emergency Fund Before Investing?

    Investing can be an important part of long-term wealth creation, but investments can lose value—especially over short periods. If your entire financial reserve is invested and an emergency occurs during a market decline, you may be forced to sell at an unfavorable time. FINRA’s guidance for new investors recommends having funds available for emergencies before investing, while the CFPB emphasizes that emergency savings can reduce dependence on loans and credit cards after an unexpected expense.

    The principle can be summarized as:

    Emergency savings protect the present. Investments help finance the future.

    You may eventually need both. But building some financial resilience first can make your long-term investment strategy more sustainable.

    How Much Should You Save in an Emergency Fund?

    There is no universal amount appropriate for every household. Your target depends on family size, essential expenses, income stability, insurance, health circumstances, employment prospects and other sources of financial support. The CFPB recommends considering the unexpected expenses you have experienced previously when establishing your target, while FINRA describes three to six months of expenses as a useful goal while emphasizing that any amount you can afford to save is helpful.

    A practical approach is to build your fund in stages:

    Stage 1: First emergency cushion — $500, $1,000 or an achievable equivalent in your local currency.

    Stage 2: One month of essential expenses.

    Stage 3: Three months of essential expenses.

    Stage 4: Work toward three to six months—or another amount appropriate for your circumstances.

    For example, if your family’s essential monthly expenses are $2,500, three months would equal $7,500 and six months would equal $15,000. Someone with irregular income, dependents or uncertain employment may prefer a larger reserve than someone with highly stable income and strong household support

    Where Should You Keep Emergency Savings?

    Emergency money should generally satisfy three requirements: safe, accessible and separate from everyday spending. The CFPB emergency savings guide identifies dedicated bank or credit-union accounts as one option and warns that physical cash can be stolen, lost or destroyed. FINRA similarly recommends keeping emergency funds in a savings account or another safe location offering immediate access.

    Where available, consider a regulated savings account that provides competitive interest without sacrificing reasonable access to the money. Readers should check the deposit-insurance system applicable in their own country and verify account fees, withdrawal rules and institutional protections.

    Emergency savings generally should not depend on volatile stocks, cryptocurrencies or speculative assets. You don’t want to discover that the $10,000 you expected to use for an emergency is worth substantially less precisely when you need it.

    Building Your First Emergency Reserve From Scratch

    If you have no emergency savings today, don’t become discouraged by a target of several months of expenses. Start smaller. The CFPB specifically emphasizes that even small amounts can provide financial security, and its automatic-saving guidance recommends regular automatic transfers as one of the easiest ways to build savings consistently.

    Start with an amount you can maintain:

    $5 a week = $260 per year
    $10 a week = $520 per year
    $25 a week = $1,300 per year
    $50 a week = $2,600 per year

    If your income is irregular, consider saving a percentage of every payment instead of a fixed monthly amount.

    Bonuses, gifts, business profits, overtime payments and other occasional income can also accelerate progress. The key is to create a repeatable savings system rather than waiting for the mythical month when you suddenly have plenty of money left over.

    Make Emergency Saving Automatic

    Automation changes emergency saving from a monthly decision into a financial system. The CFPB recommends automatic transfers from checking to savings and notes that some workers may be able to divide direct deposits between accounts. Its separate automatic-saving guide similarly explains that recurring transfers can make consistent saving easier.

    For example, if you are paid every two weeks, arrange for $25 to move automatically into emergency savings after each paycheck. You would contribute approximately $650 over 26 pay periods without needing to manually make 26 separate saving decisions.

    When your income increases, increase the automatic contribution before your lifestyle absorbs the entire raise.

    What Counts as a Real Emergency?

    An emergency is generally unexpected, necessary and financially significant. The CFPB gives examples such as medical bills, car repairs, home repairs and loss of income, while its family emergency-preparedness guidance also highlights emergency travel and disaster-related costs.

    Common legitimate emergencies might include:

    • Essential vehicle repairs needed to get to work
    • Urgent medical or dental treatment
    • Sudden job loss
    • Emergency travel for a serious family situation
    • Critical home repairs
    • Temporary loss of income
    • Essential appliance replacement
    • Disaster-related expenses not immediately covered by insurance

    A discounted vacation, new smartphone, designer clothing or spontaneous shopping opportunity is generally not an emergency.

    Establish your family’s rules before temptation appears.

    Emergency Funds Can Help You Avoid Credit Card Debt

    Without cash reserves, a $1,500 emergency may become a $1,500 credit-card balance. Interest and fees can then make the original emergency substantially more expensive. The CFPB warns that using credit or loans for emergency expenses can turn a one-time financial shock into harder-to-repay debt, while FINRA recommends addressing high-interest debt as part of establishing a sound financial foundation.

    Credit cards can be useful financial tools when managed carefully, but they are not the same thing as emergency savings.

    An emergency fund allows you to use yesterday’s savings instead of tomorrow’s income to solve today’s problem.

    That difference can prevent one emergency from creating months or years of repayments.

    How Inflation Affects Your Emergency Fund

    Inflation gradually increases the cost of food, housing, transportation, utilities, healthcare and other necessities. That means an emergency target calculated several years ago may no longer cover the same number of months. Families can use an official inflation measure applicable to their country; for international comparisons and economic data, the World Bank’s inflation indicator provides country-level information, while the International Monetary Fund provides broader educational and economic resources on inflation.

    Review your emergency target at least annually.

    If essential monthly expenses rise from $2,000 to $2,400, a six-month target rises from $12,000 to $14,400.

    Interest earned on a savings account can help offset some loss of purchasing power, but the primary purpose of emergency money remains liquidity and financial protection, not maximizing investment returns.

    Preparing for Family Emergencies

    Family emergencies often affect more than one person and may require money immediately. Emergency travel, temporary caregiving, home repairs, natural disasters or supporting dependent children can create expenses that ordinary monthly budgets cannot absorb. The CFPB’s family emergency guide recommends financial preparation before disasters occur, while the CFPB’s broader emergency-fund guidance emphasizes establishing clear rules for when emergency savings should be used.

    Families should discuss:

    Who can access the emergency account?
    What qualifies as an emergency?
    Where are important financial documents?
    Which expenses are insured?
    Who should be contacted during a crisis?

    Families in areas exposed to natural disasters may also benefit from keeping a small, secure amount of physical cash for situations when electricity, payment networks or ATMs are unavailable. However, the CFPB notes that cash stored at home can be vulnerable to theft, fire or other loss.

    Preparing for Medical Emergencies

    Medical emergencies can create both direct and indirect financial costs. Families may face treatment bills, deductibles, medication, transportation, childcare or lost wages while someone recovers. Emergency savings can help absorb costs not immediately covered by insurance; the CFPB emergency-fund guide specifically identifies unexpected medical bills as a common reason for emergency savings, while the World Health Organization provides global information about health financing and financial protection.

    Healthcare systems vary dramatically across countries. Some countries provide broad public healthcare coverage; others place more costs directly on households.

    Review your health coverage and understand what you might have to pay yourself. Where appropriate, maintain insurance or other health coverage alongside emergency savings.

    An emergency fund should complement insurance—not necessarily replace it.

    Preparing Financially for Job Loss

    Job loss is particularly difficult because it can remove income while household expenses continue. The CFPB notes that savings can help households weather furloughs, job losses and reduced working hours, while FINRA’s hardship guide identifies job loss as a major financial shock for which advance planning can help.

    Calculate your survival budget now.

    Identify what your household would absolutely need each month for:

    Housing
    Basic food
    Utilities
    Essential transportation
    Insurance
    Healthcare
    Minimum debt obligations
    Necessary communication

    Suppose normal household spending is $4,000 monthly, but essential survival expenses are $2,700. A $10,800 emergency fund could potentially cover approximately four months of those essential costs.

    Knowing this number gives your emergency-fund goal a concrete purpose.

    Should You Invest While Building an Emergency Fund?

    This is not always an either-or decision. Individual circumstances differ, especially when employer retirement contributions, pensions, high-interest debt, taxes or other benefits are involved. However, FINRA’s new-investor guidance recommends ensuring that basic needs and emergency savings are addressed before investing, while the CFPB explains how a dedicated cash reserve protects against financial shocks.

    A beginner might therefore prioritize building an initial emergency cushion before committing significant discretionary money to higher-risk investments.

    As the reserve becomes stronger, the balance can gradually shift toward long-term investment goals.

    Remember:

    Emergency fund = protection and liquidity.
    Investment portfolio = long-term growth with risk.

    Trying to make one account perform both jobs can create problems.

    What Should You Do After Using Your Emergency Fund?

    Using an emergency fund for a genuine emergency does not mean you failed.

    That is exactly why the money existed.

    The CFPB explicitly advises consumers who use their emergency savings to work on building the fund again, while its saving resources encourage establishing recurring contributions that make rebuilding more systematic.

    Suppose you had $8,000 and used $2,500 for an urgent home repair.

    Your new balance is $5,500.

    Create a temporary rebuilding plan. Perhaps redirect some discretionary spending, bonuses or extra income toward replacing the $2,500. If you were previously contributing $100 monthly, temporarily increasing that to $200 may accelerate recovery if your budget permits.

    Do not punish yourself for using emergency savings appropriately.

    Use it. Recover. Rebuild it. Continue.

    Emergency Fund Checklist for Families

    Before moving aggressively toward investing, ask:

    ☐ Do we have a dedicated emergency savings account?
    ☐ Do we know our essential monthly expenses?
    ☐ Have we established an initial savings target?
    ☐ Could we handle an urgent vehicle or home repair?
    ☐ Have we planned for possible job loss?
    ☐ Have we considered medical expenses?
    ☐ Do we understand our insurance coverage?
    ☐ Have we defined what qualifies as an emergency?
    ☐ Is the money reasonably accessible?
    ☐ Is it protected from everyday spending?
    ☐ Are we contributing automatically?
    ☐ Do we review the target as living costs change?
    ☐ Do we have a plan for rebuilding the fund after using it?

    If several answers are “no,” strengthening your financial safety net may deserve priority.

    Conclusion

    Build Your Financial Safety Net Before Chasing Returns

    Investing is exciting because it offers the possibility of growth.

    Emergency savings rarely feels exciting.

    But financial security is not built only by maximizing returns. It is also built by surviving financial shocks without destroying the progress you have already made.

    A strong emergency fund gives your family options.

    When the car breaks down, you have money.

    When an urgent medical bill appears, you have a reserve.

    When employment suddenly ends, you have time to make better decisions.

    When an unexpected family situation requires travel or caregiving, you are better prepared.

    And when markets fall, you may be less likely to sell long-term investments simply because you urgently need cash.

    Start small if necessary. Establish your first $500, $1,000 or an appropriate amount in your local currency. Then work toward one month of essential expenses and gradually build a larger reserve suited to your household.

    Keep it safe. Keep it accessible. Protect it from unnecessary spending. Adjust it as your family’s expenses change.

    And when you eventually use it, rebuild it.

    Emergency savings protect your family today so that your long-term investments have a better chance to build your future.

    Educational Disclaimer: This article provides general financial education and does not constitute individualized financial, investment, tax, insurance, medical or legal advice. Appropriate emergency savings amounts and financial products vary by household and country. Verify local deposit protections, account rules, taxes and regulations before making financial decisions.

  • Stock Market Investing for Beginners: Everything You Need to Know Before Buying Your First Stock

    Stock Market Investing for Beginners: Everything You Need to Know Before Buying Your First Stock

    Explore digital financial market

    Introduction

    Buying your first stock can feel intimidating.

    You may hear unfamiliar terms such as market capitalization, IPO, dividend yield, stock index, growth stock, value stock, bull market, and dollar-cost averaging and wonder where to begin.

    The good news is that you do not need to become a professional trader before learning how stock investing works.

    At its core, buying stock means acquiring an ownership interest in a company.

    But investing involves risk. Stock prices can rise or fall, companies can struggle, and investors can lose money. That is why education should come before your first investment.

    Reliable starting resources include Investor.gov, the International Organization of Securities Commissions, and your own country’s official securities regulator.

    This guide explains the essential stock-market concepts every beginner should understand before investing real money

    1. What Is the Stock Market?

    The stock market is a broad system through which investors buy and sell ownership interests in publicly traded companies.

    When you purchase shares, you become a shareholder.

    If a company grows and investors become willing to pay more for its shares, your investment may increase in value. If the business struggles or investors become less optimistic, the share price may decline.

    Stock markets connect businesses seeking capital with investors seeking opportunities to participate in business ownership.

    Investor.gov’s stock guide provides additional beginner education.

    2. Why Do Companies Issue Shares?

    Businesses need capital to expand.

    A company may need money to:

    • Develop new products
    • Hire employees
    • Build factories
    • Enter new countries
    • Acquire competitors
    • Invest in technology
    • Reduce debt

    One way of raising capital is selling ownership shares to investors.

    Unlike a conventional loan, issuing equity generally does not require the company to repay shareholders like lenders. Instead, shareholders participate in the company’s future risks and potential rewards.

    3. Understanding Stock Exchanges

    A stock exchange is an organized marketplace where eligible securities can be traded.

    Famous examples include the New York Stock Exchange and Nasdaq in the United States, London Stock Exchange in the United Kingdom, Japan Exchange Group, Deutsche Börse, Hong Kong Exchanges and Clearing, Johannesburg Stock Exchange, National Stock Exchange of India, and many others.

    The World Federation of Exchanges provides information about exchanges and clearing organizations around the world.

    Investors normally access exchanges through authorized brokers rather than walking into an exchange and purchasing shares directly.

    4. What Is Market Capitalization?

    Market capitalization, often called market cap, estimates a publicly traded company’s equity market value.

    A simplified calculation is:

    Market Capitalization = Share Price × Shares Outstanding

    For example, if a company has 100 million outstanding shares trading at $20:

    100 million × $20 = $2 billion market capitalization

    Companies are frequently described as:

    Large-cap — larger established companies

    Mid-cap — medium-sized publicly traded companies

    Small-cap — smaller publicly traded companies

    Definitions and thresholds can differ between markets and investment providers.

    5. Common Stock vs. Preferred Stock

    Not every stock has identical characteristics.

    Common stock typically represents ordinary company ownership and may provide voting rights. Common shareholders may also receive dividends when declared.

    Preferred stock can have characteristics of both stocks and fixed-income securities. Preferred shareholders may receive specified dividend preferences and generally rank ahead of common shareholders for certain claims, although exact rights depend on the security.

    Investor.gov provides more information through its investment-products resources.

    6. IPOs Explained

    An Initial Public Offering (IPO) occurs when a company first offers shares to the public under an applicable regulatory process.

    IPOs often receive enormous media attention.

    But excitement does not guarantee investment success.

    A newly listed company may rise dramatically—or fall substantially.

    Before investing, study:

    The company’s business model, revenue, profitability, competition, debt, risks, management and valuation.

    Never buy an IPO simply because it is popular on social media.

    7. How Stock Brokers Work

    A broker provides access to markets and facilitates securities transactions.

    Modern brokers may provide:

    Trading platforms, investment accounts, market information, research tools, order execution and portfolio reporting.

    Before opening an account, examine:

    Regulation, fees, commissions, currency-conversion costs, available investments, withdrawal policies, account protections and customer support.

    Because regulations differ worldwide, verify brokers with your country’s official securities regulator.

    IOSCO can help international readers identify securities regulators and investor-protection resources.

    8. Understanding Stock Market Indices

    Well-known examples include:

    S&P 500 — United States

    Dow Jones Industrial Average — United States

    FTSE 100 — United Kingdom

    DAX — Germany

    Nikkei 225 — Japan

    Indices help investors understand how particular segments of a market are performing.

    However, you generally cannot purchase an index itself. Investors can gain exposure through investment products designed to track an index, such as certain index funds or exchange-traded funds.

    9. Dividends Explained

    Some companies distribute part of their earnings or available capital to shareholders through dividends.

    For example, suppose you own:

    100 shares

    and the company pays:

    $1 per share annually

    Your annual dividend would be:

    $100, before applicable taxes.

    But dividends are not guaranteed. Companies can reduce, suspend or eliminate them.

    Do not buy a company solely because it has a high dividend yield. A very high yield can sometimes reflect a falling share price or concerns about the business.

    10. Growth Stocks

    Growth companies are businesses investors expect to expand revenue or earnings relatively rapidly.

    They may operate in areas such as:

    Technology, biotechnology, digital services, emerging industries or rapidly expanding consumer markets.

    Growth stocks can potentially deliver substantial gains.

    They can also carry high valuations and fall sharply when expectations change.

    A great company can still be a poor investment if purchased at an excessively high price.

    11. Value Stocks

    Value investing focuses on companies that an investor believes are trading below their underlying economic value.

    Investors may examine:

    Earnings, cash flow, assets, debt, profitability and valuation ratios.

    The objective is not simply finding the cheapest stock.

    A low-priced company may be inexpensive for a legitimate reason.

    Value investors try to distinguish between:

    Undervalued businesses and weak businesses that merely look cheap.

    12. Blue-Chip Stocks

    “Blue chip” generally describes large, established companies with substantial operating histories and recognizable businesses.

    They are often viewed as financially stronger than smaller speculative companies.

    But blue-chip does not mean risk-free.

    Large corporations can lose market share, face recessions, experience management failures or decline as industries change.

    Every investment still requires analysis.

    13. Small-Cap vs. Large-Cap Companies

    Small-cap companies may have greater room to expand but can also face greater business and market risk.

    Large-cap companies may have:

    More established businesses, greater access to capital, broader operations and stronger financial resources.

    However, smaller companies sometimes grow much faster.

    Rather than assuming one category is always superior, investors can consider diversification across appropriate company sizes.

    Investor.gov explains the importance of diversification.

    14. Understand Stock Market Cycles

    Stock markets do not rise continuously.

    Markets experience:

    Expansion, optimism, declines, fear, recovery and new growth periods.

    A sustained rising market is commonly called a bull market.

    A significant sustained decline is commonly called a bear market.

    Economic recessions, interest rates, inflation, corporate earnings, political events and investor expectations can all influence markets.

    Beginners should understand that market declines are part of investing.

    15. Reading Stock Charts

    Stock charts display historical price behavior.

    Common chart information includes:

    Price, time, opening price, closing price, highs, lows and sometimes trading volume.

    Candlestick charts can show:

    Open
    High
    Low
    Close

    for a selected period.

    Charts can help investors understand price history and volatility.

    But a chart cannot guarantee what a stock will do tomorrow.

    16. Long-Term Investing

    Long-term investing means focusing on years rather than tomorrow’s market movement.

    An investor might evaluate:

    Business quality
    Competitive advantages
    Financial strength
    Growth prospects
    Valuation
    Management
    Long-term economic trends

    Long-term investing can also reduce the temptation to react emotionally to every market headline.

    This does not mean ignoring your portfolio.

    It means distinguishing between short-term market noise and long-term investment objectives.

    17. Dollar-Cost Averaging

    Dollar-cost averaging involves investing equal amounts at regular intervals regardless of market fluctuations.

    For example:

    $200 every month

    rather than trying to predict the perfect day to invest a larger amount.

    Investor.gov explains dollar-cost averaging as investing equal portions at regular intervals regardless of market movements.

    It does not guarantee profits or prevent losses, but it can create investing discipline.

    18. Common Stock Market Myths

    Myth: The stock market is guaranteed to make you rich.

    Reality: Investments can lose value.

    Myth: You need to be wealthy before investing.

    Reality: Depending on available investment products and local rules, people may be able to begin with relatively small amounts.

    Myth: A low share price means a stock is cheap.

    Reality: Share price alone says little about company valuation.

    Myth: A stock that has fallen must eventually recover.

    Reality: Some companies never recover.

    Myth: Professional investors always know where markets are going.

    Reality: Future market movements remain uncertain.

    19. Understand the Risks Before Investing

    Stocks can create long-term wealth, but they carry risk.

    Important risks include:

    Market risk — broad markets decline.

    Company risk — the business performs poorly.

    Valuation risk — you pay too much.

    Economic risk — recessions or inflation affect businesses.

    Currency risk — international investments fluctuate with exchange rates.

    Liquidity risk — an investment may become difficult to sell efficiently.

    Behavioral risk — fear and greed cause poor decisions.

    Diversification can help manage certain risks, but it cannot eliminate the possibility of loss.

    20. Before Buying Your First Stock

    Ask yourself:

    Do I understand the company?

    Why am I buying it?

    What could cause it to lose value?

    Am I investing money I may need soon?

    Is my portfolio diversified?

    What fees and taxes apply?

    Is my broker properly regulated?

    Am I buying because of research—or because social media created FOMO?

    If you cannot explain your investment in simple language, continue learning before committing money.

    Frequently Asked Questions

    How Much Money Do I Need to Start Investing?

    There is no universal amount. Minimum investment requirements depend on your country, broker and investment product.

    Your financial stability matters more than reaching an arbitrary number.

    Can I Lose All My Money in Stocks?

    Individual stocks can lose most or even all of their value in extreme circumstances. This is one reason diversification matters.

    Are Stocks Better Than Savings Accounts?

    They serve different purposes.

    Savings are generally more appropriate for emergency reserves and near-term needs, while stocks may be appropriate for longer-term goals where an investor can tolerate market risk.

    Should Beginners Buy Individual Stocks or Funds?

    Some beginners use diversified funds because one investment can provide exposure to many securities. Others research individual companies.

    Neither approach eliminates risk.

    Learn about mutual funds and ETFs before deciding.

    Can AI Pick Winning Stocks?

    AI can help organize information and analyze data, but it cannot guarantee which stocks will rise.

    Be especially skeptical of anyone selling an “AI system” promising guaranteed stock-market profits.

    When Is the Best Time to Buy Stocks?

    Nobody consistently knows the perfect market entry point in advance.

    Long-term investors often focus more on financial goals, valuation, diversification and disciplined contributions than predicting tomorrow’s price.

    Is Stock Investing the Same Worldwide?

    The basic ownership concept is similar, but taxes, market structures, investment products and investor protections vary by jurisdiction.

    Always consult your country’s securities regulator and tax authority.

    Where Can Beginners Learn More?

    Strong educational starting points include Investor.gov, IOSCO, the World Federation of Exchanges, and the official stock exchange and securities regulator in your country.

    Conclusion

    Stock-market investing can become a powerful part of a long-term financial plan, but your first objective should not be finding the stock that will make you rich overnight.

    Your first objective should be understanding what you are buying.

    Learn:

    How stocks represent ownership.
    Why companies issue shares.
    How exchanges and brokers work.
    How market capitalization works.
    How dividends work.
    How growth and value stocks differ.
    Why diversification matters.
    How market cycles affect investors.
    Why long-term thinking matters.
    How risk can be managed.

    Then develop a disciplined investment process.

    Learn → Save → Research → Diversify → Invest → Stay Consistent → Review → Think Long Term

    Your first stock does not need to become your greatest investment.

    It needs to become part of a financial journey built on education rather than speculation.

    Markets will rise.

    Markets will fall.

    Companies will succeed.

    Others will fail.

    The investor’s job is not to predict everything perfectly.

    It is to make informed decisions, manage risk, remain disciplined and give sound financial habits enough time to work.

  • The Psychology of Wealth: How Millionaires Think Differently About Money

    The Psychology of Wealth: How Millionaires Think Differently About Money

    Wealth-Building Mindsets, Investing Habits and Long-Term Strategies for Creating Financial Independence

    Introduction

    Wealth Often Begins With a Different Way of Thinking

    Why do some people continually increase their wealth while others earn good incomes for decades yet accumulate relatively few assets?

    Income certainly matters, but income alone does not determine wealth. The way people think about earning, spending, saving, investing, risk, opportunity and time can strongly influence what eventually happens to their money.

    Millionaires are not one homogeneous group, and there is no secret mindset guaranteed to make someone wealthy. Some inherit wealth. Others build businesses, develop high-income careers, invest consistently, own property or combine several strategies. Economic opportunity, education, family circumstances, government policies and luck can also influence outcomes.

    Nevertheless, many financially successful people demonstrate behaviors worth studying: they tend to think beyond today’s paycheck, acquire productive assets, continually improve valuable skills, cultivate useful relationships, manage rather than blindly avoid risk, and understand that sustainable wealth generally requires time.

    Here are some of the most important lessons behind the psychology of wealth and how you can apply them to your own financial journey.

    1. Wealthy Thinking Focuses on Ownership, Not Just Income

    Most people naturally think about money in terms of income:

    How much do I earn every month?

    A wealth-building perspective adds another question:

    What do I own that can potentially increase in value or produce income?

    Someone can earn a large salary and still accumulate little wealth if nearly everything is consumed.

    Another person may earn less but consistently acquire productive assets.

    The distinction between earning money and building assets is fundamental.

    2. Millionaires Often Think in Years, Not Weeks

    Short-term thinking asks:

    What can this money buy today?

    Long-term thinking asks:

    What could this money become over the next 10, 20 or 30 years?

    This does not mean wealthy people never enjoy their money. It means immediate consumption is weighed against future opportunity.

    Time is one of the most powerful resources available to investors and entrepreneurs.

    3. They Understand the Power of Compounding

    Compounding occurs when returns potentially generate additional returns over time.

    Consider a hypothetical example.

    Someone who invests $500 monthly for 30 years and hypothetically earns an average 7% annual return would contribute $180,000 personally, while the account could potentially grow to considerably more because of compounding.

    Actual investment returns are never guaranteed, but the example illustrates an important principle:

    Time can be as important as the amount invested.

    That is why starting earlier can provide a major advantage.

    4. They Pay Themselves Before Expanding Their Lifestyle

    When income increases, many people immediately increase consumption.

    A wealth-building approach directs part of additional income toward assets before upgrading lifestyle.

    Suppose your monthly income rises by $1,000.

    Instead of automatically adding $1,000 to monthly spending, you might allocate part toward investments, emergency savings, education or productive business assets.

    The result is simple:

    Income rises → Asset accumulation rises.

    5. They Understand the Difference Between Looking Rich and Being Wealthy

    Visible consumption can easily be mistaken for wealth.

    A luxury vehicle, designer clothing or expensive home says little about someone’s actual net worth if those purchases are heavily financed.

    Much of genuine wealth is invisible.

    It exists in investment accounts, business ownership, savings, property equity and other assets.

    A powerful psychological shift is learning to value financial independence more than the appearance of financial success.

    6. They Develop Consistent Investing Habits

    Successful long-term investing rarely depends on finding one magical investment.

    It more often involves consistency.

    That can mean regularly allocating money toward diversified investments appropriate to one’s objectives, time horizon and risk tolerance.

    The amount may initially be small.

    The habit comes first.

    As income grows, contributions can potentially grow with it.

    7. They Don’t Confuse Investing With Gambling

    Investing should involve understanding what you own, why you own it, what risks exist and how the investment fits your overall strategy.

    Buying something simply because its price is rising is speculation—not automatically sound investing.

    A wealth-oriented investor asks:

    What is the potential return?
    What could go wrong?
    How much could I lose?
    How long can I hold this investment?
    How does it fit my portfolio?

    Risk is evaluated rather than ignored.

    8. They Read to Solve Problems

    Reading can be one of the least expensive ways to access other people’s knowledge.

    Successful entrepreneurs and investors often learn from books, industry publications, financial reports, biographies, courses, research and other experienced people.

    The important lesson isn’t simply “millionaires read books.”

    It is:

    Successful people continually acquire information that improves their decisions.

    Read with a purpose.

    9. They Invest in Continuous Learning

    The modern economy changes rapidly.

    Technology changes.

    Industries change.

    Consumer preferences change.

    Artificial intelligence changes how certain jobs are performed.

    Skills that were valuable ten years ago may become less valuable, while entirely new opportunities emerge.

    Continuous learning helps protect your earning power.

    10. They Invest in Skills That Increase Their Value

    Not all education has the same economic return.

    Wealth-oriented learners often ask:

    What skill would make me more valuable?

    Depending on your location and industry, that could mean technology, healthcare, manufacturing, engineering, sales, finance, construction, digital marketing, management or entrepreneurship.

    Education becomes particularly powerful when it increases earning capacity.

    11. They Build Valuable Networks

    Relationships create access to information.

    A strong professional network can introduce you to employers, customers, investors, mentors, suppliers, partners and new ideas.

    Effective networking is not collecting hundreds of contacts.

    It is developing genuine, mutually valuable relationships.

    Give value before expecting value in return.

    12. They Learn From People Ahead of Them

    A good mentor can shorten the learning curve.

    Instead of repeating every mistake personally, you can learn from someone else’s experience.

    Ask successful people specific questions.

    What mistakes did they make?

    What skills mattered most?

    What would they do differently?

    Which opportunities do they see developing?

    Experience can provide lessons that textbooks cannot

    13. They Look for Problems Worth Solving

    Entrepreneurship fundamentally revolves around solving problems.

    Successful businesses generally provide something customers value:

    Convenience
    Entertainment
    Transportation
    Food
    Technology
    Education
    Healthcare
    Communication
    Financial services
    Productivity
    Security

    Instead of asking only, “How can I make money?”, entrepreneurs often ask:

    “What problem can I solve profitably?”

    Money becomes the result of creating value.

    14. They Think About Scalability

    An employee typically exchanges time for income.

    Some businesses and investments can potentially generate value without requiring an identical increase in personal hours.

    Software is an example: developing a product may require substantial work initially, but the same software can potentially serve many customers.

    Digital courses, intellectual property, media, automated systems and certain business models may offer similar scalability.

    Scalability is one reason entrepreneurship can create significant wealth—but it also involves considerable risk.

    15. They Develop Multiple Income Streams Carefully

    Depending exclusively on one income source can create vulnerability.

    Potential income sources include:

    Employment income
    Business income
    Freelance income
    Investment income
    Rental income
    Royalties
    Interest
    Dividends

    You do not need seven income streams immediately.

    Trying to build everything simultaneously can actually reduce progress.

    Establish one reliable income source and gradually diversify when appropriate.

    16. They Turn Income Into Assets

    This is one of the most important wealth-building habits.

    Consider two people who each receive an additional $10,000.

    One spends it entirely.

    The other uses some for enjoyment but directs the remainder toward investments, business equipment, education or another productive asset.

    The difference becomes larger when this behavior is repeated for decades.

    Wealth is not simply what flows into your hands.

    17. They Monitor Net Worth

    Income measures earnings.

    Net worth measures:

    Assets – Liabilities = Net Worth

    Tracking net worth can provide a clearer picture of long-term financial progress than salary alone.

    Review it periodically.

    Is debt falling?

    Are savings increasing?

    Are investments growing?

    Are productive assets accumulating?

    The direction matters.

    18. They Respect Cash Flow

    A business can appear successful yet fail because it cannot meet immediate obligations.

    A household can face the same problem.

    Wealthy financial management pays close attention to cash flow:

    Money coming in versus money going out.

    Knowing your cash flow helps you determine how much can realistically be saved, invested or reinvested.

    19. They Maintain Emergency Liquidity

    Investing every available dollar may sound aggressive, but emergencies require accessible money.

    A financial reserve can prevent someone from having to sell long-term investments at an unfavorable time or borrow at expensive interest rates.

    Wealth building requires both growth and resilience.

    20. They Take Calculated Risks

    Avoiding every risk can limit opportunity.

    Taking every risk can destroy wealth.

    The better approach is calculated risk.

    Before making a significant decision, consider:

    Potential upside
    Potential downside
    Probability of failure
    Maximum possible loss
    Time horizon
    Alternative options

    Successful wealth building is often about deciding which risks are worth taking.

    21. They Protect Against Catastrophic Losses

    Making money receives enormous attention.

    Protecting money deserves equal attention.

    Depending on circumstances, protection can involve emergency reserves, appropriate insurance, diversification, cybersecurity, legal structures and careful debt management.

    One catastrophic event can erase years of financial progress.

    Risk management is therefore part of wealth creation.

    22. They Avoid Concentrating Everything in One Place

    No investment is guaranteed.

    Putting nearly all your wealth into one company, asset, business, cryptocurrency or property can create enormous concentration risk.

    Diversification spreads exposure across different assets or investments.

    It cannot eliminate market losses, but it can help manage the consequences of one investment performing badly.

    23. They Protect Their Reputation

    Trust is an economic asset.

    Business owners need customers to trust them.

    Professionals need employers and colleagues to trust them.

    Investors need partners.

    A reputation for reliability, honesty and competence can produce opportunities for decades.

    Short-term dishonesty can destroy long-term economic value.

    24. They Understand Taxes and Financial Rules

    Ignoring taxes can become expensive.

    Financially sophisticated people understand the basic tax consequences of income, investments, businesses and major transactions.

    Tax systems vary dramatically around the world, so qualified local professional guidance can be important.

    The goal should be lawful tax planning—not illegal tax avoidance or concealment.

    25. They Make Decisions Based on Value, Not Only Price

    Cheap does not always mean economical.

    An inexpensive tool that constantly breaks may cost more than a durable one.

    Likewise, the most expensive option isn’t automatically superior.

    A wealth-building mindset considers:

    Price + Quality + Durability + Productivity + Opportunity Cost

    The objective is maximizing value.

    26. They Understand Opportunity Cost

    Every financial decision eliminates another possibility.

    Spending $20,000 on a luxury purchase means that same $20,000 cannot simultaneously finance education, an investment or a business.

    This doesn’t automatically make the purchase wrong.

    It simply means every significant purchase should be evaluated against what else the money could accomplish.

    27. They Protect Their Time

    Money can be earned again.

    Time cannot.

    Financially successful people often become increasingly selective about where their time goes.

    They automate repetitive work, delegate when economically sensible and prioritize high-value activities.

    Ask yourself:

    Which activities create the greatest improvement in my income, skills or future opportunities?

    Give those activities priority.

    28. They Use Money to Buy Options

    One of wealth’s greatest benefits is freedom of choice.

    Financial reserves can allow someone to:

    Leave an unsuitable job.

    Move to another location.

    Start a business.

    Return to school.

    Care for family.

    Take a career risk.

    Retire.

    The objective of wealth does not have to be luxury.

    It can be control over your time and decisions.

    29. They Define Financial Independence

    Financial independence means different things to different people.

    For one person it may mean becoming debt-free.

    For another, owning a home without a mortgage.

    Another may want enough investments to cover living expenses without employment.

    Define your own target.

    Without a definition, “more money” can become an endless pursuit.

    30. They Don’t Expect Overnight Wealth

    Social media frequently compresses a ten-year journey into a 30-second success story.

    Real wealth often takes much longer.

    Careers take years to develop.

    Businesses take time to mature.

    Investments need time to compound.

    Patience is not inactivity.

    It is continuing the right behaviors long enough for them to produce meaningful results.

    31. They Learn From Financial Mistakes

    Successful entrepreneurs and investors make mistakes.

    Businesses fail.

    Investments lose money.

    Products flop.

    Hiring decisions go wrong.

    The important question is:

    What did this mistake teach me?

    A mistake becomes especially expensive when nothing is learned from it.

    32. They Preserve Wealth After Creating It

    Making money and keeping money require different skills.

    Once meaningful wealth has been accumulated, priorities may gradually shift from aggressive growth toward a combination of growth, income, diversification, liquidity and capital preservation.

    Someone approaching retirement, for example, may have different risk needs from someone beginning a career.

    Wealth strategy should evolve with circumstances.

    33. They Think About Legacy

    Wealth can outlive its creator.

    Legacy planning may involve family, charitable giving, education, businesses, property, investments or community impact.

    Financial legacy also includes knowledge.

    Teaching children how to budget, save, invest and manage risk may be as important as transferring assets.

    34. They Create Systems That Can Continue Without Them

    Successful entrepreneurs eventually ask:

    Can this organization function without my constant presence?

    Documented processes, trained employees, technology, delegation and management systems can transform self-employment into a more durable enterprise.

    A business completely dependent on its founder may have limited transferable value.

    35. They Think in Generations

    Long-term wealth planning can extend beyond retirement.

    How can assets benefit children or future generations?

    How can a business continue?

    How should property be transferred?

    How can heirs be financially educated?

    Building wealth without preparing future generations to manage it can undermine the legacy.

    Lessons From Successful Entrepreneurs

    There is no single formula behind successful entrepreneurs, but several recurring principles deserve attention.

    Warren Buffett is strongly associated with long-term investing, patience and focusing on businesses rather than short-term market excitement.

    Sara Blakely built her company from a product idea aimed at solving a specific consumer problem, illustrating the entrepreneurial importance of identifying unmet needs and persistently developing solutions.

    Oprah Winfrey transformed expertise and audience trust into a much broader media and business platform, demonstrating the potential economic value of reputation, communication skills and intellectual property.

    Their circumstances and paths were very different. The lesson is not to imitate their exact investments or businesses. It is to study broader principles: create value, think long term, learn continuously, protect your reputation and reinvest intelligently.

    Case Study 1: The High-Income Spender

    Imagine James earns $120,000 annually but increases his lifestyle every time his salary rises.

    After many years, his income looks impressive but his net worth remains relatively modest.

    He changes one behavior: every future salary increase is divided between lifestyle improvement and asset accumulation.

    His income hasn’t suddenly transformed.

    His relationship between income and ownership has.

    Case Study 2: The Consistent Investor

    Maria earns considerably less than James but begins regularly investing a manageable percentage of her income for long-term goals.

    As her salary rises, she gradually increases her contributions.

    She avoids chasing every market trend and maintains emergency savings separately.

    Her advantage is not secret investment knowledge.

    It is consistency + diversification + patience + time.

    Case Study 3: The Entrepreneur Who Starts Small

    Daniel wants to start a food business.

    Instead of immediately borrowing heavily for a restaurant, he tests demand by selling a limited menu through pre-orders.

    Customers respond positively.

    He reinvests profits into equipment, improves packaging, builds repeat customers and expands gradually.

    His wealth-building lesson is:

    Test → Learn → Generate revenue → Reinvest → Scale.

    Starting small allowed him to gather evidence before taking larger risks.

    The Wealth-Building Cycle

    The psychology of wealth can be summarized through a repeating cycle:

    Learn → Increase Your Value → Earn → Control Spending → Save → Acquire Productive Assets → Invest → Protect → Reinvest → Repeat

    The cycle can operate at almost any income level, although the speed will differ dramatically according to earnings and circumstances.

    Someone earning a low income may need to concentrate first on skills and increasing earnings.

    Someone with strong income but no savings may need to control lifestyle inflation.

    Someone with substantial assets may need to focus more heavily on diversification and wealth preservation.

    The correct strategy depends on where you are today.

    How to Start Thinking Differently About Money Today

    You don’t need to become a millionaire before adopting stronger financial habits.

    Begin by asking yourself five questions:

    1. What percentage of my income am I keeping?

    2. Which valuable skill could increase my earning power?

    3. What productive assets am I accumulating?

    4. What financial risks could seriously damage my progress?

    5. Where could consistent action put me in 10 years?

    Write down the answers.

    Then identify one change you can begin this month.

    Perhaps you automate savings.

    Maybe you begin professional training.

    Perhaps you finally calculate your net worth.

    Maybe you reduce expensive debt.

    Or perhaps you begin researching long-term investments appropriate to your circumstances.

    The action does not need to be dramatic.

    It needs to move you in the right direction.

    Conclusion

    Wealth Is Built Through Behavior, Assets and Time

    The psychology of wealth is not about pretending that positive thinking alone creates money.

    It doesn’t.

    Wealth creation is influenced by income, education, opportunity, geography, economic conditions, family circumstances, access to capital, government policy and sometimes luck.

    But behavior still matters enormously.

    People who build sustainable wealth often learn to think beyond immediate consumption. They continually improve their earning ability, acquire productive assets, invest for long-term goals, manage risk, develop strong networks, learn from mistakes and resist unnecessary lifestyle inflation.

    Most importantly, they understand the difference between earning money and owning wealth.

    Your goal does not have to be becoming a millionaire.

    Your goal can be something more meaningful:

    Greater security.
    Greater independence.
    Greater control over your time.
    More opportunities for your family.
    And the ability to make decisions based on what you value rather than what you can afford this week.

    Start where you are.

    Learn continuously. Increase your value. Control what you spend. Build assets. Manage risk. Think long term.

    Because sustainable wealth is rarely created by one extraordinary financial decision.

    It is usually built through ordinary intelligent decisions repeated for an extraordinary amount of time.

    Educational Disclaimer: This article provides general financial education and does not constitute individualized investment, financial, tax or legal advice. Investing involves risk, including possible loss of principal. Investment products, taxes, regulations and consumer protections vary by country.

  • How to Become Financially Independent Before Age 40

    How to Become Financially Independent Before Age 40

    A Practical Roadmap to Saving, Investing, Multiple Income Streams and Long-Term Financial Freedom

    Introduction

    Financial Independence Is About Freedom, Not Just Becoming Rich

    Imagine reaching your late 30s and knowing that losing your job would not immediately threaten your home, food, healthcare or basic lifestyle. Imagine having enough savings, investments, business income or other assets that employment becomes a choice rather than your only means of financial survival.

    That is the basic idea behind financial independence.

    Becoming financially independent before age 40 is an ambitious goal, and it will not be realistic for everyone. Income levels, family responsibilities, housing costs, healthcare systems, taxes, economic conditions and access to investment opportunities differ dramatically around the world.

    However, the principles behind financial independence can benefit almost anyone—even if reaching complete independence happens at 45, 55 or later.

    The journey generally requires several things working together:

    Increasing income.
    Controlling expenses.
    Saving consistently.
    Investing for long-term growth.
    Building assets.
    Avoiding destructive debt.
    Creating additional income sources.
    Giving compound growth enough time to work.

    Financial independence rarely comes from one brilliant investment. It is usually the result of hundreds of sensible financial decisions repeated for many years

    What Does Financial Independence Mean?

    Financial independence generally means reaching a position where your accumulated financial resources and sustainable income sources can support your living expenses without depending entirely on employment.

    It does not necessarily mean never working again.

    Many financially independent people continue working because they enjoy their careers, run businesses, pursue creative projects or want to continue accumulating wealth.

    The difference is choice.

    A financially independent person may have income from investments, businesses, property or other assets that reduces dependence on a monthly salary.

    A useful starting point is calculating your current financial position:

    Net Worth = Total Assets − Total Liabilities

    Assets may include cash, investments, retirement accounts, business interests and property equity. Liabilities can include credit-card debt, personal loans, student loans, mortgages and other financial obligations.

    The Consumer Financial Protection Bureau provides educational resources for building savings, while Investor.gov provides beginner-friendly information about investing and financial markets.

    Understanding the FIRE Movement

    FIRE stands for Financial Independence, Retire Early.

    The movement became popular among people who wanted an alternative to the traditional pattern of working until their 60s before gaining significant control over their time.

    FIRE followers often focus on three major principles:

    Earn more.
    Spend intentionally.
    Invest the difference.

    Some pursue very high savings rates and deliberately maintain modest lifestyles so they can invest a substantial percentage of their income.

    However, FIRE does not have to mean extreme deprivation.

    Different approaches include:

    Lean FIRE — achieving independence with relatively low annual expenses.

    Fat FIRE — accumulating enough wealth to maintain a more expensive lifestyle.

    Coast FIRE — accumulating enough investments relatively early so that, assuming sufficient future growth, additional retirement contributions may eventually become less important.

    Barista FIRE — accumulating substantial assets but continuing some employment or business activity to cover part of current expenses.

    Whichever version appeals to you, remember that future investment returns are uncertain. The Investor.gov retirement resources can help explain retirement planning, while the FINRA retirement resources provide additional education about long-term investing and retirement.

    Increase Your Income Before Trying to Cut Everything

    Reducing unnecessary expenses is useful, but there is a limit to how much you can cut.

    Income has much greater upside.

    Suppose someone earns $2,000 per month and already spends $1,700 on essential living costs. Extreme budgeting has limited potential.

    Increasing income to $3,000 or $4,000 could transform that person’s ability to save and invest.

    Ways to increase earning potential may include:

    • Professional certifications
    • Technical skills
    • Skilled trades
    • Sales
    • Healthcare careers
    • Technology
    • Management
    • Freelancing
    • Digital marketing
    • Entrepreneurship
    • Online services
    • Consulting

    Ask yourself:

    What skill could increase my income significantly over the next three years?

    Investing in your earning ability can sometimes produce a greater initial financial impact than obsessing over tiny spending reductions.

    Diversify Your Income Sources

    Depending entirely on one employer creates concentration risk.

    If that job disappears, your entire primary income may disappear with it.

    Income diversification means gradually developing additional ways of earning money.

    Potential income streams include:

    Employment income
    Freelance income
    Business profits
    Investment income
    Rental income
    Interest
    Dividends
    Royalties
    Digital products

    You do not need to create seven income streams immediately.

    That can actually become counterproductive.

    Start by strengthening your primary income. Then develop one additional source that fits your abilities, available time, capital and market opportunities.

    Eventually, multiple income streams can provide greater financial resilience and accelerate wealth accumulation.

    Save Aggressively—but Sustainably

    Your savings rate is one of the most important variables in the financial-independence journey.

    If someone earns $50,000 and saves $2,500 annually, the savings rate is approximately 5%.

    If that person saves $15,000, it is approximately 30%.

    Higher savings rates can dramatically accelerate asset accumulation, although taxes and definitions of income need to be considered when making precise calculations.

    Aggressive saving does not mean ignoring health, nutrition, family responsibilities or basic quality of life.

    Instead, focus first on major recurring expenses:

    Housing
    Transportation
    Food
    Debt
    Insurance
    Subscriptions
    Utilities

    Saving $300 every month on a major recurring expense is generally more powerful than occasionally saving $3 on coffee.

    The CFPB savings resources provide practical saving guidance, while the FDIC’s Money Smart program provides broader financial education.

    Build an Emergency Fund Before Aggressive Investing

    Financial independence requires resilience as well as growth.

    Before putting all available money into long-term investments, establish accessible emergency savings.

    An emergency fund can help cover unexpected expenses such as job loss, medical costs, urgent repairs or temporary income disruption.

    Without one, you may be forced to borrow or sell investments during unfavorable market conditions.

    The CFPB emergency-fund guide explains how dedicated emergency savings can protect against financial shocks, while FINRA provides educational resources for people preparing to invest.

    Invest Wisely for Long-Term Growth

    Saving builds capital.

    Investing gives that capital an opportunity to grow.

    Long-term investments can include diversified stock and bond funds and other regulated investment products appropriate to your country, circumstances, objectives and risk tolerance.

    The objective is not to chase whatever asset has recently produced spectacular returns.

    Ask:

    What am I investing in?
    How does it generate value?
    What are the fees?
    What risks am I taking?
    How diversified am I?
    When will I need this money?

    Diversification can help manage investment risk, although it cannot guarantee profits or eliminate losses. Investor.gov explains diversification, while FINRA’s investing resources provide additional education on investing and risk.

    Understand the Power of Compound Growth

    Compound growth means your investment returns can potentially generate additional returns.

    Imagine investing $500 every month for 20 years.

    Your personal contributions would total:

    $500 × 12 × 20 = $120,000

    If those investments earned a hypothetical average return over time, the eventual value could be significantly higher because returns may compound.

    The example is illustrative rather than a promise of future performance.

    The key lesson is:

    Money + Return + Time = Potential Compound Growth

    Starting earlier gives compounding more time to operate.

    Investor.gov provides a useful compound interest calculator for experimenting with different contribution amounts, time periods and hypothetical returns.

    Create Passive and Semi-Passive Income Carefully

    “Passive income” is one of the most overused phrases online.

    Most income streams require something first:

    Money, time, expertise, systems—or all four.

    Potential sources can include dividends, interest, rental property, royalties, licensing, digital products and businesses that eventually operate with limited owner involvement.

    But none should automatically be assumed to be effortless.

    Rental property requires maintenance and management.

    Dividend-paying companies can reduce dividends.

    Businesses can fail.

    Digital products require development and marketing.

    Instead of asking:

    “How can I make money without working?”

    Ask:

    “What asset or system can I build today that may continue generating value later?”

    That is a much stronger approach to passive income.

    Use Digital Business to Expand Your Opportunities

    The internet has reduced some barriers to entrepreneurship.

    A person can potentially serve customers beyond their immediate town or country through:

    • Freelance services
    • Online education
    • Digital publishing
    • Software
    • Content businesses
    • E-commerce
    • Consulting
    • Affiliate marketing
    • Graphic design
    • Marketing services
    • Subscription businesses

    Digital business is not automatic income.

    Competition is intense, and success generally requires useful skills, customer demand, marketing, persistence and continuous improvement.

    But digital distribution can give entrepreneurs access to markets that were previously impossible to reach without substantial capital.

    Entrepreneurship Can Accelerate Financial Independence

    Employment usually provides more predictable income.

    Entrepreneurship can provide greater upside—but greater risk.

    A successful business may create income and an asset that has value beyond the founder’s salary.

    However, businesses can also lose money.

    A safer approach for many beginners is:

    Identify a problem → Test demand → Start small → Generate sales → Improve → Reinvest → Scale

    Avoid borrowing enormous amounts of money simply because you have an exciting idea.

    Customers—not enthusiasm alone—validate a business.

    Build evidence before increasing risk.

    Avoid Lifestyle Inflation

    Lifestyle inflation happens when expenses automatically rise alongside income.

    You earn $3,000 monthly and spend $2,900.

    Your income increases to $4,000—and eventually you spend $3,900.

    Then you earn $5,000 and spend $4,900.

    Your salary grows, but your wealth barely changes.

    One powerful strategy is to establish a raise allocation rule.

    For example:

    Whenever income increases, automatically direct part of the increase toward investments or other financial goals before increasing lifestyle spending.

    You can still improve your standard of living.

    The objective is simply to make sure your assets rise when your income rises.

    Eliminate Expensive Consumer Debt

    High-interest debt can work against financial independence.

    If an investment hypothetically earns 7% while a credit-card balance costs substantially more in interest, the expensive debt can overwhelm investment progress.

    Prioritize high-cost consumer debt while continuing to maintain appropriate emergency reserves and considering any important employer benefits available to you.

    Once expensive debt disappears, redirect the former monthly payment toward savings and investments.

    Do not simply absorb it into lifestyle spending.

    Plan for Retirement Even If You Want to Retire Early

    Early financial independence requires more retirement planning—not less.

    Someone planning to stop traditional employment at 40 may need assets to support decades of future expenses.

    Consider:

    Housing
    Food
    Healthcare
    Taxes
    Insurance
    Inflation
    Family responsibilities
    Investment volatility
    Longevity
    Unexpected expenses

    Retirement rules, pensions and tax-advantaged accounts vary by country. U.S. readers can explore Investor.gov’s retirement toolkit, while readers elsewhere should consult their country’s official pension, tax and financial regulators.

    Do not assume today’s expenses will remain unchanged for 40 years.

    Calculate Your Financial Independence Number Carefully

    A popular FIRE concept is estimating how large a portfolio might be needed to support annual spending.

    You may encounter simplified rules such as multiplying annual expenses by 25, which corresponds to an initial 4% withdrawal assumption.

    For example:

    $40,000 annual expenses × 25 = $1,000,000

    But this should not be treated as a guarantee.

    Taxes, inflation, investment returns, retirement duration, healthcare expenses, portfolio allocation and future spending can materially change outcomes.

    Someone retiring at 40 potentially faces a much longer retirement horizon than someone retiring at 65.

    Use withdrawal rules as planning tools—not promises.

    Build Assets, Not Just a Bigger Salary

    But financial independence ultimately depends more on what you own relative to what you need to spend.

    Assets may include:

    Investments
    Business ownership
    Property equity
    Cash reserves
    Retirement assets
    Intellectual property

    Someone earning $150,000 while spending $145,000 may be less financially resilient than someone earning $80,000, living on $45,000 and consistently acquiring productive assets.

    Income provides the fuel.

    Asset ownership helps build independence.

    Protect the Wealth You Are Building

    Building financial independence without risk management can leave years of progress vulnerable.

    Depending on your circumstances, protection may include:

    Emergency savings
    Appropriate insurance
    Diversification
    Secure passwords and cybersecurity
    Estate planning
    Responsible debt management
    Tax planning

    Avoid putting your entire financial future into one stock, cryptocurrency, property, employer or business.

    Building wealth and protecting wealth should happen together.

    A Financial Freedom Roadmap: From Starting Point to Independence

    Stage 1: Stabilize Your Finances

    Track income and expenses.

    Create a basic budget.

    Stop accumulating unnecessary high-interest debt.

    Build your first emergency reserve.

    Stage 2: Increase Your Financial Capacity

    Improve valuable skills.

    Negotiate compensation where appropriate.

    Pursue career advancement.

    Build an additional income source.

    Stage 3: Increase Your Savings Rate

    Automate savings.

    Control major recurring expenses.

    Avoid unnecessary lifestyle inflation.

    Save part of every income increase.

    Stage 4: Begin Long-Term Investing

    Understand risk.

    Choose regulated investments appropriate to your circumstances.

    Diversify.

    Keep fees in mind.

    Invest consistently rather than emotionally chasing markets.

    Stage 5: Build Additional Assets and Income

    Develop a business if appropriate.

    Build digital assets.

    Acquire productive investments.

    Reinvest part of additional income.

    Stage 6: Protect Your Progress

    Maintain emergency reserves.

    Review insurance.

    Diversify assets.

    Avoid catastrophic financial risks.

    Stage 7: Calculate Your Independence Target

    Estimate future annual expenses.

    Consider taxes and inflation.

    Estimate healthcare and family obligations.

    Review potential retirement income.

    Model several investment-return scenarios rather than assuming one outcome.

    Stage 8: Review Your Progress Every Year

    Calculate:

    Net worth
    Savings rate
    Investment contributions
    Debt
    Annual expenses
    Additional income
    Progress toward your financial-independence target

    Then adjust the strategy.

    A Hypothetical Journey to Financial Independence Before 40

    Consider Maya, age 25.

    She has a full-time job but little invested.

    Instead of expecting instant wealth, she develops a 15-year strategy.

    From 25–28, she focuses on eliminating expensive debt, building emergency savings and developing a higher-income professional skill.

    From 28–32, her income increases. Instead of upgrading every aspect of her lifestyle, she invests a meaningful portion of the additional income.

    From 32–35, she develops a small digital business alongside employment and invests part of the profits.

    From 35–38, she continues accumulating diversified assets while keeping living expenses manageable.

    By 38–40, her investments and additional income sources have grown substantially.

    Whether she reaches complete financial independence depends on her income, savings rate, investment performance, expenses and circumstances.

    But even if she reaches only 60% or 70% of her original target, she may still be dramatically more financially secure than when she started.

    That is an important lesson:

    Financial independence is not all-or-nothing.

    Every step toward it increases your financial options.

    The Financial Independence Formula

    The entire strategy can be summarized as:

    Learn → Earn More → Spend Intentionally → Save → Invest → Build Assets → Diversify Income → Protect Wealth → Reinvest → Repeat

    Do this for long enough, and the relationship between your work and your money can begin to change.

    At first:

    You work for money.

    Eventually:

    Your accumulated assets can begin working alongside you.

    The ultimate objective is reaching the point where those assets can support a meaningful portion—or eventually all—of your financial needs.

    Conclusion

    Financial Independence Before 40 Requires a Plan, Not a Miracle

    Becoming financially independent before age 40 is ambitious.

    It usually requires much more than finding the perfect investment.

    You need to understand your expenses, increase your earning power, maintain a strong savings rate, control lifestyle inflation, avoid destructive debt, build emergency reserves and invest consistently.

    You may also accelerate progress through entrepreneurship, digital business and carefully developed additional income streams.

    Most importantly, give yourself time.

    Compound growth needs time.

    Businesses need time.

    Careers need time.

    Skills need time.

    Financial independence is built by repeatedly converting income into assets and assets into greater financial freedom.

    If you are 20, start now.

    If you are 30, start now.

    If you are already over 40, the principles remain valuable. The objective is not to compete with someone else’s age or net worth.

    The objective is to make your future financially stronger than your present.

    Earn intentionally. Save aggressively but sustainably. Invest intelligently. Build assets. Protect what you create. And keep moving toward the point where money gives you more control over your life rather than less.

    Educational Disclaimer: This article is for general educational purposes and does not constitute individualized financial, investment, tax, retirement or legal advice. Investments involve risk, including possible loss of principal. Financial products, retirement systems, taxes and regulations vary by country.
  • The Psychology of Money: 40 Lessons That Can Change Your Financial Life Forever

    The Psychology of Money: 40 Lessons That Can Change Your Financial Life Forever

    Understand Your Money Mindset, Control Emotional Spending, Build Better Financial Habits and Make Smarter Decisions About Saving, Spending and Investing

    Introduction

    Your Financial Life Begins in Your Mind. Why can two people earning similar incomes have completely different financial lives? Why does one person consistently save while another repeatedly spends everything? Why do intelligent investors sometimes panic when markets fall, while others become dangerously confident when prices rise?

    The answers often involve more than mathematics. Money is psychological.

    Our financial decisions can be influenced by emotions, childhood experiences, family expectations, social pressure, fear, greed, confidence, habits and beliefs about what money represents. Behavioral finance examines how psychological influences can affect financial decisions, including decisions that do not always follow purely rational economic assumptions.

    Understanding your own behavior therefore can be just as important as understanding interest rates, budgets or investments.

    These 40 lessons explore the psychology behind spending, saving, investing and wealth building—and provide practical ways to develop a healthier relationship with money.

    1. Money Is Emotional

    Money is rarely just numbers in a bank account.

    It can represent security, freedom, success, independence, power, status or even fear. That emotional connection can influence financial decisions without us realizing it.

    Before making an important financial decision, ask yourself:

    Am I making this decision based on facts—or feelings?

    Recognizing the emotion is the first step toward controlling its influence.

    2. Understand Emotional Spending

    Some people shop when they feel stressed, lonely, bored, frustrated or even excited.

    The purchase provides temporary satisfaction, but the underlying emotion remains.

    Before making an unplanned purchase, identify what triggered the desire. If the purchase is emotional rather than necessary, wait 24 hours.

    That short delay can separate the emotion from the financial decision.

    3. Examine Your Money Beliefs

    Everyone develops beliefs about money.

    You may believe:

    “Money is difficult to earn.”
    “Rich people are greedy.”
    “I will always struggle financially.”
    “Having more money will solve everything.”

    Some beliefs may motivate you. Others may limit you.

    Ask yourself where each belief originated and whether evidence actually supports it.

    4. Understand Your Childhood Money Influences

    Your earliest financial education probably occurred before you understood what finance meant.

    Perhaps your parents constantly worried about bills. Maybe money was never discussed. Perhaps spending demonstrated success, or extreme saving was considered virtuous.

    These experiences can influence adult behavior.

    You don’t have to blame your childhood. Instead, identify which lessons are worth keeping and which should be reconsidered.

    5. Separate Your Identity From Your Income

    Your salary is not your personal worth.

    Someone earning more money is not automatically more intelligent, responsible or valuable.

    Connecting self-worth to income can encourage status spending and unhealthy comparisons.

    Treat income as a financial resource—not a measurement of human value.

    6. Recognize the Scarcity Mindset

    When money is genuinely scarce, focusing intensely on immediate needs can be necessary.

    But scarcity can also narrow attention so much that long-term planning becomes difficult.

    If every decision is focused exclusively on surviving today, saving, training and future planning may receive little attention.

    Begin with small steps. Even planning one week ahead can be progress when circumstances are difficult.

    7. Develop an Opportunity-Oriented Mindset

    An abundance mindset does not mean pretending unlimited money exists.

    A healthier interpretation is believing that skills can improve, opportunities can be pursued, knowledge can increase and financial circumstances can potentially change.

    Instead of asking only:

    “What can I cut?”

    also ask:

    “How can I increase my value and income?”

    Financial progress often requires both.

    8. Understand Fear

    Fear can protect your money—but it can also paralyze you.

    Fear might prevent someone from investing anything, negotiating salary, changing careers or starting a carefully researched business.

    Ask:

    What exactly am I afraid will happen? What evidence supports that fear? How could I reduce the risk?

    Turning vague fear into measurable risk makes better decisions possible.

    9. Understand Greed

    Greed can push people toward investments they barely understand because someone promises extraordinary returns.

    The higher the promised reward, the more carefully you should investigate the risk.

    Never allow the desire to become wealthy quickly to override basic due diligence.

    10. Practice Delayed Gratification

    Delayed gratification means accepting a smaller reward today in pursuit of a potentially greater future benefit.

    Instead of immediately spending a bonus, you might save part of it.

    Instead of financing an unnecessary luxury purchase, you might wait until you can comfortably afford it.

    This habit sits at the heart of long-term wealth building.

    11. Learn to Wait Before Buying

    Create a waiting rule:

    24 hours for small discretionary purchases.
    Several days for expensive purchases.

    Waiting gives excitement time to decline.

    You may discover that something you desperately wanted yesterday feels unnecessary tomorrow.

    12. Stop Using Money to Impress People

    Status spending can become extremely expensive.

    Luxury vehicles, clothing, electronics and other possessions may communicate wealth without actually creating it.

    Someone can look wealthy while carrying substantial debt.

    Financial security is often largely invisible: savings, investments, manageable debt and adequate financial reserves rarely attract attention.

    13. Understand Lifestyle Inflation

    When income increases, spending often increases with it.

    You get a raise and immediately upgrade the vehicle, apartment, phone, wardrobe or vacations.

    Enjoying higher income is not inherently wrong.

    The danger appears when every income increase becomes a permanent expense increase.

    Automatically save or invest part of future raises before adjusting your lifestyle.

    14. Make Saving Automatic

    Saving requires less willpower when it happens automatically.

    Where available, schedule automatic transfers shortly after receiving income.

    Psychologically, money that immediately moves into savings is less likely to feel available for everyday spending.

    The goal is to make good behavior easier.

    15. Give Savings an Emotional Purpose

    “Save $5,000” may not feel motivating.

    “Build six months of security for my family” creates meaning.

    Attach savings goals to outcomes:

    Emergency security
    Education
    Homeownership
    Business capital
    Travel
    Retirement
    Financial independence

    Purpose strengthens motivation.

    16. Celebrate Saving Milestones

    arge goals can feel distant.

    Break them into smaller victories.

    If your goal is $10,000, celebrate psychologically—not necessarily by spending heavily—when you reach $1,000, $2,500, $5,000 and $7,500.

    Visible progress encourages consistency.

    17. Understand Why Habits Beat Motivation

    Motivation changes from day to day.

    Habits continue even when motivation disappears.

    Build routines around payday, budgeting, saving and investing.

    For example:

    Payday → Save automatically → Pay bills → Spend remaining budget

    Repeated systems reduce dependence on willpower.

    18. Control Your Financial Environment

    Your environment influences behavior.

    Shopping notifications, promotional emails, one-click purchasing and social-media advertising constantly encourage consumption.

    Unsubscribe from unnecessary marketing. Remove stored payment information if impulse buying is a problem. Avoid browsing online stores for entertainment.

    Sometimes the easiest way to improve discipline is to remove temptation.

    19. Understand Consumer Psychology

    Businesses study consumer behavior carefully.

    Scarcity messages such as “Only two remaining!”, countdown timers, discounts and limited-time promotions can create urgency.

    A discount is not automatically a saving.

    If you spend $70 on something you didn’t need because it was reduced from $100, you did not necessarily “save $30.” You still spent $70.

    20. Stop Comparing Your Finances With Social Media

    Social media shows outcomes without necessarily showing financial reality.

    You may see someone’s vacation without seeing the credit-card balance. You see the vehicle without knowing the monthly payment.

    Comparison can create pressure to spend money proving that you are equally successful.

    Measure your progress against your own goals instead.

    21. Understand Present Bias

    Humans often give disproportionate importance to immediate rewards.

    Spending $100 today feels real. Having $100 plus potential growth decades later feels distant.

    This helps explain why retirement saving can be psychologically difficult.

    Bring the future closer by visualizing what today’s financial decision means for your future lifestyle.

    22. Meet Your Future Self

    Imagine yourself 10, 20 or 30 years from now.

    Where will you live?

    Will you still need to work?

    What financial obligations might you have?

    Now ask:

    What would that future version of me wish I had started doing today?

    This can transform saving from sacrifice into self-care for your future.

    23. Understand Loss Aversion

    People often experience the pain of losses strongly, sometimes more intensely than equivalent gains feel rewarding.

    This can affect investment decisions.

    An investor may sell during a market decline simply to stop the emotional discomfort—or hold a losing investment irrationally because selling would make the loss feel “real.”

    Investment decisions should be based on goals, risk tolerance, diversification and evidence rather than panic.

    24. Beware of Herd Behavior

    When everyone seems to be buying an investment, fear of missing out can become powerful.

    But popularity does not prove value.

    Before investing, ask:

    Would I still buy this if nobody on social media were talking about it?

    If the answer is no, investigate further.

    25. Watch for Overconfidence

    Success can create dangerous confidence.

    After several profitable investments, someone may conclude that they possess exceptional forecasting ability.

    That can lead to larger bets and excessive risk.

    A favorable outcome does not always mean the original decision was wise. Sometimes luck contributes.

    26. Recognize Confirmation Bias

    People naturally seek information supporting what they already believe.

    If you love a particular investment, you may focus on positive articles while dismissing warnings.

    Challenge yourself deliberately:

    What evidence would prove my assumption wrong?

    Good decision-making requires examining opposing evidence.

    27. Know Your Risk Tolerance

    Investment risk is partly financial and partly psychological.

    An investment may appear appropriate mathematically but still be unsuitable if normal price fluctuations cause you to panic.

    Understand both your ability and willingness to tolerate losses.

    Your investment strategy should reflect your goals, time horizon, circumstances and capacity for risk.

    28. Don’t Make Major Money Decisions During Extreme Emotions

    Avoid important financial decisions when you are panicked, furious, euphoric or desperate whenever circumstances allow.

    Strong emotions can narrow judgment.

    Write down the decision, gather information, consider alternatives and revisit it when your emotional state is calmer.

    29. Build Financial Confidence Through Small Wins

    Financial confidence develops through action.

    Create a $100 emergency fund.

    Pay off one small debt.

    Follow your budget for one month.

    Complete a financial course.

    Negotiate one bill.

    Small achievements provide evidence that you can manage money effectively.

    30. Accept That Wealth Building Is Usually Boring

    Sustainable financial progress often lacks excitement.

    Budget.

    Save.

    Increase income.

    Avoid unnecessary debt.

    Invest appropriately.

    Repeat for years.

    The search for constant financial excitement can lead people toward excessive trading, speculation and scams.

    Boring consistency can be powerful.

    31. Build Patience

    Compounding requires time.

    Skills require time.

    Businesses require time.

    Careers require time.

    Wealth generally requires time.

    Do not compare your first year with someone else’s twentieth year.

    Judge whether your direction is improving.

    32. Avoid Financial Perfectionism

    You will make money mistakes.

    You may overspend one month, choose a poor investment, miss a savings target or regret a purchase.

    Do not respond by abandoning your entire financial plan.

    Ask what happened, correct the behavior and continue.

    Progress matters more than perfection.

    33. Create Rules Before Temptation Arrives

    Financial rules simplify decision-making.

    Examples include:

    I save 10% of every payment.
    I wait 48 hours before purchases above $200.
    I never borrow for vacations.
    I research investments before committing money.
    I increase retirement contributions whenever my income rises.

    Decisions made calmly can protect you when emotions become stronger.

    34. Separate Emergency Money From Spending Money

    Keeping all money together can create the illusion that you have more available to spend.

    Where practical, separate emergency savings from everyday transaction accounts.

    Creating physical or psychological boundaries around savings reduces temptation.

    35. Define What “Enough” Means

    Without a definition of enough, financial goals can become endless.

    More income. A bigger house. A newer vehicle. A larger investment portfolio.

    There will almost always be someone with more.

    Determine what financial success means to you.

    Security? Freedom? Family stability? Early retirement? Entrepreneurship? Generational wealth?

    Your definition determines your strategy.

    36. Use Money to Buy Freedom, Not Only Things

    One of money’s greatest benefits is optionality.

    Savings may allow you to leave an unhealthy job, survive unemployment, pursue education, care for family, relocate, start a business or retire with dignity.

    Think of savings not merely as numbers.

    Think of them as future choices.

    37. Reduce Financial Stress With Systems

    Money stress often increases when finances feel uncertain.

    Create systems:

    Know your bills.
    Track your debts.
    Automate essential payments where appropriate.
    Build emergency savings.
    Maintain a budget.
    Review accounts regularly.

    A system cannot eliminate every financial problem, but greater visibility can reduce uncertainty.

    38. Hold a Weekly Money Meeting With Yourself

    Choose 15–20 minutes once each week.

    Review:

    Account balances
    Recent spending
    Upcoming bills
    Savings progress
    Debt balances
    Financial goals

    For couples or families managing money together, a regular household financial meeting can improve communication and shared accountability.

    39. Learn From Your Financial Decisions

    At the end of each month, identify:

    One financial decision that worked.
    One mistake you made.
    One expense you could reduce.
    One behavior you want to repeat.
    One improvement for next month.

    Financial intelligence develops through reflection as well as education.

    40. Build a Financial Identity

    Instead of repeatedly telling yourself:

    “I am terrible with money,”

    build a new identity through repeated actions:

    “I am someone who plans before spending.”
    “I save part of what I earn.”
    “I research before investing.”
    “I don’t need to impress people with purchases.”
    “I make decisions for both my present and future.”

    Identity reinforces behavior, and behavior eventually produces financial results.

    Practical Example: The Emotional Spender

    Imagine Sarah frequently shops online after stressful workdays.

    She initially thinks her problem is simply poor budgeting.

    After tracking her behavior, however, she discovers that most unnecessary purchases occur late at night following stressful days.

    She creates a new rule: items go into the shopping cart, but she cannot purchase them for 48 hours.

    Many never get purchased.

    Her financial improvement came not from earning more but from understanding the psychological trigger behind her spending.

    Practical Example: The Fearful Saver

    David saves consistently but refuses to learn about investing because he fears losing any money.

    His caution protects him from reckless speculation, but fear may also prevent him from considering suitable long-term options.

    Rather than jumping into an investment he doesn’t understand, David learns about diversification, risk, fees and long-term investing.

    Knowledge allows him to distinguish calculated risk from blind risk.

    Practical Example: The Lifestyle Trap

    Michael receives a significant salary increase.

    Within months he leases a more expensive vehicle, moves into a larger apartment and increases restaurant spending.

    His salary is higher, but his savings rate barely changes.

    When he receives his next raise, he changes strategy: half of the increase is automatically directed toward long-term financial goals before his lifestyle expands.

    Higher income finally begins producing higher wealth.

    Daily Exercises to Improve Your Money Psychology

    Understanding financial psychology becomes valuable when knowledge changes behavior. Try these exercises regularly:

    Morning: Identify one financial priority for the day.

    Before purchasing: Ask, “Do I need this, value this, or am I reacting emotionally?”

    After spending: Record the purchase and briefly identify why you made it.

    Daily: Avoid at least one unnecessary purchase and record the amount.

    Weekly: Review spending and identify emotional triggers.

    Monthly: Calculate savings, debt reduction and progress toward your goals.

    Quarterly: Review your income, investments, financial goals and risk tolerance.

    Annually: Compare your financial position with the previous year—not with another person’s lifestyle.

    A Simple Money Psychology Checklist

    Before making a significant financial decision, ask yourself:

    What am I feeling right now?
    What is motivating this decision?
    Am I being influenced by fear or greed?
    Am I following other people without sufficient research?
    Can I afford to lose this money?
    Does this decision support my long-term goals?
    Would I make the same choice tomorrow?
    What would my future self think about this decision?

    These questions cannot guarantee perfect decisions, but they can introduce a valuable pause between impulse and action.

    Conclusion

    Master Your Behavior Before Trying to Master Money

    Financial success is not determined solely by how much you know about money.

    You can understand budgeting and still overspend emotionally. You can understand investing and still panic during market volatility. You can earn a high income and spend all of it trying to maintain an image. You can know that saving is important and continuously postpone starting.

    Knowledge matters—but behavior determines whether knowledge becomes action.

    Learn your emotional triggers. Examine the money beliefs you inherited. Stop measuring your worth through possessions. Practice delayed gratification. Automate good habits. Develop patience. Understand your tolerance for risk. Build financial confidence through small victories. And create financial systems that continue working even when motivation disappears.

    You do not have to become emotionless about money.

    You need to become more aware of how emotions influence your decisions.

    The objective is not to make perfect financial decisions forever. It is to make increasingly better decisions over time.

    Because changing your financial life often begins before your bank balance changes.

    It begins when the way you think about money changes.

    Educational disclaimer: This article provides general financial education and is not individualized financial, investment, psychological, tax or legal advice. Investments involve risk, including possible loss of principal. Financial products, regulations and consumer protections differ by country.

  • How to Escape Poverty: 35 Practical Financial Habits That Change Lives

    How to Escape Poverty: 35 Practical Financial Habits That Change Lives

    A Step-by-Step Guide to Building Skills, Increasing Income, Managing Money and Creating Long-Term Financial Security

    Introduction

    Breaking the Cycle of Poverty Starts With a Practical Plan

    Escaping poverty is rarely the result of one lucky opportunity, one investment, or one dramatic increase in income. For most people, improving their financial position is a gradual process involving better skills, stronger financial habits, increased earning capacity, careful spending, savings, productive relationships, and long-term planning. At the same time, poverty is not caused solely by individual choices. Job availability, wages, education, economic conditions, access to banking, family responsibilities, health costs, inflation, and where a person lives can significantly affect financial opportunity.

    That means there is no universal formula guaranteed to move everyone out of poverty. However, there are practical financial habits that can improve your ability to manage limited resources, pursue opportunities, withstand emergencies, and gradually build assets.

    Whether you live in the United States, Canada, Europe, Australia, Africa, Asia, Latin America, the Caribbean, or elsewhere, these 35 practical financial habits can help you develop a stronger financial foundation and work toward greater economic independence.

    1. Understand What Poverty Really Means

    Poverty is more complicated than simply “not having enough money.”

    It can include inadequate or unstable income, limited savings, high debt, lack of access to education, unemployment or underemployment, insecure housing, limited access to financial services, and an inability to absorb emergencies.

    Understanding your particular financial situation is the first step toward changing it.

    Write down your income, essential expenses, debts, assets, skills, and financial obligations. You cannot build an effective plan until you know your starting point.

    2. Replace a Poverty Mindset With a Growth-Oriented Money Mindset

    A so-called “poverty mindset” should not be used to blame people for circumstances outside their control.

    A more useful concept is developing a growth-oriented financial mindset.

    Instead of thinking, “I will never earn enough,” ask:

    What valuable skill can I learn?
    How could I increase my income?
    Which expenses can I control?
    What opportunities exist around me or online?
    What can I start doing today?

    A wealth-building mindset focuses on possibilities while remaining realistic about risks and circumstances.

    3. Treat Education as an Investment

    Education can extend far beyond earning a university degree.

    Vocational training, apprenticeships, professional certifications, community colleges, technical institutes, online courses, employer training, and self-directed learning can all increase your economic value.

    Before paying for training, ask whether employers actually demand the skill and whether the likely income improvement justifies the cost.

    The goal is not collecting certificates. The goal is acquiring marketable knowledge.

    4. Build Employable Skills

    Learn skills people or businesses are willing to pay for.

    Depending on your location, opportunities could include healthcare, construction, plumbing, electrical work, welding, manufacturing, bookkeeping, sales, logistics, digital marketing, software development, data analysis, graphic design, caregiving, culinary work, agriculture, or equipment operation.

    Study local job advertisements. Look for qualifications that repeatedly appear.

    Then build those qualifications systematically.

    5. Learn One High-Value Skill Deeply

    Trying to learn ten skills simultaneously often produces shallow knowledge.

    Choose one marketable skill and become competent enough to earn from it.

    For example, instead of vaguely “learning computers,” you could learn bookkeeping software, web development, spreadsheet analysis, video editing, digital advertising, or another specific skill.

    Specialized competence can make you more valuable than general familiarity.

    6. Increase Your Primary Income

    Cutting expenses has limits. Income growth has much greater potential.

    Ask whether you can:

    • Work additional hours
    • Move into a higher-paying position
    • Earn a professional certification
    • Negotiate compensation
    • Change employers
    • Learn a trade
    • Develop a specialized skill
    • Relocate where economically realistic
    • Pursue remote employment

    Even a modest permanent increase in monthly income can significantly change your financial trajectory if lifestyle expenses do not increase equally.

    7. Diversify Your Sources of Income

    Depending entirely on one income source creates vulnerability.

    A second source might include freelance work, weekend employment, tutoring, consulting, agriculture, delivery work, selling products, online services, or a small business.

    Do not try everything simultaneously. Build one additional reliable income stream before adding another.

    8. Create a Realistic Budget

    A budget is a plan for your money.

    Start with:

    Income – Essential expenses – Debt obligations – Savings = Available discretionary money

    Track housing, food, transportation, utilities, communication, healthcare, education, debt, and other necessities.

    Budgeting cannot solve inadequate income by itself, but it can help you use available income more intentionally.

    9. Track Where Your Money Goes

    Track every expense for 30 days.

    Small daily purchases can become significant monthly expenses.

    You may discover unused subscriptions, excessive transportation costs, unnecessary fees, frequent takeout meals, impulse purchases, or other expenses that can be reduced.

    Do not guess where your money goes. Measure it.

    10. Set Specific Financial Goals

    Replace vague goals such as “I want to become rich” with measurable targets.

    For example:

    “I will save $1,000 within 10 months.”

    Or:

    “I will complete my professional certification by June and apply for five higher-paying positions every week.”

    A goal needs an amount, action, and deadline whenever possible.

    11. Save Before Increasing Your Lifestyle

    When your income rises, resist immediately upgrading everything.

    This phenomenon is often called lifestyle inflation.

    If your income increases by $200 per month, consider directing part of that increase toward savings, debt reduction, education, or investment before increasing discretionary spending.

    This is one of the most powerful ways to convert higher income into actual financial progress.

    12. Practice Delayed Gratification

    Learn to distinguish “I want it” from “I need it now.”

    For nonessential purchases, wait 24 hours before buying. For expensive purchases, wait several days.

    Investor.gov similarly suggests a 24-hour waiting rule for impulse purchases and explains how small recurring savings can accumulate over time.

    Delayed gratification is not about never enjoying money. It is about controlling when and why you spend it.

    13. Build Your First Emergency Fund

    An emergency fund protects you when life becomes unpredictable.

    Start with an achievable amount—perhaps $100, $500, or the equivalent in your local currency. Then work toward a larger reserve based on your essential expenses and circumstances.

    An emergency fund can reduce the need to borrow when your vehicle breaks down, work hours are reduced, or another unexpected expense occurs.

    Investor.gov identifies an emergency fund as an important component of long-term financial security.

    14. Avoid High-Cost Consumer Debt

    Debt can either support productive goals or destroy financial progress.

    High-interest consumer debt is particularly dangerous because interest consumes future income.

    Before borrowing, ask:

    Will this debt help me generate income or build something valuable—or am I borrowing simply to consume something today?

    Investor.gov recommends aggressively addressing high-interest debt because interest charges can significantly interfere with saving and wealth building.

    15. Pay Bills on Time

    Late fees are money lost without receiving anything valuable in return.

    Create reminders, calendar alerts, or automatic payments where appropriate and safe.

    Good payment habits can also contribute to stronger creditworthiness in countries where formal credit reporting systems are used.

    16. Read About Personal Finance Regularly

    Financial education is a lifelong process.

    Read books and reputable resources about budgeting, saving, investing, entrepreneurship, taxes, insurance, debt, and retirement.

    Do not rely solely on social-media influencers.

    For introductory investing education, Investor.gov provides free information about saving, investing, diversification, risk, and financial planning.

    17. Build Relationships With Ambitious People

    Your network can expose you to opportunities you might never discover alone.

    Build genuine relationships with employers, entrepreneurs, skilled workers, former classmates, professional organizations, community leaders, and people working in industries you want to enter.

    Networking is not begging people for jobs.

    It means developing relationships in which information, experience, referrals, and opportunities can be shared.

    18. Find Mentors

    A good mentor can help you avoid expensive mistakes.

    Look for someone with genuine experience in the field you want to enter.

    Ask specific questions:

    What skills should I learn?
    What mistakes should I avoid?
    What would you do if you were starting today?

    Be cautious of anyone demanding large payments while promising guaranteed wealth.

    19. Consider Entrepreneurship Carefully

    Entrepreneurship can create income and assets, but it also carries risk.

    Start by solving a real problem.

    Instead of asking, “What business should I start?”, ask:

    “What problem are people willing to pay me to solve?”

    Test your idea inexpensively before investing substantial money.

    A small profitable business is better than an impressive business that constantly loses money.

    20. Start Small Before Borrowing Big

    Many businesses can initially be tested at small scale.

    A baker might begin with pre-orders. A designer can start freelancing. A tutor can find a few students. A farmer can test a higher-value crop on a limited area.

    Validate demand before taking significant debt.

    Revenue should prove the idea whenever possible.

    21. Explore Digital Opportunities

    he internet has expanded the geographic reach of employment and entrepreneurship.

    Potential opportunities include freelancing, remote customer support, online tutoring, e-commerce, digital marketing, software development, content creation, bookkeeping, translation, virtual assistance, and consulting.

    Digital financial services can also expand access to payments and financial products. The World Bank notes that such services can reduce costs and increase transaction speed and access, while also introducing risks including privacy, cybersecurity, and predatory lending.

    22. Learn How AI Can Increase Your Productivity

    Artificial intelligence is creating new ways to work faster and develop services.

    AI tools may assist with research, writing, translation, data organization, customer service, coding, marketing, design concepts, and administrative tasks.

    The opportunity is not simply “make money with AI.”

    Learn how to combine AI with a valuable human skill.

    For example:

    Marketing skill + AI
    Bookkeeping knowledge + AI
    Programming + AI
    Design + AI
    Research + AI

    AI should amplify useful skills rather than replace the need to develop them.

    23. Use Social Media as a Business Tool

    Social media does not have to be only entertainment.

    It can help you build professional visibility, demonstrate skills, attract customers, market a small business, develop a portfolio, or connect with employers.

    Choose a niche, publish useful content consistently, and build credibility.

    Do not assume followers automatically equal income.

    24. Protect Your Time

    Time is an economic resource.

    Entertainment and social media can consume hours that could otherwise be used for studying, job applications, building a side business, networking, exercising, or learning.

    You do not need to eliminate recreation.

    Simply become intentional about where your hours go.

    25. Start Investing Only When You Understand the Risk

    Investing can help build long-term wealth, but investments can lose money.

    Before investing, understand the product, fees, risks, liquidity, and time horizon.

    Investor.gov explains that asset allocation and diversification can help manage investment risk, although diversification cannot guarantee against losses.

    Never invest money needed for rent, food, emergencies, or immediate obligations in volatile assets.

    26. Start Small With Investments

    You do not necessarily need a large fortune to begin investing where suitable regulated options are available.

    A small regular contribution can develop the habit.

    Investor.gov summarizes long-term wealth building with the principle that regular investments plus time can create wealth, while emphasizing that all investments involve risk.

    The exact products available depend on your country and regulatory system.

    27. Avoid Get-Rich-Quick Schemes

    Financial desperation makes people especially vulnerable to scams.

    Be suspicious of:

    • Guaranteed investment returns
    • “Risk-free” high profits
    • Secret trading systems
    • Pressure to invest immediately
    • Unlicensed investment operators
    • Requests to recruit others primarily to earn money
    • Fake cryptocurrency opportunities

    Investor.gov identifies promises of high returns with little or no risk, urgency, FOMO, and suspicious payment methods as common fraud warning signs.

    Protecting your existing money is part of escaping poverty.

    28. Build Assets Instead of Only Buying Liabilities

    Ask whether your money is purchasing something that can improve your financial position.

    Assets may include appropriate investments, productive equipment, business inventory, intellectual property, education that improves earnings, or property depending on circumstances.

    Not every asset generates income, and not every purchase commonly called an “asset” will appreciate.

    Evaluate purchases based on their real economic value to you.

    29. Protect Yourself With Appropriate Insurance

    One serious event can erase years of financial progress.

    Depending on your country and circumstances, appropriate health, vehicle, property, disability, business, crop, or life insurance may protect against catastrophic losses.

    Insurance systems vary significantly worldwide, so understand exclusions, deductibles, coverage limits, and the reputation of the provider before purchasing.

    30. Use Financial Services Safely

    Bank accounts, credit unions, mobile money, digital wallets, and regulated financial services can make saving and payments easier.

    The World Bank describes access to affordable payments, savings, credit, and insurance as important to poverty reduction and economic growth.

    But always protect passwords, PINs, verification codes, and personal information.

    Never send money merely because an unexpected message claims you must act immediately.

    31. Invest in Your Health and Ability to Work

    Your ability to earn is one of your most important economic assets.

    Within your means, prioritize adequate sleep, nutrition, preventative care, exercise, workplace safety, and medical attention when necessary.

    Poor health can create expenses and reduce earning capacity, although many health circumstances are outside an individual’s control.

    Protect your ability to remain productive whenever possible.

    32. Measure Your Net Worth

    Income tells you what you earn.

    Net worth helps show what you are building.

    Calculate:

    Assets – Liabilities = Net Worth

    Do not panic if the number is initially negative.

    Use it as a starting point.

    Recalculate every six or twelve months. Progress might mean increasing savings, reducing debt, acquiring productive assets, or building investments.

    33. Create a Five-Year Financial Plan

    Ask yourself:

    Where do I want to be financially five years from now?

    Your plan might include:

    • A new professional qualification
    • Higher income
    • No high-interest consumer debt
    • A fully funded emergency reserve
    • A profitable side business
    • Regular investments
    • A home deposit
    • Education funding
    • Retirement contributions

    Then work backward and determine what must happen this year.

    34. Build a Long-Term Financial Plan

    Financial progress does not stop once your immediate situation improves.

    Think about retirement, housing, children’s education, healthcare, business succession, insurance, investments, taxes, and estate planning where applicable.

    Investor.gov emphasizes setting financial goals, creating a plan, regularly investing, controlling high-interest debt, and maintaining emergency savings as components of long-term wealth building.

    Your country’s financial system will determine which retirement and investment vehicles are available.

    35. Become Consistent Instead of Searching for Perfection

    The final habit connects everything else.

    Consistency matters more than occasional bursts of motivation.

    Save repeatedly.

    Learn repeatedly.

    Apply for opportunities repeatedly.

    Improve your skills repeatedly.

    Review your budget repeatedly.

    Invest carefully and consistently when financially ready.

    A person who makes small improvements for years may ultimately achieve more than someone constantly searching for one dramatic shortcut.

    Real-Life Example 1: From Low Income to a Marketable Skill

    Imagine Samuel earns the equivalent of $350 per month and struggles to cover expenses.

    Instead of borrowing money to start a large business, he studies job advertisements and discovers strong local demand for commercial electrical technicians.

    He saves gradually, completes affordable technical training, gains entry-level experience, and eventually moves into a higher-paying role.

    His transformation did not begin with investing.

    It began with increasing the market value of his labor.

    Real-Life Example 2: Turning a Small Skill Into Additional Income

    Amina already works full-time but enjoys baking.

    She begins accepting small weekend orders rather than immediately renting a commercial shop. She tracks ingredient, packaging, transportation, electricity, and marketing costs.

    As demand grows, she reinvests part of the profits into equipment.

    Eventually, the business creates a meaningful second income.

    The lesson is simple: test small, measure demand, control costs, and scale gradually.

    Real-Life Example 3: Using Digital Skills to Reach a Global Market

    Daniel lives in a country where local wages are relatively low.

    He learns video editing and creates a portfolio. Instead of depending exclusively on local clients, he begins offering services remotely.

    His first projects pay little, but reviews, experience, and better skills allow him to pursue higher-value work.

    The internet does not guarantee financial success, but digital skills can sometimes expand the market in which your labor competes.

    What Successful Financial Journeys Have in Common

    Success stories often appear dramatic when viewed from the end.

    What we do not see are the years of learning, rejection, small savings, unsuccessful applications, business experiments, disciplined spending, and gradual improvement that came first.

    Sustainable financial progress commonly involves several elements working together:

    Skills + Income + Financial Discipline + Savings + Productive Assets + Time

    Remove financial discipline and higher income can disappear.

    Remove income growth and saving may remain extremely difficult.

    Remove skills and opportunities may be limited.

    Remove time and people become vulnerable to unrealistic get-rich-quick promises.

    The goal is to strengthen all of these areas gradually.

    Conclusion

    Escaping Poverty Is a Journey, Not a Single Financial Decision

    There is no honest promise that 35 habits will automatically lift every person out of poverty. Economic circumstances differ dramatically around the world, and many barriers cannot be solved through personal budgeting alone.

    But you can focus on the areas where you have influence.

    Learn valuable skills. Pursue better income. Build multiple income sources carefully. Control unnecessary spending. Avoid destructive debt. Create emergency savings. Use digital opportunities intelligently. Build professional relationships. Explore entrepreneurship by solving real problems. Invest cautiously when financially ready. Protect yourself from scams. Develop assets and plan years—not days—ahead.

    You do not have to transform your financial life overnight.

    Choose three habits from this guide and begin there.

    Then add another.

    The objective is not instant wealth. It is to create a financial position that becomes progressively stronger, more resilient, and more capable of generating opportunities.

    Learn more. Earn more. Keep more. Build assets. Protect your progress. Give the process time.

    Educational disclaimer: This article provides general financial education and does not guarantee that any strategy will eliminate poverty or produce wealth. Income opportunities, investments, financial products, taxes, labor markets, regulations, and consumer protections vary by country. Investments involve risk, including possible loss of principal. Consider qualified local professional guidance where appropriate.

  • Why Saving Is the Foundation of Wealth: A Complete Step-by-Step Guide for Beginners (Even on a Small Income)

    Why Saving Is the Foundation of Wealth: A Complete Step-by-Step Guide for Beginners (Even on a Small Income)

    Learn Practical Saving Systems, Budgeting Strategies, and Wealth-Building Habits That Can Transform Your Financial Future

    Introduction

    Building wealth does not begin with earning a huge salary—it begins with learning how to manage and save the money you already have. Whether you are a student, employee, entrepreneur, supporting a family, living on a small income, or dealing with irregular earnings, developing consistent saving habits can create the foundation for greater financial security and long-term wealth. In this complete beginner’s guide, you will learn how to save money and build wealth through practical saving strategies, budgeting, emergency funds, the Pay Yourself First method, automated savings, and other proven money-management habits. You will also discover how to protect your savings and eventually turn accumulated savings into investment capital, helping you move step by step toward greater financial stability and financial freedom.

    Saving creates the financial foundation from which emergency security, investing, homeownership, entrepreneurship, retirement planning, and long-term wealth can grow.

    You may earn $1,000, $3,000, or $10,000 a month, but income alone does not determine financial security. What matters is how much of your income you keep, how effectively you manage it, and what you eventually do with the money you accumulate. This beginner-friendly guide explains practical saving techniques you can use whether you have a regular salary, irregular income, are a student, supporting a family, temporarily unemployed, or simply starting your financial journey

    Why Saving Is the Foundation of Wealth

    Saving creates a gap between what you earn and what you spend. That gap is where financial progress begins.

    Without savings, an unexpected car repair, medical expense, job interruption, or family emergency can force you to borrow. With savings, the same event may become an inconvenience rather than a financial crisis.

    The U.S. Consumer Financial Protection Bureau explains that even a small dedicated emergency fund can help people recover more quickly from unexpected expenses. CFPB Emergency Fund Guide

    Saving also creates capital. The first $500 you save may become an emergency cushion. Later, $5,000 or $10,000 could help finance education, a business, a home purchase, or long-term investments.

    Common Myths About Saving Money

    One of the biggest myths is: “I will start saving when I earn more.”

    Higher income certainly makes saving easier, but earning more does not automatically create wealth. If spending rises every time income increases, there may still be nothing left.

    Another myth is that small amounts are meaningless. They are not. Saving $5 a day equals $1,825 in one year before interest. The SEC’s Investor.gov explains how small amounts can become considerably larger over time when saving and investing are combined with compound growth. See How Small Savings Can Add Up

    The habit matters before the amount becomes large.

    Why Income Alone Doesn’t Create Wealth

    Imagine two workers.

    Person A earns $8,000 monthly but spends $8,200. Person B earns $4,000 but consistently saves $600.

    Who is moving toward greater financial stability?

    Income provides opportunity. Financial discipline determines what happens to that opportunity.

    Increasing your earnings is important, but building wealth usually requires controlling expenses, saving consistently, managing debt carefully, and eventually putting appropriate long-term money to productive use.

    Set SMART Savings Goals

    “Save more money” is a wish. A specific savings target is a plan.

    Use the SMART framework: make your goal Specific, Measurable, Achievable, Relevant, and Time-bound.

    Instead of saying, “I want an emergency fund,” say:

    “I will save $1,200 during the next 12 months by automatically transferring $100 each month into a separate savings account.”

    You immediately know the destination, deadline, and required monthly contribution.

    Investor.gov also provides a free Savings Goal Calculator that can help estimate how much you need to save regularly to reach a financial target.

    Create Your First Emergency Fund

    Before chasing high investment returns, establish financial protection.

    Start with an achievable milestone such as $500 or $1,000. Then work toward one month of essential expenses and gradually increase your reserve according to your circumstances.

    Some financial professionals commonly suggest eventually holding roughly three to six months of essential expenses, although the appropriate amount depends on employment stability, household responsibilities, health expenses, insurance, and other risks.

    Keep emergency savings somewhere safe and reasonably accessible rather than exposing money needed soon to unnecessary market risk.

    Use the Pay Yourself First Principle

    Most people follow this formula:

    Income → Expenses → Save whatever remains.

    Try reversing it:

    Income → Savings → Necessary expenses → Discretionary spending.

    This is the Pay Yourself First principle.

    When your paycheck arrives, transfer a predetermined amount into savings before optional spending begins. Even 5% is a meaningful starting point if that is what your budget allows.

    Saving becomes a financial obligation to your future self rather than an afterthought.

    Daily, Weekly and Monthly Saving Systems

    Different saving schedules work for different personalities.

    For a daily system, save a small fixed amount, transfer spare change, or redirect the cost of one unnecessary purchase. A $3 daily habit becomes more than $1,000 over a year.

    For a weekly system, choose one day—perhaps every Friday—to review spending and transfer a predetermined amount.

    For a monthly system, treat savings like rent or another recurring bill. Schedule it immediately after payday.

    Consistency is more important than choosing the “perfect” schedule.

    Try the 52-Week Saving Challenge

    The 52-week challenge turns saving into a gradual habit.

    Traditionally, you save $1 in week one, $2 in week two, $3 in week three, continuing until $52 in week 52. Completing the challenge produces $1,378.

    You can also reverse the challenge, starting with $52 and decreasing each week, or use a fixed weekly amount that better matches your income.

    The objective is not the specific formula. It is developing consistency.

    Automate Your Savings

    Automation removes repeated decision-making.

    Schedule an automatic transfer from checking to savings shortly after each payday. If your employer permits split direct deposit, you may be able to send part of every paycheck directly into savings.

    The CFPB specifically identifies automatic deposits and recurring transfers as practical ways to build savings consistently. CFPB Guide to Saving Automatically When saving happens automatically, you are less dependent on motivation

    Choose a Budgeting Method You Can Maintain

    A budget tells your money where it should go.

    One popular starting framework is the 50/30/20 approach: roughly 50% toward needs, 30% toward wants, and 20% toward savings and/or financial priorities. Those percentages are guidelines, not rules. Someone with high housing costs or a low income may need a different allocation.

    Another approach is zero-based budgeting, where every dollar of expected income receives a purpose before the month begins.

    The best budget is not necessarily the most complicated one. It is the system you can realistically follow month after month.

    Consider a High-Yield Savings Account

    Leaving substantial savings in an account paying very little interest can reduce its growth potential.

    A competitive high-yield savings account may provide a better return while retaining relatively easy access. Rates change, so compare APY, minimum balances, withdrawal options, fees, and deposit protection rather than choosing an account based only on an advertisement.

    In the United States, eligible deposits at an FDIC-insured bank are automatically insured to at least $250,000 per depositor, per insured bank, subject to ownership-category rules. Learn About FDIC Deposit Insurance

    Readers outside the United States should check their country’s equivalent deposit-protection system.

    Cut Unnecessary Expenses Without Making Life Miserable

    Saving does not require eliminating everything you enjoy.

    Start by identifying expenses providing little value: forgotten subscriptions, frequent delivery fees, impulse purchases, excessive banking fees, unused memberships, or expensive habits that have cheaper alternatives.

    Try a 24-hour rule before nonessential purchases. For larger purchases, consider waiting several days.

    Redirect at least part of the money you avoid spending directly into savings. Otherwise, “saving money” on one purchase can easily become spending it somewhere else.

    How to Save With Irregular Income or While Unemployed

    Freelancers, seasonal workers, gig workers, and entrepreneurs can save using percentages rather than fixed amounts.

    For example, decide that 5% or 10% of every payment received goes into savings. During high-income months, save more to create a buffer for slower periods.

    If unemployed, the immediate goal may change from aggressive saving to protecting existing cash. Prioritize housing, food, utilities, transportation, insurance, and other essentials. Reduce nonessential expenses and investigate legitimate benefits or assistance for which you qualify.

    Saving $5 during a difficult month still maintains the habit—but essential needs come first.

    Saving as a Student

    Students have one enormous financial advantage: time.

    Begin with manageable amounts. Save part of income from a part-time job, scholarship refund that is genuinely available for personal use, gifts, or other discretionary income.

    Learning budgeting, avoiding unnecessary debt, comparing prices, cooking more often, using student discounts, and saving even $10 or $20 regularly can establish habits that continue long after graduation.

    Family Saving Strategies

    Household saving works better when financial goals become shared goals.

    Families can create separate savings categories for emergencies, education, vacations, home repairs, vehicles, and major purchases. Parents can also involve children in age-appropriate discussions about needs, wants, saving, and delayed gratification.

    A family target—such as saving $3,000 for emergencies—can be divided into smaller monthly milestones so everyone can see progress.

    Use Mobile Banking and Savings Apps Carefully

    Modern banking makes saving easier. Mobile banking apps can provide automatic transfers, balance alerts, savings goals, spending notifications, and recurring deposits.

    Budgeting tools such as YNAB can help users plan where their money goes, while Acorns combines automated saving and investing features.

    No app is universally “best.” Compare subscription costs, security, account protection, features, withdrawal restrictions, and whether the service involves saving or investing. Investment accounts can lose value and should not be confused with insured bank savings.

    Common Saving Mistakes to Avoid

    The biggest mistakes include waiting for the “perfect” income, setting unrealistic targets, keeping no emergency reserve, repeatedly withdrawing savings for non-emergencies, ignoring high-interest debt, failing to track expenses, and increasing lifestyle spending every time income rises.

    Another mistake is treating every saved dollar as investment money. Emergency savings and long-term investments have different purposes

    Protect Your Savings

    Building money is only half the job. You must protect it.

    Use strong unique passwords, multi-factor authentication where available, account alerts, and reputable financial institutions. Be suspicious of unsolicited messages promising guaranteed profits or unusually high returns.

    Investor.gov warns that promises of high investment returns with little or no risk, pressure to act immediately, fake testimonials, and suspicious payment methods are common investment-fraud warning signs. Investor.gov Fraud and Investor Education Resources

    Turn Savings Into Investment Capital

    Saving provides security. Investing can provide long-term growth.

    Once you have appropriate emergency reserves and control over expensive debt, some money intended for long-term goals may potentially move toward diversified investments appropriate to your objectives, time horizon, and risk tolerance.

    Do not invest emergency money you may need next month.

    Investor.gov describes regular investing plus time as a powerful approach to building wealth and recommends establishing emergency savings alongside long-term investing. SEC Guide to Building Wealth Through Saving and Investing

    Case Studies: How Small Savings Can Build Financial Momentum

    Case Study 1 — The beginner: Maria can save only $25 each week. Instead of waiting until she earns more, she automates the transfer. After 52 weeks, she has contributed $1,300 before any interest. Her first financial victory is not becoming rich—it is proving she can consistently keep money.

    Case Study 2 — The irregular-income worker: Daniel’s monthly income changes. Rather than promising himself a fixed $300 contribution he cannot always afford, he saves 10% whenever he gets paid. Strong months automatically produce larger contributions, while difficult months remain manageable.

    Case Study 3 — The lifestyle reset: Aisha reviews several months of transactions and discovers approximately $180 per month going toward subscriptions, delivery fees, and impulse purchases she barely remembers. She cuts $100 and automatically transfers it monthly. In one year, she contributes $1,200 toward her emergency fund without increasing her salary.

    These examples are illustrative, but the principle is universal: wealth-building starts when part of today’s income is deliberately reserved for tomorrow.

    Final Thoughts: Start Small, Start Today

    You do not need to become wealthy before you begin saving. Saving is one of the habits that can help you build wealth.

    Start with an amount you can sustain. Create an emergency fund. Pay yourself first. Automate your contributions. Control unnecessary spending. Increase the amount when your income rises. Protect the money you accumulate. Then learn how to responsibly put long-term capital to work.

    Your first $10 may not appear life-changing. Neither may your first $100.

    But the habit behind those dollars can change the direction of your financial life.

    Start today. Save consistently. Protect what you build. Then give your money time to grow.

    Educational disclaimer: This article provides general financial education and does not constitute individualized financial, investment, tax, or legal advice. Financial products, regulations, interest rates, risks, and deposit-protection rules vary by country and can change over time.