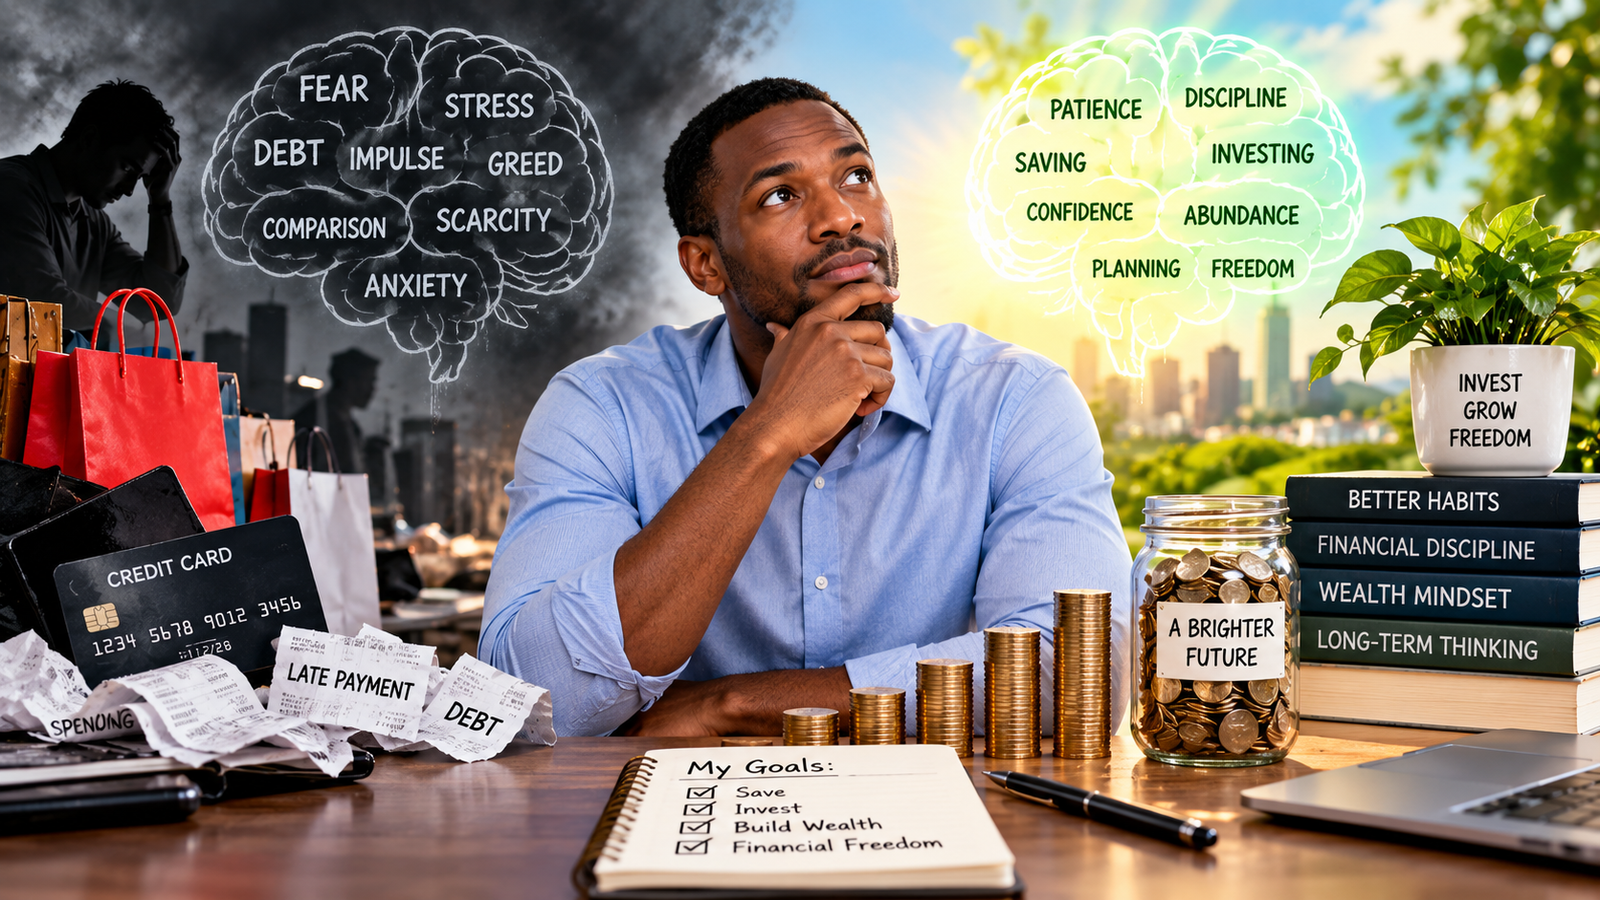
Understand Your Money Mindset, Control Emotional Spending, Build Better Financial Habits and Make Smarter Decisions About Saving, Spending and Investing
Introduction
Your Financial Life Begins in Your Mind. Why can two people earning similar incomes have completely different financial lives? Why does one person consistently save while another repeatedly spends everything? Why do intelligent investors sometimes panic when markets fall, while others become dangerously confident when prices rise?
The answers often involve more than mathematics. Money is psychological.
Our financial decisions can be influenced by emotions, childhood experiences, family expectations, social pressure, fear, greed, confidence, habits and beliefs about what money represents. Behavioral finance examines how psychological influences can affect financial decisions, including decisions that do not always follow purely rational economic assumptions.
Understanding your own behavior therefore can be just as important as understanding interest rates, budgets or investments.
These 40 lessons explore the psychology behind spending, saving, investing and wealth building—and provide practical ways to develop a healthier relationship with money.
1. Money Is Emotional
Money is rarely just numbers in a bank account.
It can represent security, freedom, success, independence, power, status or even fear. That emotional connection can influence financial decisions without us realizing it.
Before making an important financial decision, ask yourself:
Am I making this decision based on facts—or feelings?
Recognizing the emotion is the first step toward controlling its influence.
2. Understand Emotional Spending
Some people shop when they feel stressed, lonely, bored, frustrated or even excited.
The purchase provides temporary satisfaction, but the underlying emotion remains.
Before making an unplanned purchase, identify what triggered the desire. If the purchase is emotional rather than necessary, wait 24 hours.
That short delay can separate the emotion from the financial decision.
3. Examine Your Money Beliefs
Everyone develops beliefs about money.
You may believe:
“Money is difficult to earn.”
“Rich people are greedy.”
“I will always struggle financially.”
“Having more money will solve everything.”
Some beliefs may motivate you. Others may limit you.
Ask yourself where each belief originated and whether evidence actually supports it.
4. Understand Your Childhood Money Influences
Your earliest financial education probably occurred before you understood what finance meant.
Perhaps your parents constantly worried about bills. Maybe money was never discussed. Perhaps spending demonstrated success, or extreme saving was considered virtuous.
These experiences can influence adult behavior.
You don’t have to blame your childhood. Instead, identify which lessons are worth keeping and which should be reconsidered.
5. Separate Your Identity From Your Income
Your salary is not your personal worth.
Someone earning more money is not automatically more intelligent, responsible or valuable.
Connecting self-worth to income can encourage status spending and unhealthy comparisons.
Treat income as a financial resource—not a measurement of human value.
6. Recognize the Scarcity Mindset
When money is genuinely scarce, focusing intensely on immediate needs can be necessary.
But scarcity can also narrow attention so much that long-term planning becomes difficult.
If every decision is focused exclusively on surviving today, saving, training and future planning may receive little attention.
Begin with small steps. Even planning one week ahead can be progress when circumstances are difficult.
7. Develop an Opportunity-Oriented Mindset
An abundance mindset does not mean pretending unlimited money exists.
A healthier interpretation is believing that skills can improve, opportunities can be pursued, knowledge can increase and financial circumstances can potentially change.
Instead of asking only:
“What can I cut?”
also ask:
“How can I increase my value and income?”
Financial progress often requires both.
8. Understand Fear
Fear can protect your money—but it can also paralyze you.
Fear might prevent someone from investing anything, negotiating salary, changing careers or starting a carefully researched business.
Ask:
What exactly am I afraid will happen? What evidence supports that fear? How could I reduce the risk?
Turning vague fear into measurable risk makes better decisions possible.
9. Understand Greed
Greed can push people toward investments they barely understand because someone promises extraordinary returns.
The higher the promised reward, the more carefully you should investigate the risk.
Never allow the desire to become wealthy quickly to override basic due diligence.
10. Practice Delayed Gratification
Delayed gratification means accepting a smaller reward today in pursuit of a potentially greater future benefit.
Instead of immediately spending a bonus, you might save part of it.
Instead of financing an unnecessary luxury purchase, you might wait until you can comfortably afford it.
This habit sits at the heart of long-term wealth building.
11. Learn to Wait Before Buying
Create a waiting rule:
24 hours for small discretionary purchases.
Several days for expensive purchases.
Waiting gives excitement time to decline.
You may discover that something you desperately wanted yesterday feels unnecessary tomorrow.
12. Stop Using Money to Impress People
Status spending can become extremely expensive.
Luxury vehicles, clothing, electronics and other possessions may communicate wealth without actually creating it.
Someone can look wealthy while carrying substantial debt.
Financial security is often largely invisible: savings, investments, manageable debt and adequate financial reserves rarely attract attention.
13. Understand Lifestyle Inflation
When income increases, spending often increases with it.
You get a raise and immediately upgrade the vehicle, apartment, phone, wardrobe or vacations.
Enjoying higher income is not inherently wrong.
The danger appears when every income increase becomes a permanent expense increase.
Automatically save or invest part of future raises before adjusting your lifestyle.
14. Make Saving Automatic
Saving requires less willpower when it happens automatically.
Where available, schedule automatic transfers shortly after receiving income.
Psychologically, money that immediately moves into savings is less likely to feel available for everyday spending.
The goal is to make good behavior easier.
15. Give Savings an Emotional Purpose
“Save $5,000” may not feel motivating.
“Build six months of security for my family” creates meaning.
Attach savings goals to outcomes:
Emergency security
Education
Homeownership
Business capital
Travel
Retirement
Financial independence
Purpose strengthens motivation.
16. Celebrate Saving Milestones
arge goals can feel distant.
Break them into smaller victories.
If your goal is $10,000, celebrate psychologically—not necessarily by spending heavily—when you reach $1,000, $2,500, $5,000 and $7,500.
Visible progress encourages consistency.
17. Understand Why Habits Beat Motivation
Motivation changes from day to day.
Habits continue even when motivation disappears.
Build routines around payday, budgeting, saving and investing.
For example:
Payday → Save automatically → Pay bills → Spend remaining budget
Repeated systems reduce dependence on willpower.
18. Control Your Financial Environment
Your environment influences behavior.
Shopping notifications, promotional emails, one-click purchasing and social-media advertising constantly encourage consumption.
Unsubscribe from unnecessary marketing. Remove stored payment information if impulse buying is a problem. Avoid browsing online stores for entertainment.
Sometimes the easiest way to improve discipline is to remove temptation.
19. Understand Consumer Psychology
Businesses study consumer behavior carefully.
Scarcity messages such as “Only two remaining!”, countdown timers, discounts and limited-time promotions can create urgency.
A discount is not automatically a saving.
If you spend $70 on something you didn’t need because it was reduced from $100, you did not necessarily “save $30.” You still spent $70.
20. Stop Comparing Your Finances With Social Media
Social media shows outcomes without necessarily showing financial reality.
You may see someone’s vacation without seeing the credit-card balance. You see the vehicle without knowing the monthly payment.
Comparison can create pressure to spend money proving that you are equally successful.
Measure your progress against your own goals instead.
21. Understand Present Bias
Humans often give disproportionate importance to immediate rewards.
Spending $100 today feels real. Having $100 plus potential growth decades later feels distant.
This helps explain why retirement saving can be psychologically difficult.
Bring the future closer by visualizing what today’s financial decision means for your future lifestyle.
22. Meet Your Future Self
Imagine yourself 10, 20 or 30 years from now.
Where will you live?
Will you still need to work?
What financial obligations might you have?
Now ask:
What would that future version of me wish I had started doing today?
This can transform saving from sacrifice into self-care for your future.
23. Understand Loss Aversion
People often experience the pain of losses strongly, sometimes more intensely than equivalent gains feel rewarding.
This can affect investment decisions.
An investor may sell during a market decline simply to stop the emotional discomfort—or hold a losing investment irrationally because selling would make the loss feel “real.”
Investment decisions should be based on goals, risk tolerance, diversification and evidence rather than panic.
24. Beware of Herd Behavior
When everyone seems to be buying an investment, fear of missing out can become powerful.
But popularity does not prove value.
Before investing, ask:
Would I still buy this if nobody on social media were talking about it?
If the answer is no, investigate further.
25. Watch for Overconfidence
Success can create dangerous confidence.
After several profitable investments, someone may conclude that they possess exceptional forecasting ability.
That can lead to larger bets and excessive risk.
A favorable outcome does not always mean the original decision was wise. Sometimes luck contributes.
26. Recognize Confirmation Bias
People naturally seek information supporting what they already believe.
If you love a particular investment, you may focus on positive articles while dismissing warnings.
Challenge yourself deliberately:
What evidence would prove my assumption wrong?
Good decision-making requires examining opposing evidence.
27. Know Your Risk Tolerance
Investment risk is partly financial and partly psychological.
An investment may appear appropriate mathematically but still be unsuitable if normal price fluctuations cause you to panic.
Understand both your ability and willingness to tolerate losses.
Your investment strategy should reflect your goals, time horizon, circumstances and capacity for risk.
28. Don’t Make Major Money Decisions During Extreme Emotions
Avoid important financial decisions when you are panicked, furious, euphoric or desperate whenever circumstances allow.
Strong emotions can narrow judgment.
Write down the decision, gather information, consider alternatives and revisit it when your emotional state is calmer.
29. Build Financial Confidence Through Small Wins
Financial confidence develops through action.
Create a $100 emergency fund.
Pay off one small debt.
Follow your budget for one month.
Complete a financial course.
Negotiate one bill.
Small achievements provide evidence that you can manage money effectively.
30. Accept That Wealth Building Is Usually Boring
Sustainable financial progress often lacks excitement.
Budget.
Save.
Increase income.
Avoid unnecessary debt.
Invest appropriately.
Repeat for years.
The search for constant financial excitement can lead people toward excessive trading, speculation and scams.
Boring consistency can be powerful.
31. Build Patience
Compounding requires time.
Skills require time.
Businesses require time.
Careers require time.
Wealth generally requires time.
Do not compare your first year with someone else’s twentieth year.
Judge whether your direction is improving.
32. Avoid Financial Perfectionism
You will make money mistakes.
You may overspend one month, choose a poor investment, miss a savings target or regret a purchase.
Do not respond by abandoning your entire financial plan.
Ask what happened, correct the behavior and continue.
Progress matters more than perfection.
33. Create Rules Before Temptation Arrives
Financial rules simplify decision-making.
Examples include:
I save 10% of every payment.
I wait 48 hours before purchases above $200.
I never borrow for vacations.
I research investments before committing money.
I increase retirement contributions whenever my income rises.
Decisions made calmly can protect you when emotions become stronger.
34. Separate Emergency Money From Spending Money
Keeping all money together can create the illusion that you have more available to spend.
Where practical, separate emergency savings from everyday transaction accounts.
Creating physical or psychological boundaries around savings reduces temptation.
35. Define What “Enough” Means
Without a definition of enough, financial goals can become endless.
More income. A bigger house. A newer vehicle. A larger investment portfolio.
There will almost always be someone with more.
Determine what financial success means to you.
Security? Freedom? Family stability? Early retirement? Entrepreneurship? Generational wealth?
Your definition determines your strategy.
36. Use Money to Buy Freedom, Not Only Things
One of money’s greatest benefits is optionality.
Savings may allow you to leave an unhealthy job, survive unemployment, pursue education, care for family, relocate, start a business or retire with dignity.
Think of savings not merely as numbers.
Think of them as future choices.
37. Reduce Financial Stress With Systems
Money stress often increases when finances feel uncertain.
Create systems:
Know your bills.
Track your debts.
Automate essential payments where appropriate.
Build emergency savings.
Maintain a budget.
Review accounts regularly.
A system cannot eliminate every financial problem, but greater visibility can reduce uncertainty.
38. Hold a Weekly Money Meeting With Yourself
Choose 15–20 minutes once each week.
Review:
Account balances
Recent spending
Upcoming bills
Savings progress
Debt balances
Financial goals
For couples or families managing money together, a regular household financial meeting can improve communication and shared accountability.
39. Learn From Your Financial Decisions
At the end of each month, identify:
One financial decision that worked.
One mistake you made.
One expense you could reduce.
One behavior you want to repeat.
One improvement for next month.
Financial intelligence develops through reflection as well as education.
40. Build a Financial Identity
Instead of repeatedly telling yourself:
“I am terrible with money,”
build a new identity through repeated actions:
“I am someone who plans before spending.”
“I save part of what I earn.”
“I research before investing.”
“I don’t need to impress people with purchases.”
“I make decisions for both my present and future.”
Identity reinforces behavior, and behavior eventually produces financial results.
Practical Example: The Emotional Spender
Imagine Sarah frequently shops online after stressful workdays.
She initially thinks her problem is simply poor budgeting.
After tracking her behavior, however, she discovers that most unnecessary purchases occur late at night following stressful days.
She creates a new rule: items go into the shopping cart, but she cannot purchase them for 48 hours.
Many never get purchased.
Her financial improvement came not from earning more but from understanding the psychological trigger behind her spending.
Practical Example: The Fearful Saver
David saves consistently but refuses to learn about investing because he fears losing any money.
His caution protects him from reckless speculation, but fear may also prevent him from considering suitable long-term options.
Rather than jumping into an investment he doesn’t understand, David learns about diversification, risk, fees and long-term investing.
Knowledge allows him to distinguish calculated risk from blind risk.
Practical Example: The Lifestyle Trap
Michael receives a significant salary increase.
Within months he leases a more expensive vehicle, moves into a larger apartment and increases restaurant spending.
His salary is higher, but his savings rate barely changes.
When he receives his next raise, he changes strategy: half of the increase is automatically directed toward long-term financial goals before his lifestyle expands.
Higher income finally begins producing higher wealth.
Daily Exercises to Improve Your Money Psychology
Understanding financial psychology becomes valuable when knowledge changes behavior. Try these exercises regularly:
Morning: Identify one financial priority for the day.
Before purchasing: Ask, “Do I need this, value this, or am I reacting emotionally?”
After spending: Record the purchase and briefly identify why you made it.
Daily: Avoid at least one unnecessary purchase and record the amount.
Weekly: Review spending and identify emotional triggers.
Monthly: Calculate savings, debt reduction and progress toward your goals.
Quarterly: Review your income, investments, financial goals and risk tolerance.
Annually: Compare your financial position with the previous year—not with another person’s lifestyle.
A Simple Money Psychology Checklist
Before making a significant financial decision, ask yourself:
What am I feeling right now?
What is motivating this decision?
Am I being influenced by fear or greed?
Am I following other people without sufficient research?
Can I afford to lose this money?
Does this decision support my long-term goals?
Would I make the same choice tomorrow?
What would my future self think about this decision?
These questions cannot guarantee perfect decisions, but they can introduce a valuable pause between impulse and action.
Conclusion
Master Your Behavior Before Trying to Master Money
Financial success is not determined solely by how much you know about money.
You can understand budgeting and still overspend emotionally. You can understand investing and still panic during market volatility. You can earn a high income and spend all of it trying to maintain an image. You can know that saving is important and continuously postpone starting.
Knowledge matters—but behavior determines whether knowledge becomes action.
Learn your emotional triggers. Examine the money beliefs you inherited. Stop measuring your worth through possessions. Practice delayed gratification. Automate good habits. Develop patience. Understand your tolerance for risk. Build financial confidence through small victories. And create financial systems that continue working even when motivation disappears.
You do not have to become emotionless about money.
You need to become more aware of how emotions influence your decisions.
The objective is not to make perfect financial decisions forever. It is to make increasingly better decisions over time.
Because changing your financial life often begins before your bank balance changes.
It begins when the way you think about money changes.
Educational disclaimer: This article provides general financial education and is not individualized financial, investment, psychological, tax or legal advice. Investments involve risk, including possible loss of principal. Financial products, regulations and consumer protections differ by country.