Full Post with 30 proven ways
Introduction
Depending entirely on one paycheck can leave your financial life vulnerable.
If your employer reduces hours, your industry slows down, a business closes, or an unexpected event prevents you from working, a household supported by only one source of income can suddenly face serious financial pressure.
Building multiple streams of income can help reduce that dependence.
Income diversification does not mean launching five businesses tomorrow. A better strategy is usually to strengthen your primary income first, establish financial stability, and then gradually add complementary income streams that match your skills, available time, capital and tolerance for risk.
Those streams might eventually include employment income, freelancing, consulting, investments, dividends, digital products, affiliate marketing, online courses, rental income, royalties or a small business.
The U.S. Small Business Administration provides extensive guidance for people considering entrepreneurship, while Investor.gov provides educational resources for those considering investment-based income.
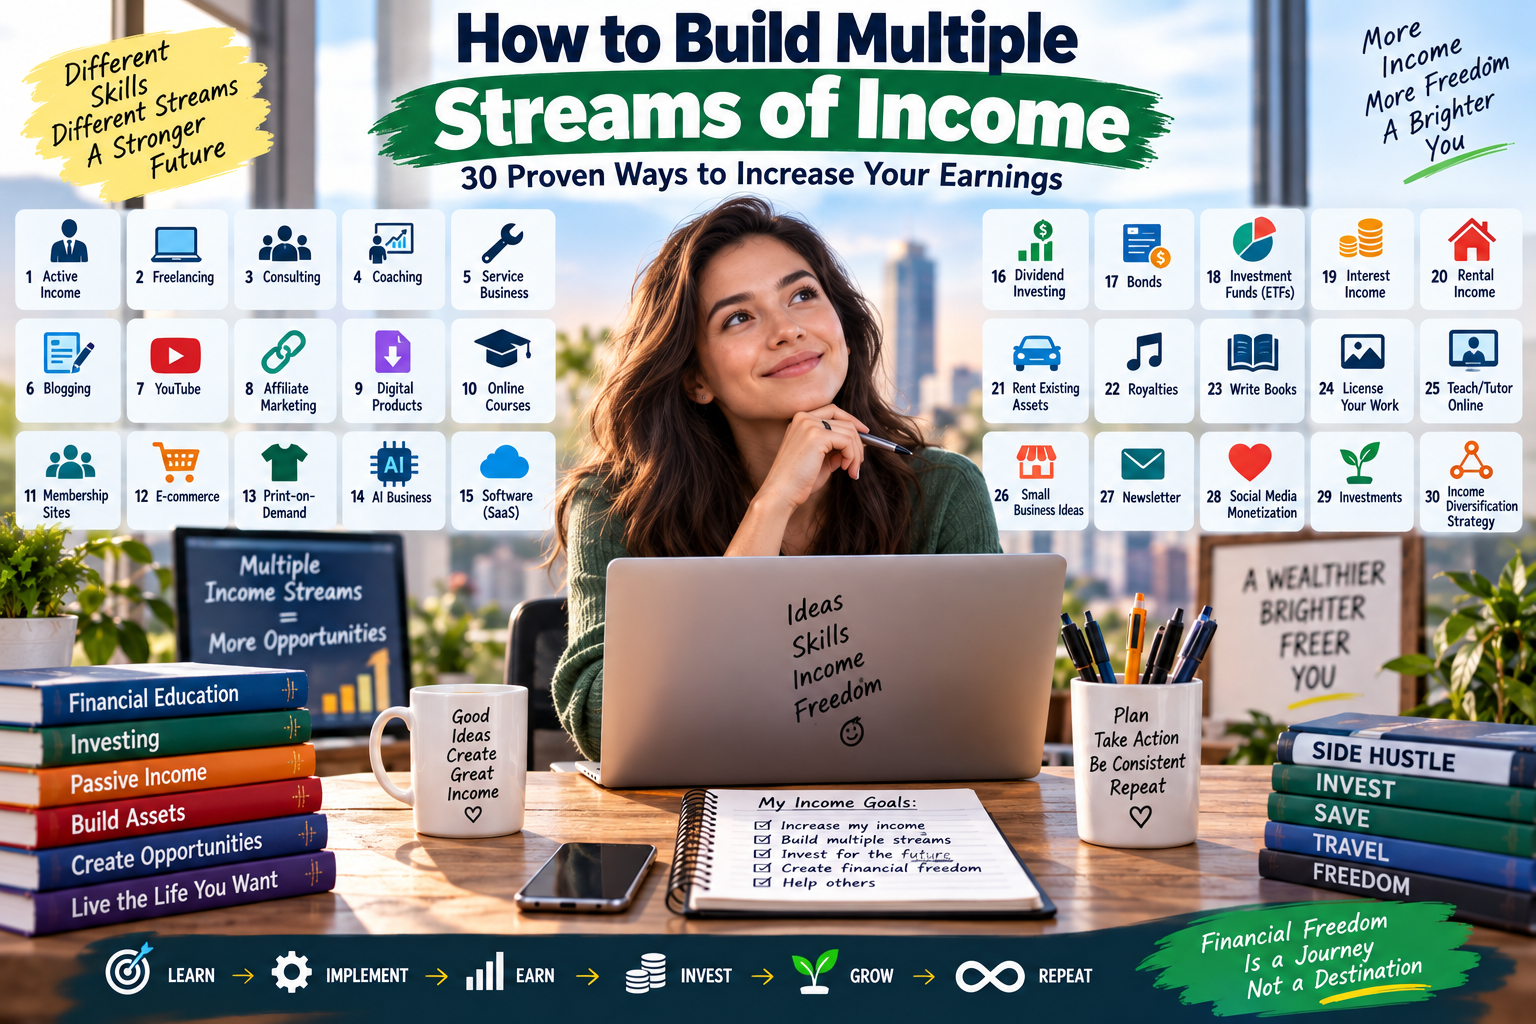
Here are 30 practical ways to increase your earnings and build a more diversified financial future.
Understanding the Four Major Types of Income
Before building multiple streams, understand where income can come from.
Active Income
Active income generally requires your direct labor.
Examples include:
- Salary
- Hourly wages
- Freelancing
- Consulting
- Coaching
- Contract work
Stop working, and much of this income usually stops.
Passive or Semi-Passive Income
Passive income is often misunderstood.
Most income described online as “passive” requires either money, substantial upfront work, ongoing management—or all three.
Examples can include rental income, royalties, digital products and certain business systems.
The objective isn’t necessarily “money for doing nothing.”
A more realistic goal is building assets or systems where income becomes less directly connected to every hour you personally work.
Portfolio Income
Portfolio income can come from financial assets.
Depending on the investment and tax system, examples may include:
- Dividends
- Interest
- Capital gains
- Bond income
- Investment-fund distributions
Investment income involves risk. Investor.gov explains the relationship between investment risk and potential return.
Digital Income
Digital technology has created another broad category of earning opportunities.
A person can potentially earn through:
- Websites
- YouTube
- Affiliate marketing
- Digital products
- Online courses
- E-commerce
- Software
- AI-assisted businesses
- Membership communities
Digital businesses can reach customers internationally, but they still require valuable products, marketing, customer acquisition and ongoing work.
1. Increase Your Primary Employment Income
Before creating complicated side businesses, consider increasing the income stream you already have.
A salary increase of $5,000 annually may be more valuable than spending hundreds of hours creating a side business that earns $500.
Ways to increase employment income can include:
Developing specialized skills → earning certifications → taking greater responsibility → negotiating compensation → changing positions → moving into higher-value roles.
Your primary career can provide the capital needed to build your other income streams.
2. Work Overtime or Additional Shifts
For hourly workers, additional shifts can be one of the fastest ways to increase income without creating a new business.
Unlike starting a company, there may be:
- No customer acquisition
- No advertising
- No inventory
- No website
- No startup capital
However, avoid making overtime your permanent financial strategy if it damages your health or leaves no time to develop higher-value opportunities.
Use some of the additional earnings to strengthen emergency savings, reduce expensive debt, develop skills or acquire productive assets.
3. Freelancing
Freelancing allows you to sell a skill directly to clients.
Examples include:
Graphic design, writing, bookkeeping, translation, programming, website development, video editing, virtual assistance, photography and social-media management.
Start with one skill and one clearly defined service.
Instead of saying:
“I do digital marketing.”
Offer something more specific:
“I create and manage email campaigns for small online stores.”
Specialization can make your offer easier for customers to understand.
4. Consulting
Consultants are generally paid for specialized knowledge, analysis and solutions.
If you have substantial expertise in areas such as business operations, finance, technology, marketing, human resources, logistics or another professional field, consulting can potentially become a high-value additional income stream.
The SBA’s business guide provides resources covering business planning, launching and managing a company.
Start by identifying:
Who has a problem I understand extremely well—and what measurable result can I help them achieve?
5. Coaching
Coaching differs somewhat from consulting.
A consultant often recommends solutions, while a coach commonly helps clients improve skills, behaviors, accountability or performance.
Possible areas include:
Career coaching, business coaching, fitness coaching, language coaching, productivity coaching and professional-skills coaching.
Only offer coaching in areas where you have legitimate knowledge or experience, and don’t present yourself as a licensed healthcare, legal or financial professional unless appropriately qualified.
6. Start a Service Business
Service businesses can be attractive because many require less startup capital than product businesses.
Possible examples include:
Cleaning, lawn care, mobile car detailing, photography, catering, tutoring, moving assistance, repair services, pet care and home maintenance.
The formula is straightforward:
Problem + Skill + Customer + Reliable Service = Potential Income
The SBA’s guide to starting a business explains important steps including market research, planning, funding and business registration.
7. Start a Blog
Blogging can become a digital business rather than simply an online diary.
A useful blog can generate income through:
Advertising, affiliate marketing, sponsorships, memberships, digital products, courses and services.
Choose a focused subject where readers actively search for solutions.
Examples might include:
Personal finance, technology, education, travel, career development, cooking, parenting, home improvement or entrepreneurship.
A successful blog usually requires substantial high-quality content, search visibility, audience trust and patience.
It is rarely instant passive income.
8. Affiliate Marketing
Affiliate marketing allows publishers or creators to receive compensation when people purchase products or complete qualifying actions through tracked affiliate links.
You could use affiliate marketing through:
Blogs, YouTube videos, newsletters, social-media content or niche websites.
However, recommendations should be genuinely useful rather than driven only by commission rates.
In the United States, the Federal Trade Commission’s endorsement guidance explains disclosure requirements that can apply when creators have material relationships with brands.
Always clearly disclose affiliate relationships where required.
9. Build a YouTube Channel
YouTube can potentially produce several income streams from one audience.
Depending on eligibility and location, creators can monetize through advertising, memberships, fan-funding features, Shopping and YouTube Premium revenue.
A channel can also support:
Affiliate marketing, sponsorships, courses, consulting, merchandise and your own digital products.
YouTube Partner Program requirements
The strongest approach is to create useful original content rather than simply producing large quantities of repetitive material. YouTube’s monetization policies emphasize original, valuable content and specifically address generic or repetitive content.
10. Create Digital Products
Digital products can be produced once and sold repeatedly, although marketing and customer support still require work.
Examples include:
eBooks, worksheets, templates, planners, spreadsheets, design assets, business documents, printable educational materials and digital guides.
The advantage is low marginal distribution cost.
If you create a $20 digital product, selling another copy doesn’t require manufacturing another physical item.
The challenge is creating something people genuinely need.
Start with the customer’s problem—not the product.
11. Sell Online Courses
If you possess valuable knowledge, you can package it into structured education.
Courses could teach:
Software, graphic design, languages, cooking, marketing, photography, entrepreneurship, professional skills or technical subjects.
A course becomes valuable when it helps someone move from:
Problem → Understanding → Action → Result
Avoid creating a course simply because online courses appear profitable.
Validate that people actually want the knowledge first.
12. Create a Paid Membership
Instead of selling a product once, you can build recurring revenue through membership.
Customers might pay monthly or annually for:
Premium articles, tutorials, research, educational resources, templates, community access, coaching sessions or specialized tools.
Recurring revenue can make business income more predictable, but customers must continue receiving enough value to justify renewing.
13. Start an E-Commerce Business
E-commerce allows you to sell physical products through the internet.
Possible models include:
Your own products, wholesale products, handmade goods, private-label products or carefully sourced merchandise.
Before buying substantial inventory, validate demand.
Research:
Customer demand
Competition
Product cost
Shipping
Returns
Advertising costs
Payment fees
Taxes
Profit margin
Revenue is not the same as profit.
A store producing $100,000 in sales can still lose money if expenses exceed its gross margin.
14. Print-on-Demand
Print-on-demand lets creators sell products that are manufactured after an order is placed.
Products can include:
T-shirts, mugs, posters, notebooks, tote bags and other merchandise.
This reduces the need to purchase large amounts of inventory in advance.
However, profit margins may be lower because manufacturing and fulfillment companies take part of the sale.
Success generally depends on original designs, strong niches and effective marketing.
15. Build an AI-Assisted Business
Artificial intelligence can help entrepreneurs produce work faster, automate repetitive tasks and create new services.
Possible AI-assisted businesses include:
Content research, marketing services, workflow automation, customer-support systems, data organization, educational tools, design assistance and specialized business applications.
But AI itself is not a business model.
Customers pay for results.
Instead of asking:
“How can I make money from AI?”
Ask:
“What expensive or time-consuming problem can I solve more efficiently using AI?”
Human review, originality, data privacy and quality control remain important.
16. Create a Software or Micro-SaaS Business
People with technical skills—or partnerships with developers—can build specialized software addressing narrow business problems.
For example:
Appointment systems, calculators, reporting tools, scheduling software, productivity tools or industry-specific applications.
A small software product serving 500 customers can sometimes be more manageable than trying to create the next global technology platform.
Start narrow.
Solve one problem extremely well.
17. Sell Templates and Professional Tools
Businesses and individuals repeatedly need tools that save time.
You might sell:
Budget templates, business plans, resume templates, invoice systems, social-media calendars, presentation templates or project-management tools.
The best templates eliminate work.
If your product saves someone three hours every month, its value becomes easier to demonstrate.
18. Earn Dividend Income
Some companies distribute part of their earnings to shareholders through dividends.
Dividend investing can therefore create portfolio income.
However, dividends are not guaranteed. Companies can reduce or eliminate them, and stock prices can fall.
Investor.gov provides educational resources on stocks and explains why diversification can be important.
Don’t choose an investment solely because its dividend yield looks high.
Evaluate the overall investment, risk, diversification, fees and suitability for your financial goals.
19. Invest in Bonds
Bonds generally involve lending money to a government, municipality or company in exchange for promised interest and repayment according to the bond’s terms.
They can potentially generate portfolio income but still involve risks.
Investor.gov provides an educational introduction to bonds.
Interest-rate risk, inflation, default risk and liquidity can all affect bond investments.
20. Use Interest-Bearing Savings for Short-Term Money
Not every dollar needs to be invested in stocks.
Emergency reserves and shorter-term savings may be better suited to appropriately protected, liquid accounts.
Interest earned on savings creates another small income stream while preserving access to funds.
In the United States, the FDIC explains how deposit insurance works at insured banks.
Readers elsewhere should research deposit-protection arrangements and regulated financial institutions in their own countries
21. Invest in Diversified Funds
Rather than attempting to select individual winning companies, some investors use diversified mutual funds or exchange-traded funds.
Investor.gov explains mutual funds and ETFs and provides educational information about diversification.
Diversification cannot eliminate market losses, but it can reduce the danger of having your entire portfolio depend on one investment.
22. Generate Rental Income
Real estate can potentially generate income when tenants pay rent.
But rental property is not automatically passive.
Owners may face:
Mortgage payments, taxes, insurance, vacancies, maintenance, repairs, management fees and legal responsibilities.
Before purchasing property, calculate expected net cash flow, not simply rent.
For example:
Rental Revenue − Operating Expenses − Financing Costs = Approximate Cash Flow
Property markets and landlord laws vary significantly by country and location, so local research is essential.
23. Rent Existing Assets
You may not need to purchase an entire investment property to generate rental income.
Depending on local regulations and platform availability, people sometimes rent:
A spare room, parking space, storage space, equipment, vehicles or specialized tools.
This can turn underused assets into productive assets.
Calculate insurance, maintenance, depreciation, taxes and platform fees before assuming the income represents profit.
24. Earn Royalties
Creators and intellectual-property owners can potentially receive royalties from:
Books, music, photography, illustrations, licensing agreements, patents or other intellectual property.
Royalties are attractive because one creative asset can potentially generate income repeatedly.
However, most creative works earn modest amounts, and meaningful royalty income often requires a substantial catalog, audience or commercially valuable intellectual property.
25. Write and Publish Books
A useful book can potentially generate several opportunities:
Book royalties → credibility → speaking → consulting → courses → related products
Authors can publish educational books, professional guides, fiction, children’s books or specialized reference material.
Focus on producing original work that serves a defined audience rather than mass-producing low-value titles.
One excellent book can become an asset supporting your brand for years.
26. License Your Creative Work
Photographers, designers, musicians, illustrators and other creators may be able to license their work.
Instead of permanently selling ownership, licensing can allow customers to purchase specified usage rights.
One asset may potentially generate multiple licensing transactions.
Understand copyright and licensing agreements before granting rights.
For U.S. creators, the U.S. Copyright Office provides official copyright information.
27. Build a Newsletter
A focused newsletter can become an audience asset.
Possible monetization methods include:
Sponsorships, premium subscriptions, affiliate partnerships, consulting, courses and digital products.
Successful newsletters usually serve a clearly defined audience.
Instead of:
“Weekly business news.”
Consider something more targeted:
“Weekly funding opportunities and digital marketing strategies. Specific audiences can be commercially valuable even when they aren’t enormous.
28. Teach or Tutor Online
Knowledge can become income without creating a full course.
You might tutor:
Languages, mathematics, science, writing, music, software, professional certifications or academic subjects.
Tutoring begins as active income.
Over time, however, you could transform repeated lessons into:
Worksheets → recorded lessons → courses → books → memberships
That creates a path from active income toward scalable digital income
29. Buy or Build a Small Business
Owning a profitable small business can become a major income stream.
Possible businesses range from:
Cleaning companies and bakeries to online stores, repair businesses, digital agencies and specialized local services.
But business ownership carries significant risk.
Before investing, understand:
Revenue, expenses, cash flow, competition, customer concentration, liabilities and required working capital.
The SBA business guide offers extensive resources for planning, launching and managing businesses in the United States. Entrepreneurs elsewhere should also consult their country’s business-registration, taxation and regulatory authorities.
30. Combine Several Income Streams Into One Financial Ecosystem
The most powerful strategy may not be having 30 unrelated sources of income.
It can be building several connected income streams around one skill, audience or asset.
Imagine a personal-finance educator.
They could build:
Blog → YouTube → Affiliate Marketing → eBook → Online Course → Membership → Consulting
One article attracts a reader.
That reader watches a video.
The video introduces an eBook.
The eBook promotes a course.
The course leads some customers to consulting.
Instead of building six unrelated businesses, you are creating one ecosystem with multiple ways to earn.
How to Build Your Income Diversification Strategy
The objective is not to collect income streams like trophies.
Each new source creates complexity.
A stronger approach is:
Stage 1 — Stabilize: Strengthen your primary income and create emergency savings.
Stage 2 — Expand: Develop one marketable skill that can generate additional active income.
Stage 3 — Validate: Test one side business without risking essential household money.
Stage 4 — Systemize: Improve processes so the business requires less of your time per dollar earned.
Stage 5 — Invest: Direct part of your surplus income toward diversified long-term investments appropriate to your circumstances.
Stage 6 — Scale: Expand the income sources demonstrating genuine demand and profitability.
Stage 7 — Protect: Use appropriate insurance, cash reserves, diversification, cybersecurity, contracts and professional tax/legal guidance.
An Example Multiple-Income Portfolio
Consider Maya, a fictional 32-year-old marketing professional.
Her financial structure might eventually look like this:
Primary job: $60,000 annually
Freelancing: $8,000
Digital products: $3,000
Affiliate marketing: $1,500
YouTube: $2,000
Investment distributions: $1,000
Total hypothetical annual income:
$75,500
Her additional streams generate $15,500 beyond employment.
More importantly, the structure doesn’t depend entirely on one source.
If freelance work slows, her employment continues.
If digital-product sales fall, investments remain.
If she eventually loses her job, the smaller streams won’t necessarily replace her salary—but they can provide a financial bridge while she finds new employment.
That is one of the real benefits of diversification.
Active Income vs. Scalable Income
Early in your wealth-building journey, active income is extremely valuable.
It produces capital.
But active income has a limitation:
Your time.
You have only 24 hours each day.
If you earn $30 per hour and can sell only 30 additional hours per month, your additional earning capacity is limited.
Scalable assets change the equation.
A digital course could potentially serve 10 students or 10,000.
A YouTube video can potentially be viewed repeatedly.
A book can potentially sell for years.
A software product can potentially serve hundreds of customers simultaneously.
An investment portfolio can potentially generate returns without your performing an hourly service.
This does not mean scalable income is easy.
It means the relationship between time and revenue can eventually become less direct.
Avoid the Multiple-Income Trap
Diversification is beneficial, but excessive diversification can destroy focus.
Imagine simultaneously attempting to:
Start YouTube + build a blog + launch e-commerce + freelance + trade stocks + manage rental property + create courses + start consulting.
You may become extremely busy while making very little money.
A better rule is:
Build one. Stabilize it. Systemize it. Then add another.
Your first additional stream may take a year to become meaningful.
That’s fine.
The objective is not overnight income.
The objective is durable income.
Reinvest Your Additional Income
The purpose of earning more should not simply be spending more.
When a new income stream becomes profitable, consider dividing the surplus among:
Emergency savings
Debt reduction
Business reinvestment
Long-term investments
Retirement
Education
Personal enjoyment
This is how income diversification can become wealth diversification.
You move from:
Working for money
to:
Using earned money to acquire productive assets
and eventually toward:
Assets producing additional income.
Protect Yourself From Income Scams
Whenever people search for ways to make money, scammers appear.
Be skeptical of opportunities promising:
Guaranteed passive income
Guaranteed investment returns
Thousands per week with no experience
Secret AI money systems
Risk-free cryptocurrency profits
Pay-to-unlock employment
Instant business success
Investor.gov provides guidance on protecting your investments from fraud.
Legitimate income usually requires at least one of four things:
Skill, work, capital or risk.
Often it requires several.
Your 12-Month Multiple-Income Roadmap
Months 1–3: Build the Foundation
Track spending, establish emergency savings, examine expensive debt and identify your strongest marketable skill.
Months 4–6: Create Your Second Stream
Choose one opportunity.
Freelancing may be appropriate if you have skills but little capital.
A service business may work if you prefer local customers.
Content creation may work if you possess knowledge and patience.
Months 7–9: Improve the System
Study which activities actually produce revenue.
Eliminate tasks that consume time without producing results.
Improve pricing, marketing, customer experience and operations.
Months 10–12: Reinvest
Direct part of the new income toward productive assets.
Then determine whether your existing stream should be expanded or whether you have enough capacity to add another.
The Multiple-Income Wealth Formula
A sustainable long-term strategy can look like this:
Learn Valuable Skills → Increase Active Income → Save the Surplus → Build a Second Income Stream → Invest → Acquire Productive Assets → Reinvest Profits → Diversify → Protect → Repeat
You don’t need 30 streams.
You may eventually need only three or four strong ones.
For example:
Employment + Business + Investments + Digital Assets
could be considerably stronger than ten tiny projects that never become profitable.
Conclusion
Building multiple streams of income is not about becoming rich overnight.
It is about reducing financial dependence, increasing earning capacity and gradually building assets that can support your financial future.
Start with your strongest resource.
If you have skills but little money, consider freelancing, consulting or services.
If you have specialized knowledge, consider coaching, courses, books or digital products.
If you have an audience, consider affiliate marketing, YouTube, memberships or sponsorships.
If you have capital, learn about diversified investments and other productive assets.
If you have entrepreneurial experience, consider building or acquiring a business.
But don’t try everything simultaneously.
Build one income stream.
Make it work.
Improve it.
Systemize it.
Reinvest the profits.
Then build the next one.
Over time, your financial structure can evolve from:
One job → Job + Side Income → Business + Investments → Multiple Assets + Multiple Income Streams
The ultimate objective isn’t simply having more money coming in.
It is building a financial life where one lost paycheck, one failed client or one struggling business does not determine your entire future.