Tag: #SavingMoney

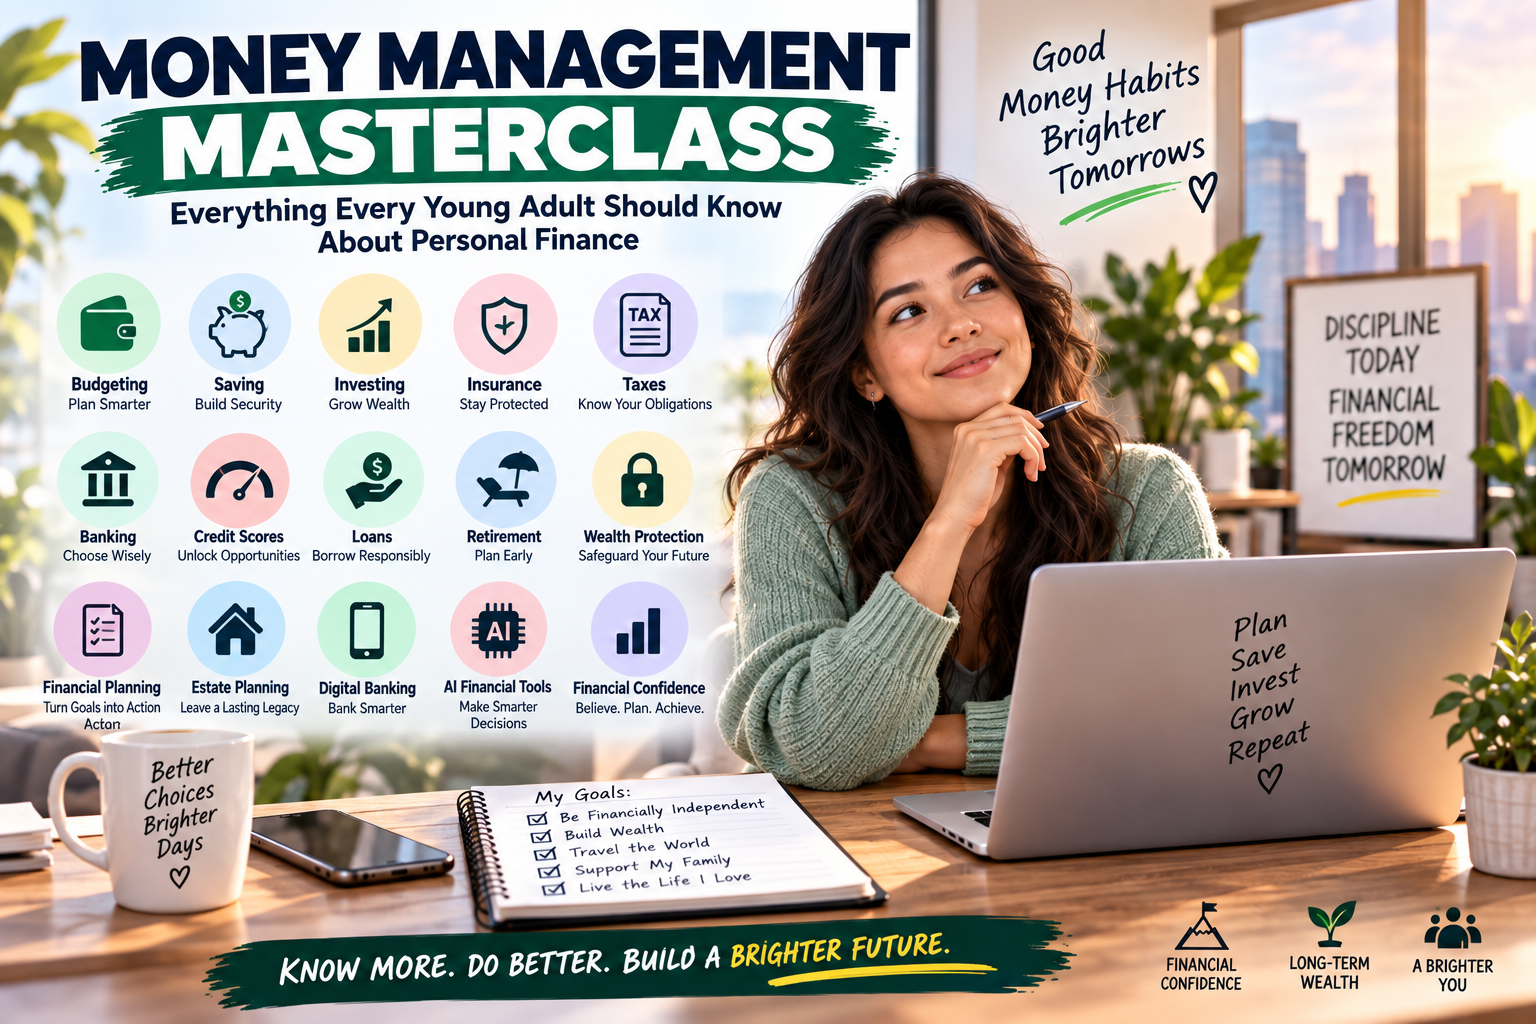
  • Money Management Masterclass: Everything Every Young Adult Should Know About Personal Finance

    Money Management Masterclass: Everything Every Young Adult Should Know About Personal Finance

    The master class every one can depend on.

    Introduction

    Managing money well is one of the most valuable life skills a young adult can develop.

    Yet many people enter adulthood knowing how to earn a paycheck but knowing very little about budgeting, credit, investing, insurance, taxes, banking, retirement or protecting the wealth they eventually build.

    That knowledge gap can become expensive.

    A person can earn a good salary and still live paycheck to paycheck. Another person earning less may gradually create financial security because they understand how to control expenses, save consistently, avoid destructive debt and invest for long-term goals.

    Personal finance is therefore not simply about how much money you earn.

    It is about what you do with the money that passes through your hands.

    The Consumer Financial Protection Bureau provides resources covering everyday financial decisions, Investor.gov provides investing education, and the FDIC Money Smart program offers financial education covering banking, saving, credit and other essential topics.

    This masterclass explains the fundamental personal-finance skills every young adult should understand—and how those skills fit together to create long-term financial confidence.

    1. Learn Where Your Money Actually Goes

    Before investing, buying property or trying to become wealthy, understand your current financial position.

    Start with four numbers:

    Income — Expenses — Assets — Liabilities

    Income is money coming in.

    Expenses are money going out.

    Assets are things you own that have financial value.

    Liabilities are financial obligations you owe.

    Your net worth can then be summarized as:

    Net Worth = Assets − Liabilities

    Someone earning $100,000 annually while carrying excessive debt and owning few assets may be financially weaker than someone earning $60,000 who consistently saves, invests and keeps debt under control.

    The CFPB’s financial well-being resources provide tools for thinking about overall financial health.

    Your first goal should therefore be understanding your numbers—not comparing your salary with everyone else’s.

    2. Budgeting: Give Every Dollar a Purpose

    A budget is simply a plan for your income.

    It tells you how much can reasonably go toward:

    Housing
    Food
    Transportation
    Utilities
    Debt
    Insurance
    Savings
    Investments
    Entertainment
    Other goals

    The CFPB budgeting resources provide practical tools for managing cash flow and expenses.

    Several budgeting approaches can work.

    The 50/30/20 Framework

    A commonly discussed starting framework divides after-tax income approximately into:

    50% needs
    30% wants
    20% savings and debt repayment

    Your circumstances may require different percentages.

    Someone living in a high-cost city may spend more than 50% on necessities, while someone living with family may be able to save substantially more.

    Zero-Based Budgeting

    With zero-based budgeting, you assign a purpose to all available income.

    That does not mean spending everything.

    Saving and investing are also purposes.

    Pay Yourself First

    Instead of saving whatever remains after spending, transfer money toward financial goals soon after receiving income.

    The principle is:

    Income → Save/Invest → Expenses

    rather than:

    Income → Expenses → Maybe Save

    3. Saving: Build Your Financial Safety Net

    Savings create stability.

    Without savings, a relatively small emergency can become debt.

    A car repair, medical bill, temporary loss of income or urgent trip may otherwise end up on a credit card or expensive loan.

    The CFPB’s emergency-fund guide explains how dedicated emergency savings can help people recover from unexpected expenses.

    Start small if necessary.

    Your progression might look like:

    $500 → $1,000 → One month of essential expenses → Three months → Several months

    The appropriate amount depends on job stability, family responsibilities, insurance coverage and other circumstances.

    Keep emergency money somewhere safe and reasonably accessible rather than exposing essential reserves to unnecessary investment risk.

    4. Banking: Understand Where You Keep Your Money

    Young adults should understand the difference between common financial accounts.

    Checking Accounts

    Generally designed for frequent transactions such as bills, purchases and direct deposits.

    Savings Accounts

    Designed primarily for holding savings and potentially earning interest.

    Certificates or Fixed Deposits

    Depending on the country and institution, these can offer interest in exchange for leaving money deposited for a specified period.

    For U.S. consumers, the FDIC’s deposit insurance resources explain coverage at FDIC-insured banks.

    The National Credit Union Administration provides information about federal share insurance at eligible U.S. credit unions.

    Outside the United States, check your country’s banking regulator and deposit-protection system.

    Never assume every financial app automatically provides the same protections as a regulated bank account.

    5. Digital Banking: Convenience Requires Security

    Banking has moved increasingly onto smartphones.

    People can now:

    Deposit checks
    Transfer money
    Pay bills
    Monitor accounts
    Send money
    Freeze cards
    Receive alerts

    This convenience creates new risks.

    Protect accounts with:

    Strong unique passwords
    Multi-factor authentication
    Transaction alerts
    Secure devices
    Regular account monitoring

    The Federal Trade Commission’s consumer security guidance provides information about scams and fraud, while the Cybersecurity and Infrastructure Security Agency provides practical cybersecurity recommendations.

    Never provide passwords, verification codes or banking credentials to someone simply because they claim to represent your bank.

    6. Credit Scores: Understand Your Financial Reputation

    In countries using consumer credit scoring, your credit history can influence access to loans and the rates offered.

    In the United States, credit scores commonly consider factors connected to payment history, debt and credit usage.

    Young adults should focus on fundamentals:

    Pay bills on time.
    Avoid excessive balances.
    Don’t apply unnecessarily for numerous accounts.
    Review credit reports for errors.

    The Consumer Financial Protection Bureau provides extensive information about credit reports and scores.

    U.S. consumers can obtain federally authorized free credit reports through AnnualCreditReport.com.

    Your credit score is important where applicable—but it is not the same thing as wealth.

    Someone can have excellent credit and very little net worth.

    7. Credit Cards: Use Them as Tools, Not Extra Income

    A credit-card limit is not money you own.

    It is borrowing capacity.

    Credit cards can be useful for payments and credit history, but carrying balances can become expensive.

    The CFPB credit-card resources explain card costs and consumer rights.

    Before applying, understand:

    APR
    Annual fees
    Late fees
    Grace periods
    Rewards conditions

    When possible, pay the statement balance in full and on time.

    Never spend simply to earn points.

    Spending $1,000 unnecessarily to earn $20 in rewards does not make you $20 richer.

    It makes you approximately $980 poorer.

    8. Loans: Understand the Real Cost of Borrowing

    Loans can help finance education, housing, transportation or business opportunities.

    But borrowing always deserves careful analysis.

    Before accepting a loan, understand:

    Principal
    Interest rate
    APR where applicable
    Monthly payment
    Loan term
    Fees
    Total repayment

    Do not evaluate affordability based only on the monthly payment.

    A longer loan can reduce the payment while increasing the total amount paid.

    The CFPB consumer loan resources cover several borrowing categories, including mortgages, auto loans, student loans and credit cards.

    9. Student Loans: Borrow With Your Future Income in Mind

    Education can improve earning capacity, but excessive education debt can restrict financial flexibility for years.

    Before borrowing, compare the expected cost with:

    Likely career opportunities
    Expected starting salary
    Alternative programs
    Scholarships and grants
    Less expensive institutions

    U.S. students can use Federal Student Aid for official federal student-aid information and its Loan Simulator for repayment planning.

    Avoid assuming that every degree automatically produces enough income to comfortably repay any amount borrowed.

    10. Taxes: Understand the Money Taken From Your Income

    Taxes affect your paycheck, investments, business income and sometimes your estate.

    Young adults should understand at least:

    Gross income
    Taxable income
    Withholding
    Tax deductions
    Tax credits
    Payroll taxes
    Investment taxes
    Self-employment taxes

    U.S. taxpayers can learn directly from the Internal Revenue Service and access filing information through the IRS’s File Your Taxes resources.

    Tax systems vary enormously worldwide.

    If you freelance, operate a business or earn money online, don’t assume that income becomes tax-free simply because an employer did not withhold taxes.

    Learn the requirements in your jurisdiction.

    11. Build an Emergency Fund Before Taking Major Investment Risks

    Investing is important.

    But investing without emergency savings can create problems.

    Imagine investing every spare dollar and then suddenly needing $2,000 for an emergency.

    You may have to sell investments during a market decline.

    Emergency savings give long-term investments time to remain invested.

    The CFPB emergency-fund guide provides a useful starting point.

    Think of emergency savings as the foundation underneath your investment portfolio.

    12. Investing: Make Your Money Work Toward Future Goals

    Saving protects short-term stability.

    Investing is generally intended to pursue longer-term growth while accepting risk.

    Common investment categories can include:

    Stocks
    Bonds
    Mutual funds
    Exchange-traded funds
    Real estate
    Other investment assets

    Investor.gov provides beginner resources explaining investment products.

    Every investment carries risk.

    The objective isn’t to eliminate risk completely—it is to understand and manage it.

    13. Understand Diversification

    Putting your entire financial future into one company, industry or speculative asset creates concentration risk.

    Diversification spreads investments across different assets.

    Investor.gov explains diversification and why it can reduce certain investment risks.

    Diversification cannot guarantee profits or prevent all losses.

    But it can help prevent one failed investment from destroying an entire portfolio.

    14. Understand Compound Growth

    Young adults have something extremely valuable:

    Time.

    Suppose you invest $200 monthly for 40 years.

    Your direct contributions would total:

    $96,000

    If those investments generate positive returns over time, the eventual portfolio could become substantially larger because earlier returns may generate additional returns.

    Experiment with different assumptions using the Investor.gov Compound Interest Calculator.

    Starting small and early can be more powerful than waiting years for the perfect salary.

    15. Retirement Planning Should Begin While You Are Young

    Retirement may seem decades away.

    That distance is an advantage.

    Money invested at 25 potentially has 40 years to grow before age 65.

    Money first invested at 55 has only ten.

    Investor.gov provides a Retirement Toolkit, while FINRA’s retirement resources explain additional planning considerations.

    Learn about pensions, employer plans, government programs and tax-advantaged retirement accounts available in your country.

    If an employer offers matching contributions, understand how the program works and whether participating fits your circumstances.

    16. Insurance: Protect Yourself Against Financial Catastrophe

    Insurance is part of financial planning because some losses are too large to comfortably pay from savings.

    Depending on your situation, relevant coverage might include:

    Health insurance
    Auto insurance
    Renters insurance
    Homeowners insurance
    Disability insurance
    Life insurance

    Life insurance becomes especially important to consider when other people financially depend on your income.

    Insurance requirements and products vary considerably by country.

    The purpose isn’t to insure every inconvenience.

    It is primarily to protect against risks capable of causing major financial damage.

    17. Protect Your Ability to Earn Income

    Your income is one of your largest financial assets.

    Imagine earning $50,000 annually for the next 30 years.

    That represents $1.5 million in gross future earnings before raises.

    Your ability to work therefore has enormous economic value.

    This is why health, career development, emergency savings and appropriate disability protection can be important parts of financial planning.

    Wealth protection starts long before you become wealthy.

    18. Avoid Lifestyle Inflation

    When income rises, spending often rises automatically.

    New salary.

    New car.

    More expensive apartment.

    More expensive restaurants.

    More subscriptions.

    Suddenly, someone earning twice as much still has nothing left at the end of the month.

    Instead, when receiving a raise, consider dividing it:

    Some for lifestyle improvement
    Some for saving
    Some for investing
    Some for debt reduction

    Allow your lifestyle to improve—but let your net worth improve too.

    19. Build Multiple Sources of Income

    One income stream creates dependence.

    Over time, consider building additional sources such as:

    Freelancing
    Consulting
    Business income
    Digital products
    Rental income
    Royalties
    Portfolio income

    Don’t build everything simultaneously.

    Develop one additional stream, stabilize it and then consider another.

    The SBA Business Guide provides useful information for people considering entrepreneurship.

    20. Protect Yourself From Financial Fraud

    Young adults increasingly encounter investment opportunities through social media.

    Be suspicious of:

    Guaranteed returns
    Secret investments
    Risk-free profits
    Urgent opportunities
    Celebrity investment claims
    Unsolicited messages
    Requests for cryptocurrency transfers

    Investor.gov provides extensive resources on investment fraud and specifically addresses internet and social-media fraud.

    For U.S. investment professionals, FINRA BrokerCheck can help research brokerage firms and professionals.

    Never confuse confidence with credibility.

    21. AI Financial Tools: Useful Assistant, Dangerous Authority

    Artificial intelligence can help with everyday financial organization.

    AI tools may help users:

    Categorize expenses
    Create budget scenarios
    Compare financial goals
    Explain terminology
    Analyze spending patterns
    Model savings scenarios
    Organize financial information

    But AI output can be inaccurate.

    Never blindly rely on an AI system for decisions involving investments, taxes, insurance, loans or legal obligations.

    Verify important information through regulators, financial institutions and appropriately qualified professionals.

    Also protect your privacy.

    Avoid unnecessarily entering:

    Bank passwords
    Credit-card numbers
    Social Security numbers
    Tax identification numbers
    Authentication codes
    Private financial credentials

    into general-purpose AI tools.

    Use AI to improve financial understanding and organization—not as an unquestionable financial authority.

    22. Financial Planning: Connect Today’s Money With Tomorrow’s Goals

    Financial planning asks:

    Where am I now?
    Where do I want to go?
    What must happen between those two points?

    Create goals across different time horizons.

    Short Term

    Emergency fund, debt reduction, vehicle repair, travel.

    Medium Term

    Education, home deposit, business capital.

    Long Term

    Retirement, financial independence, property, legacy.

    Assign each important goal:

    Amount + Deadline + Monthly Contribution

    A dream becomes much more actionable when it becomes measurable.

    23. Calculate and Track Your Net Worth

    Once or twice a year, calculate:

    Assets − Liabilities = Net Worth

    Assets might include:

    Cash
    Savings
    Investments
    Retirement accounts
    Business interests
    Property

    Liabilities might include:

    Credit-card debt
    Student loans
    Auto loans
    Personal loans
    Mortgages

    Don’t panic if your net worth is negative when you are young.

    The important question is:

    Is it improving?

    Tracking net worth can shift your attention away from appearing wealthy and toward actually building wealth.

    24. Wealth Protection: Building Money Is Only Half the Job

    As your financial position improves, protection becomes increasingly important.

    Your wealth-protection system may eventually include:

    Emergency reserves
    Diversified investments
    Appropriate insurance
    Cybersecurity
    Fraud prevention
    Tax planning
    Estate planning
    Responsible debt management

    Someone who spends decades building assets but never protects them can lose substantial wealth through one preventable event.

    25. Estate Planning Is Not Only for Millionaires

    Estate planning answers important questions:

    What happens to my assets when I die?
    Who handles my affairs?
    Who receives my property?
    Who makes certain decisions if I become unable to do so?

    Depending on your country, estate planning may involve:

    A will
    Beneficiary designations
    Powers of attorney
    Healthcare directives
    Trusts in appropriate circumstances

    For U.S. consumers, general estate and tax information is available from the IRS.

    Estate law varies substantially by jurisdiction, so important documents should be prepared according to local law, often with professional legal guidance.

    Young adults with children, spouses, property or other dependents have especially strong reasons to consider planning.

    26. Keep Beneficiaries and Important Documents Updated

    Financial planning isn’t finished when you sign documents.

    Major life events can change your intentions:

    Marriage
    Divorce
    Children
    Home purchase
    Business ownership
    Death of a beneficiary

    Periodically review relevant account beneficiaries and estate-planning documents.

    Keep important records organized and ensure an appropriate trusted person knows how necessary information can be located in an emergency.

    Do not casually share passwords

    27. Build Financial Confidence Through Education

    Financial confidence does not mean knowing everything.

    It means developing enough knowledge to ask better questions and make increasingly informed decisions.

    Start with reliable sources.

    Useful educational resources include:

    Consumer Financial Protection Bureau — budgeting, credit, debt, mortgages and consumer finance.

    Investor.gov — investing, fraud prevention and calculators.

    FINRA Investor Education — investing and financial-market education.

    FDIC Money Smart — financial education and banking.

    Internal Revenue Service — U.S. federal tax information.

    USA.gov Money and Credit — official U.S. financial resources.

    Readers outside the United States should combine these general educational concepts with guidance from their country’s central bank, securities regulator, tax authority and consumer-protection agencies.

    28. Create Your Personal Financial System

    Good financial management should eventually become systematic.

    A simple system might be:

    Paycheck arrives

    ↓

    Bills funded

    ↓

    Savings transferred automatically

    ↓

    Retirement/investment contribution

    ↓

    Debt repayment

    ↓

    Discretionary spending

    ↓

    Monthly review

    Automation reduces the number of financial decisions you need to make repeatedly.

    The goal is to make good financial behavior easier.

    29. Conduct a Monthly Money Meeting

    Once each month, spend 20–30 minutes reviewing:

    Income
    Expenses
    Debt balances
    Savings
    Investments
    Credit
    Upcoming bills
    Financial goals

    Ask yourself:

    What improved this month?

    What went wrong?

    What is my most important financial action next month?

    You don’t need to check your investment portfolio ten times every day.

    But you should know the direction of your financial life.

    30. Follow the Personal Finance Wealth-Building Roadmap

    Personal finance can appear complicated because there are thousands of products, strategies and opinions.

    The fundamental roadmap is much simpler:

    Learn → Earn → Budget → Save → Manage Debt → Protect → Invest → Increase Income → Build Assets → Plan Retirement → Protect Wealth → Plan Your Estate

    You do not have to complete every stage immediately.

    A 20-year-old student and a 38-year-old parent should not necessarily have identical priorities.

    Your strategy should evolve with your life.

    A Practical Personal Finance Checklist for Young Adults

    Use this as your basic money-management framework:

    1. Know your monthly income.

    2. Track where your money goes.

    3. Create a realistic budget.

    4. Build an emergency fund.

    5. Pay bills on time.

    6. Understand your credit where applicable.

    7. Avoid destructive high-interest debt.

    8. Understand every loan before signing.

    9. Learn your tax obligations.

    10. Protect your banking information.

    11. Obtain appropriate insurance.

    12. Start learning about investing.

    13. Diversify long-term investments appropriately.

    14. Begin retirement planning early.

    15. Increase your earning ability.

    16. Avoid lifestyle inflation.

    17. Develop additional income streams gradually.

    18. Monitor your net worth.

    19. Protect yourself from scams.

    20. Create measurable financial goals.

    21. Use AI financial tools cautiously.

    22. Protect the assets you build.

    23. Organize important financial documents.

    24. Consider estate planning appropriate to your circumstances.

    25. Review your financial plan every year.

    Conclusion

    Mastering personal finance is not about memorizing hundreds of financial terms.

    It is about developing a system.

    Earn money intentionally.
    Budget it carefully.
    Save consistently.
    Borrow cautiously.
    Protect yourself appropriately.
    Invest intelligently.
    Plan for retirement early.
    Build productive assets.
    Protect your wealth.
    Plan for the people you care about.

    You will make financial mistakes.

    Almost everyone does.

    The objective is to make fewer costly mistakes, recognize them earlier and continuously improve your financial decisions.

    You do not need to become wealthy before learning money management.

    In reality, learning how to manage money before you have significant wealth may be one of the most important steps toward building it.

    Start with the money you have today.

    Create your first budget.

    Save your first emergency dollar.

    Learn how your bank account works.

    Understand your credit.

    Make your first informed investment when you are financially prepared.

    Plan for retirement even when it feels far away.

    Then keep learning.

    Financial confidence is rarely created by one brilliant decision.

    It is built through hundreds of small, informed financial decisions repeated over many years.

    And the earlier you begin making those decisions, the more time you give yourself to build the financial future you want.
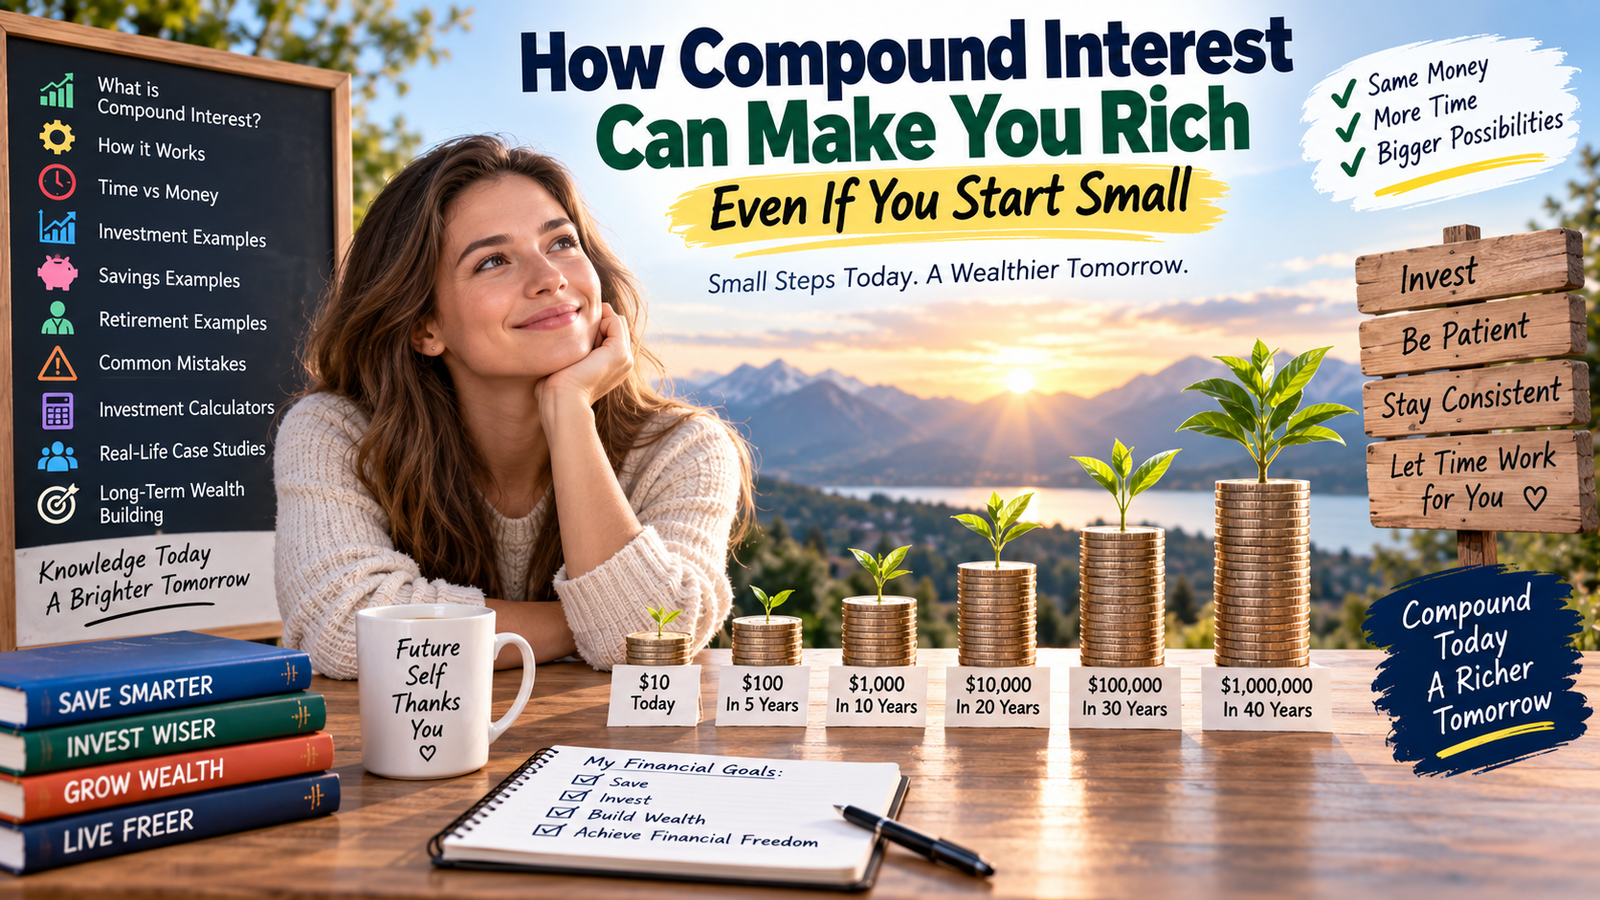
  • How Compound Interest Can Make You Rich Even If You Start Small

    How Compound Interest Can Make You Rich Even If You Start Small

    How Small Savings and Investments Can Grow Into Significant Long-Term Wealth Through Time and Consistency

    Introduction

    You Don’t Need to Start Rich to Build Wealth

    One of the biggest misconceptions about wealth building is that you need a large amount of money before investing becomes worthwhile.

    You don’t.

    Starting with $10, $50, $100 or $500 may seem insignificant when compared with the large investment portfolios discussed in financial media. But when money is invested consistently and allowed to grow over many years, something powerful can happen: compound growth.

    Compound interest means you can potentially earn returns not only on the money you originally saved or invested, but also on previous interest or investment returns.

    This creates a snowball effect.

    At first, progress can appear frustratingly slow. As time passes, however, the growth generated by your accumulated money can become increasingly important.

    The U.S. Securities and Exchange Commission’s Investor.gov provides a compound-interest calculator that demonstrates how savings can potentially grow over time, while the Consumer Financial Protection Bureau provides educational resources for establishing stronger saving habits.

    The lesson is simple:

    You don’t necessarily need a large starting amount. You need consistency, reasonable returns, and—most importantly—time.

    What Is Compound Interest?

    Compound interest is interest calculated on your original principal plus previously accumulated interest.

    Imagine depositing $1,000 into an account earning a hypothetical 5% annually.

    After the first year:

    $1,000 × 5% = $50

    Your balance becomes:

    $1,050

    If the money remains in the account, the second year’s interest is calculated on $1,050 rather than only the original $1,000.

    At 5%, that would produce:

    $52.50

    Your balance becomes:

    $1,102.50

    The extra $2.50 may appear insignificant.

    But over many compounding periods, the difference can become much larger.

    Investor.gov explains the concept through its educational material on compound interest, and its compound interest calculator allows investors to test different hypothetical scenarios.

    The fundamental principle is:

    Your money can potentially begin earning money on money it previously earned.

    How Does Compound Interest Work?

    A simplified annual compounding formula is:

    Future Value = Principal × (1 + Rate)^Time

    Suppose you invest $5,000 and hypothetically earn 7% annually for 20 years without adding additional money.

    The calculation would be approximately:

    $5,000 × (1.07)^20 = $19,348

    Your original $5,000 would have potentially grown to approximately $19,348.

    That does not mean every investment will return 7%. Investment returns fluctuate and can be negative. The example simply demonstrates the mathematics of compounding.

    The Investor.gov compound-interest calculator lets readers experiment with principal, contributions, interest rates and time, while FINRA’s investing resources explain important concepts investors should understand before putting money at risk.

    Time vs. Money: Why Starting Early Can Matter More Than Starting Big

    One of the most important lessons about compound growth is that time can compensate for a relatively small beginning.

    Consider two hypothetical investors.

    Investor A: Starts at Age 20

    Investor A invests $200 every month from age 20 until age 60.

    Total contributions:

    $200 × 12 × 40 = $96,000

    At a hypothetical 7% annual return compounded monthly, the portfolio could grow to roughly $525,000.

    Investor B: Starts at Age 40

    Investor B also invests $200 monthly but starts at age 40 and continues until 60.

    Total contributions:

    $200 × 12 × 20 = $48,000

    At the same hypothetical return, the portfolio could grow to roughly $104,000.

    The difference isn’t simply because Investor A contributed more.

    Investor A’s earliest contributions had decades longer to potentially compound.

    This illustrates why the Investor.gov saving and investing resources encourage understanding long-term investing, while the FINRA investor education center provides resources for making informed investment decisions.

    Starting early can be more powerful than waiting until you have a large amount of money.

    Small Monthly Investments Can Become Significant

    Suppose someone begins investing $100 per month at age 25.

    Assume, purely for illustration, an average annual return of 7%.

    If that person continues for 40 years, their personal contributions total:

    $48,000

    Yet the hypothetical investment balance could eventually reach approximately $262,000.

    Increase the contribution to $300 monthly under the same hypothetical assumptions, and the eventual balance could approach approximately $787,000.

    Again, these are illustrations—not guaranteed investment outcomes.

    Actual results depend on market performance, investment fees, taxes, contribution timing and other factors.

    The lesson is not that 7% is guaranteed.

    The lesson is that:

    Small Amount + Consistency + Return + Time = Potentially Significant Growth

    Compound Growth in a Savings Account

    Compounding does not apply only to stock-market investments.

    Interest-bearing savings accounts can also compound.

    Suppose you deposit $10,000 into a savings account earning a hypothetical 4% annually and leave the interest in the account.

    After one year, approximately:

    $10,400

    After five years:

    $12,167

    After ten years:

    $14,802

    The exact result depends on the account’s rate and compounding frequency.

    Savings accounts generally offer lower expected returns than riskier investments, but they can be appropriate for emergency funds and shorter-term financial goals where protecting principal and maintaining liquidity are priorities.

    The CFPB savings resources provide information about developing savings strategies, while U.S. readers can learn about insured bank deposits from the Federal Deposit Insurance Corporation.

    Readers outside the United States should check the deposit-protection rules and regulated financial institutions in their own countries.

    Compound Growth and Retirement

    etirement planning is one of the clearest examples of why compounding matters.

    Imagine a 25-year-old contributes $250 monthly toward long-term retirement investments.

    At a hypothetical 7% annual return, continuing until age 65 could potentially produce approximately $656,000.

    Personal contributions would total only:

    $250 × 12 × 40 = $120,000

    Much of the hypothetical difference would come from investment growth and compounding.

    A person who waits until 45 has only 20 years before reaching 65. Achieving a similar result would require dramatically larger contributions or substantially different investment outcomes.

    The Investor.gov retirement toolkit provides educational resources for retirement investors, while FINRA’s retirement resources explain important considerations when preparing financially for retirement.

    The Rule of 72: A Simple Compounding Shortcut

    A popular mental shortcut called the Rule of 72 estimates how long an investment might take to double at a fixed rate.

    Divide 72 by the hypothetical annual return.

    For example:

    72 ÷ 6 = approximately 12 years

    At 6%, money would take roughly 12 years to double.

    At 8%:

    72 ÷ 8 = approximately 9 years

    This is only an approximation, but it illustrates the relationship between returns and time.

    Be careful, however: higher potential returns generally involve greater investment risk. Never select an investment simply because it advertises a high return.

    Investment Example: $50 Per Week

    Suppose you invest $50 every week.

    That is approximately:

    $2,600 per year

    Over 30 years, your direct contributions would total approximately:

    $78,000

    If those contributions achieved a hypothetical long-term return, compound growth could potentially make the final portfolio significantly larger than the amount personally contributed.

    This is why consistency matters.

    Many people wait for a future moment when they expect to have thousands of dollars available to invest.

    That moment may never arrive.

    Starting with manageable recurring contributions can be more effective than endlessly waiting for perfect financial circumstances.

    Savings Example: The Young Worker

    Consider Maya, age 22.

    She earns a modest salary and believes investing is only for wealthy people.

    She decides to begin with $25 per week.

    That equals approximately $100–$110 monthly.

    As her income rises, she gradually increases the amount.

    At 25, she contributes $150 monthly.

    At 30, she increases it to $250.

    At 35, she contributes $400.

    Her greatest advantage isn’t that she started wealthy.

    She didn’t.

    Her advantage is that she established the habit early and increased contributions as her financial capacity improved.

    Retirement Example: Starting at 25 vs. Starting at 35

    Consider two hypothetical people.

    Daniel Starts at 25

    He invests $300 monthly until age 65.

    At a hypothetical 7% annual return, his account could grow to approximately $787,000.

    Michael Starts at 35

    Michael invests the same $300 monthly until age 65.

    At the same hypothetical return, his account could grow to approximately $366,000.

    Daniel had only ten additional years.

    But those ten years gave his earliest contributions significantly more time to compound.

    This demonstrates one of the most important principles in long-term wealth building:

    The cost of waiting can be enormous.

    What If You Are Already 40, 50 or Older?

    Do not interpret the importance of starting early as meaning it is too late to start.

    Starting today still gives your money more time than starting five years from now.

    Someone beginning later can potentially compensate in several ways:

    • Increase contributions
    • Reduce unnecessary expenses
    • Extend the investment horizon
    • Increase income
    • Use appropriate retirement accounts
    • Avoid excessive investment fees
    • Develop additional income sources

    The best time to start may have been years ago.

    The next available opportunity is now.

    Compound Interest Can Also Work Against You

    Compounding has another side.

    Debt can compound too.

    If you carry expensive debt and repeatedly fail to pay it down, interest can accumulate on the outstanding balance.

    This is particularly dangerous with high-interest credit cards and certain short-term loans.

    Instead of your money generating more money for you, interest charges can transfer increasing amounts of your future income to lenders.

    The Consumer Financial Protection Bureau’s credit-card resources provide educational information about credit cards, while the CFPB debt collection and financial education resources can help consumers better understand debt-related issues.

    The goal is to put compounding on your side of the financial equation whenever possible.

    Common Compound-Interest Mistakes

    1. Waiting Until You Earn More

    People frequently say:

    “I’ll start investing when I earn more.”

    Then income rises—and expenses rise with it.

    Start with an affordable amount and increase it gradually.

    2. Expecting Unrealistically High Returns

    Be suspicious of anyone promising extremely high, guaranteed investment returns.

    The Investor.gov fraud resources explain common warning signs of investment fraud, while FINRA BrokerCheck allows U.S. investors to research investment professionals and firms.

    3. Constantly Withdrawing Investments

    Compounding needs time.

    Frequently withdrawing long-term investments interrupts the process and may create taxes, fees or missed growth opportunities.

    4. Ignoring Investment Fees

    Small percentage fees can have large long-term effects.

    The SEC’s Investor Bulletin on fees and expenses explains why investment costs deserve attention.

    5. Taking Too Much Risk

    Compounding cannot help if catastrophic losses destroy your capital.

    Diversification and appropriate risk management matter.

    Investor.gov provides an explanation of diversification, and FINRA offers broader investing guidance.

    Use Compound Interest Calculators Before Setting Goals

    You do not have to calculate decades of compound growth manually.

    Online calculators allow you to experiment with:

    Starting amount
    Monthly contribution
    Estimated return
    Investment period
    Compounding frequency

    The Investor.gov Compound Interest Calculator is a useful starting point.

    You can also explore Investor.gov’s broader collection of financial calculators.

    Try several scenarios.

    What happens if you invest $100 monthly instead of $50?

    What happens if you start five years earlier?

    What if you increase contributions by $50 every year?

    What happens if returns are lower than expected?

    Scenario planning can help transform an abstract financial goal into a practical monthly target.

    Real-Life Case Study 1: Starting Small

    Imagine Anna, age 21, can afford only $50 per month.

    She feels embarrassed because friends online discuss investing thousands.

    But Anna begins anyway.

    After receiving salary increases, she gradually moves from:

    $50 → $100 → $200 → $300 monthly

    Her first $50 contribution wasn’t important because it instantly made her rich.

    It was important because it established the behavior that could continue for decades.

    Her wealth-building engine started early.

    Real-Life Case Study 2: The High Earner Who Waited

    James earns considerably more than Anna.

    But he continually postpones investing.

    At 25, he says he’ll begin at 30.

    At 30, he buys a more expensive vehicle.

    At 35, he upgrades his lifestyle again.

    At 40, he finally begins investing aggressively.

    James may still build substantial wealth because his income allows larger contributions.

    But money invested at 40 does not have the same amount of time to compound before traditional retirement age as money invested at 20 or 25.

    High income is valuable.

    High income combined with time is considerably more powerful.

    Real-Life Case Study 3: The Consistent Family

    Consider a family that automatically saves and invests part of every paycheck.

    They don’t try to predict which investment will become the next global sensation.

    They establish emergency savings, manage expensive debt, contribute regularly to diversified long-term investments and increase contributions whenever household income rises.

    Some years markets perform strongly.

    Other years investments decline.

    They remain focused on their long-term financial plan rather than reacting emotionally to every headline.

    Their primary advantage is not prediction.

    It is discipline and consistency.

    How to Use Compound Growth for Long-Term Wealth Building

    Compound interest becomes most powerful when combined with several other financial habits.

    Start Early

    Give your money as much time as reasonably possible.

    Contribute Consistently

    Automate recurring savings or investments where appropriate.

    Increase Contributions

    Whenever income increases, consider increasing your contribution before lifestyle inflation absorbs the entire raise.

    Reinvest Returns

    Allowing interest, dividends or other investment returns to remain invested can support compounding.

    Diversify

    Avoid depending entirely on one company, industry or speculative asset.

    Keep Costs Reasonable

    Fees reduce the amount of money remaining in your portfolio to compound.

    Avoid Emotional Decisions

    Fear can cause investors to sell during downturns, while greed can encourage buying speculative investments after dramatic price increases.

    Protect Your Financial Foundation

    Maintain appropriate emergency savings so you are less likely to liquidate long-term investments whenever an unexpected expense occurs.

    The Long-Term Wealth Formula

    Sustainable wealth building can be summarized simply:

    Earn → Save → Invest → Reinvest → Compound → Increase Contributions → Repeat

    You don’t need to execute this perfectly.

    You need to continue doing it.

    The first years can feel slow because your contributions create most of the growth.

    Eventually, if investments perform positively over time, investment growth itself can become a much larger part of the portfolio.

    That is when the compounding snowball becomes easier to see.

    A Simple Action Plan to Start Today

    Step 1: Calculate how much you can realistically save every month.

    Step 2: Build an appropriate emergency reserve.

    Step 3: Address expensive consumer debt.

    Step 4: Learn the basics of diversified investing.

    Step 5: Choose regulated financial products appropriate to your country and circumstances.

    Step 6: Automate contributions where possible.

    Step 7: Reinvest investment income when appropriate for your goals.

    Step 8: Increase contributions as your income rises.

    Step 9: Review your progress annually rather than obsessing over daily market movements.

    Step 10: Give your strategy time.

    The process is not glamorous.

    But successful long-term wealth building often isn’t.

    Conclusion

    Start Small, but Give Your Money Time to Grow

    Compound interest teaches one of the most encouraging lessons in personal finance:

    Your starting amount does not have to determine your final destination.

    Someone beginning with $25 or $50 may not feel like an investor.

    But that small beginning establishes something extremely valuable—a habit.

    As income increases, $50 can become $100.

    $100 can become $250.

    $250 can become $500.

    Meanwhile, earlier contributions have more time to potentially generate returns, and those returns can potentially generate additional returns.

    That is the power of compounding.

    Do not mistake the examples in this article for guaranteed investment outcomes. Markets fluctuate, savings rates change, inflation reduces purchasing power, taxes and fees matter, and every investment carries some degree of risk.

    But the fundamental mathematics remains powerful:

    Start early.
    Save consistently.
    Invest intelligently.
    Reinvest.
    Increase your contributions.
    Be patient.

    You do not need to wait until you are rich to begin investing.

    Consistent saving and investing over a long enough period may be one of the ways you build wealth in the first place.

    Educational Disclaimer: This article provides general financial education and does not constitute individualized financial, investment, retirement, tax or legal advice. Hypothetical returns are illustrations only and are not guaranteed. Investments can lose value, including principal. Financial products, taxes and regulations vary by country.

  • Emergency Funds Explained: Why Every Family Needs One Before Investing

    Emergency Funds Explained: Why Every Family Needs One Before Investing

    How to Build an Emergency Savings Fund, Protect Your Family From Financial Shocks and Prepare for Investing

    Introduction

    Financial Security Should Come Before Financial Growth

    Most families want their money to grow. They want to invest, buy property, build businesses, prepare for retirement and create a better financial future for their children. But before focusing entirely on investment returns, there is another financial priority that deserves attention: building an emergency fund.

    An emergency fund is money specifically reserved for expenses you did not reasonably expect—such as job loss, urgent medical costs, essential vehicle repairs, emergency travel or major home repairs. The Consumer Financial Protection Bureau’s emergency-fund guide explains that even relatively small savings can help families recover more quickly from financial shocks, while FINRA’s guidance for new investors recommends putting basic financial needs—including emergency savings—in order before beginning to invest.

    That distinction is important because emergency savings and investments serve different purposes. Investments are generally intended to grow money over time and may fluctuate in value. Emergency savings should emphasize safety, accessibility and liquidity.

    This guide explains how much to consider saving, where to keep the money, how to build your first reserve, how to prepare for family and medical emergencies, and how to rebuild your fund after you use it.

    What Is an Emergency Fund?

    An emergency fund is a dedicated pool of money reserved for unexpected and necessary financial expenses, rather than routine monthly spending or planned purchases. According to the CFPB, common uses include car and home repairs, medical bills and loss of income. FINRA’s financial-hardship guidance similarly recommends keeping emergency money somewhere safe and readily accessible rather than exposing it to investment risk.

    An emergency fund is therefore different from money for a holiday, new television, wedding, planned school fees or routine annual insurance premium. Those predictable costs can be handled through ordinary savings or sinking funds. Emergency savings should be protected for genuine financial shocks.

    Think of your emergency fund as a financial shock absorber. It does not prevent bad things from happening, but it can reduce the damage when they do.

    Why Build an Emergency Fund Before Investing?

    Investing can be an important part of long-term wealth creation, but investments can lose value—especially over short periods. If your entire financial reserve is invested and an emergency occurs during a market decline, you may be forced to sell at an unfavorable time. FINRA’s guidance for new investors recommends having funds available for emergencies before investing, while the CFPB emphasizes that emergency savings can reduce dependence on loans and credit cards after an unexpected expense.

    The principle can be summarized as:

    Emergency savings protect the present. Investments help finance the future.

    You may eventually need both. But building some financial resilience first can make your long-term investment strategy more sustainable.

    How Much Should You Save in an Emergency Fund?

    There is no universal amount appropriate for every household. Your target depends on family size, essential expenses, income stability, insurance, health circumstances, employment prospects and other sources of financial support. The CFPB recommends considering the unexpected expenses you have experienced previously when establishing your target, while FINRA describes three to six months of expenses as a useful goal while emphasizing that any amount you can afford to save is helpful.

    A practical approach is to build your fund in stages:

    Stage 1: First emergency cushion — $500, $1,000 or an achievable equivalent in your local currency.

    Stage 2: One month of essential expenses.

    Stage 3: Three months of essential expenses.

    Stage 4: Work toward three to six months—or another amount appropriate for your circumstances.

    For example, if your family’s essential monthly expenses are $2,500, three months would equal $7,500 and six months would equal $15,000. Someone with irregular income, dependents or uncertain employment may prefer a larger reserve than someone with highly stable income and strong household support

    Where Should You Keep Emergency Savings?

    Emergency money should generally satisfy three requirements: safe, accessible and separate from everyday spending. The CFPB emergency savings guide identifies dedicated bank or credit-union accounts as one option and warns that physical cash can be stolen, lost or destroyed. FINRA similarly recommends keeping emergency funds in a savings account or another safe location offering immediate access.

    Where available, consider a regulated savings account that provides competitive interest without sacrificing reasonable access to the money. Readers should check the deposit-insurance system applicable in their own country and verify account fees, withdrawal rules and institutional protections.

    Emergency savings generally should not depend on volatile stocks, cryptocurrencies or speculative assets. You don’t want to discover that the $10,000 you expected to use for an emergency is worth substantially less precisely when you need it.

    Building Your First Emergency Reserve From Scratch

    If you have no emergency savings today, don’t become discouraged by a target of several months of expenses. Start smaller. The CFPB specifically emphasizes that even small amounts can provide financial security, and its automatic-saving guidance recommends regular automatic transfers as one of the easiest ways to build savings consistently.

    Start with an amount you can maintain:

    $5 a week = $260 per year
    $10 a week = $520 per year
    $25 a week = $1,300 per year
    $50 a week = $2,600 per year

    If your income is irregular, consider saving a percentage of every payment instead of a fixed monthly amount.

    Bonuses, gifts, business profits, overtime payments and other occasional income can also accelerate progress. The key is to create a repeatable savings system rather than waiting for the mythical month when you suddenly have plenty of money left over.

    Make Emergency Saving Automatic

    Automation changes emergency saving from a monthly decision into a financial system. The CFPB recommends automatic transfers from checking to savings and notes that some workers may be able to divide direct deposits between accounts. Its separate automatic-saving guide similarly explains that recurring transfers can make consistent saving easier.

    For example, if you are paid every two weeks, arrange for $25 to move automatically into emergency savings after each paycheck. You would contribute approximately $650 over 26 pay periods without needing to manually make 26 separate saving decisions.

    When your income increases, increase the automatic contribution before your lifestyle absorbs the entire raise.

    What Counts as a Real Emergency?

    An emergency is generally unexpected, necessary and financially significant. The CFPB gives examples such as medical bills, car repairs, home repairs and loss of income, while its family emergency-preparedness guidance also highlights emergency travel and disaster-related costs.

    Common legitimate emergencies might include:

    • Essential vehicle repairs needed to get to work
    • Urgent medical or dental treatment
    • Sudden job loss
    • Emergency travel for a serious family situation
    • Critical home repairs
    • Temporary loss of income
    • Essential appliance replacement
    • Disaster-related expenses not immediately covered by insurance

    A discounted vacation, new smartphone, designer clothing or spontaneous shopping opportunity is generally not an emergency.

    Establish your family’s rules before temptation appears.

    Emergency Funds Can Help You Avoid Credit Card Debt

    Without cash reserves, a $1,500 emergency may become a $1,500 credit-card balance. Interest and fees can then make the original emergency substantially more expensive. The CFPB warns that using credit or loans for emergency expenses can turn a one-time financial shock into harder-to-repay debt, while FINRA recommends addressing high-interest debt as part of establishing a sound financial foundation.

    Credit cards can be useful financial tools when managed carefully, but they are not the same thing as emergency savings.

    An emergency fund allows you to use yesterday’s savings instead of tomorrow’s income to solve today’s problem.

    That difference can prevent one emergency from creating months or years of repayments.

    How Inflation Affects Your Emergency Fund

    Inflation gradually increases the cost of food, housing, transportation, utilities, healthcare and other necessities. That means an emergency target calculated several years ago may no longer cover the same number of months. Families can use an official inflation measure applicable to their country; for international comparisons and economic data, the World Bank’s inflation indicator provides country-level information, while the International Monetary Fund provides broader educational and economic resources on inflation.

    Review your emergency target at least annually.

    If essential monthly expenses rise from $2,000 to $2,400, a six-month target rises from $12,000 to $14,400.

    Interest earned on a savings account can help offset some loss of purchasing power, but the primary purpose of emergency money remains liquidity and financial protection, not maximizing investment returns.

    Preparing for Family Emergencies

    Family emergencies often affect more than one person and may require money immediately. Emergency travel, temporary caregiving, home repairs, natural disasters or supporting dependent children can create expenses that ordinary monthly budgets cannot absorb. The CFPB’s family emergency guide recommends financial preparation before disasters occur, while the CFPB’s broader emergency-fund guidance emphasizes establishing clear rules for when emergency savings should be used.

    Families should discuss:

    Who can access the emergency account?
    What qualifies as an emergency?
    Where are important financial documents?
    Which expenses are insured?
    Who should be contacted during a crisis?

    Families in areas exposed to natural disasters may also benefit from keeping a small, secure amount of physical cash for situations when electricity, payment networks or ATMs are unavailable. However, the CFPB notes that cash stored at home can be vulnerable to theft, fire or other loss.

    Preparing for Medical Emergencies

    Medical emergencies can create both direct and indirect financial costs. Families may face treatment bills, deductibles, medication, transportation, childcare or lost wages while someone recovers. Emergency savings can help absorb costs not immediately covered by insurance; the CFPB emergency-fund guide specifically identifies unexpected medical bills as a common reason for emergency savings, while the World Health Organization provides global information about health financing and financial protection.

    Healthcare systems vary dramatically across countries. Some countries provide broad public healthcare coverage; others place more costs directly on households.

    Review your health coverage and understand what you might have to pay yourself. Where appropriate, maintain insurance or other health coverage alongside emergency savings.

    An emergency fund should complement insurance—not necessarily replace it.

    Preparing Financially for Job Loss

    Job loss is particularly difficult because it can remove income while household expenses continue. The CFPB notes that savings can help households weather furloughs, job losses and reduced working hours, while FINRA’s hardship guide identifies job loss as a major financial shock for which advance planning can help.

    Calculate your survival budget now.

    Identify what your household would absolutely need each month for:

    Housing
    Basic food
    Utilities
    Essential transportation
    Insurance
    Healthcare
    Minimum debt obligations
    Necessary communication

    Suppose normal household spending is $4,000 monthly, but essential survival expenses are $2,700. A $10,800 emergency fund could potentially cover approximately four months of those essential costs.

    Knowing this number gives your emergency-fund goal a concrete purpose.

    Should You Invest While Building an Emergency Fund?

    This is not always an either-or decision. Individual circumstances differ, especially when employer retirement contributions, pensions, high-interest debt, taxes or other benefits are involved. However, FINRA’s new-investor guidance recommends ensuring that basic needs and emergency savings are addressed before investing, while the CFPB explains how a dedicated cash reserve protects against financial shocks.

    A beginner might therefore prioritize building an initial emergency cushion before committing significant discretionary money to higher-risk investments.

    As the reserve becomes stronger, the balance can gradually shift toward long-term investment goals.

    Remember:

    Emergency fund = protection and liquidity.
    Investment portfolio = long-term growth with risk.

    Trying to make one account perform both jobs can create problems.

    What Should You Do After Using Your Emergency Fund?

    Using an emergency fund for a genuine emergency does not mean you failed.

    That is exactly why the money existed.

    The CFPB explicitly advises consumers who use their emergency savings to work on building the fund again, while its saving resources encourage establishing recurring contributions that make rebuilding more systematic.

    Suppose you had $8,000 and used $2,500 for an urgent home repair.

    Your new balance is $5,500.

    Create a temporary rebuilding plan. Perhaps redirect some discretionary spending, bonuses or extra income toward replacing the $2,500. If you were previously contributing $100 monthly, temporarily increasing that to $200 may accelerate recovery if your budget permits.

    Do not punish yourself for using emergency savings appropriately.

    Use it. Recover. Rebuild it. Continue.

    Emergency Fund Checklist for Families

    Before moving aggressively toward investing, ask:

    ☐ Do we have a dedicated emergency savings account?
    ☐ Do we know our essential monthly expenses?
    ☐ Have we established an initial savings target?
    ☐ Could we handle an urgent vehicle or home repair?
    ☐ Have we planned for possible job loss?
    ☐ Have we considered medical expenses?
    ☐ Do we understand our insurance coverage?
    ☐ Have we defined what qualifies as an emergency?
    ☐ Is the money reasonably accessible?
    ☐ Is it protected from everyday spending?
    ☐ Are we contributing automatically?
    ☐ Do we review the target as living costs change?
    ☐ Do we have a plan for rebuilding the fund after using it?

    If several answers are “no,” strengthening your financial safety net may deserve priority.

    Conclusion

    Build Your Financial Safety Net Before Chasing Returns

    Investing is exciting because it offers the possibility of growth.

    Emergency savings rarely feels exciting.

    But financial security is not built only by maximizing returns. It is also built by surviving financial shocks without destroying the progress you have already made.

    A strong emergency fund gives your family options.

    When the car breaks down, you have money.

    When an urgent medical bill appears, you have a reserve.

    When employment suddenly ends, you have time to make better decisions.

    When an unexpected family situation requires travel or caregiving, you are better prepared.

    And when markets fall, you may be less likely to sell long-term investments simply because you urgently need cash.

    Start small if necessary. Establish your first $500, $1,000 or an appropriate amount in your local currency. Then work toward one month of essential expenses and gradually build a larger reserve suited to your household.

    Keep it safe. Keep it accessible. Protect it from unnecessary spending. Adjust it as your family’s expenses change.

    And when you eventually use it, rebuild it.

    Emergency savings protect your family today so that your long-term investments have a better chance to build your future.

    Educational Disclaimer: This article provides general financial education and does not constitute individualized financial, investment, tax, insurance, medical or legal advice. Appropriate emergency savings amounts and financial products vary by household and country. Verify local deposit protections, account rules, taxes and regulations before making financial decisions.

  • 30 Proven Budgeting Strategies That Will Help You Build Wealth Faster

    30 Proven Budgeting Strategies That Will Help You Build Wealth Faster

    A Practical Global Guide to Managing Money, Cutting Expenses, Saving More and Building Long-Term Financial Security

    Introduction

    Budgeting is not simply about spending less. A good budget gives every part of your income a purpose—covering today’s needs while creating room for savings, debt reduction, emergencies, investments, and future goals.

    Whether you earn dollars, euros, pounds, shillings, pesos, rupees, rand, or another currency, the basic principle is similar: understand what comes in, control what goes out, and intentionally direct the difference toward your financial future.

    This matters in both developed and developing economies. The exact expenses, financial products, inflation rates, banking systems, and incomes may differ, but effective money management depends on many of the same behaviors. Here are 30 practical budgeting strategies you can adapt to your circumstances.

    1. Understand What Budgeting Really Means

    A budget is a financial plan showing how much money you expect to receive and how you intend to use it.

    It should include income, essential expenses, discretionary spending, debt payments, savings, and investments.

    The purpose is not to punish yourself. It is to make deliberate decisions before your money disappears.

    The World Bank’s financial capability resources emphasize behaviors such as managing resources and using financial services appropriately as important elements of financial capability.

    2. Know Why Budgets Fail

    Many budgets fail because they are unrealistic.

    A person may create a perfect spreadsheet that allows almost nothing for entertainment, unexpected expenses, price increases, family obligations, or occasional purchases.

    Within weeks, the plan collapses.

    Instead, create a budget around your real behavior and real income. Review previous bank statements, mobile-money transactions, receipts, bills, and cash spending before deciding what your future budget should look like.

    3. Track Every Expense

    You cannot effectively control spending you do not understand.

    Track your expenses for at least 30 days. Include large bills and seemingly insignificant purchases.

    Investor.gov recommends tracking household income and expenses and including savings and investing as part of the monthly financial plan. Learn how to evaluate your finances.

    Small purchases matter because repeated expenses can become surprisingly large over time.

    4. Try Zero-Based Budgeting

    With zero-based budgeting, every unit of income receives a job.

    If your monthly income is $3,000, for example, your planned expenses, savings, debt payments, and investments should collectively account for that $3,000.

    That does not mean spending everything.

    Money assigned to savings, investments, or an emergency fund has also been given a purpose.

    Zero-based budgeting can be especially useful for people who want detailed control over their finances.

    Consider the 50/30/20 Budget

    A popular framework divides after-tax income approximately into:

    50% for needs
    30% for wants
    20% for savings, investments and financial goals

    Treat these percentages as guidelines rather than universal rules.

    Someone living in a high-cost European or North American city may spend more than 50% on necessities. A household in a lower-income country supporting extended family members may face entirely different financial pressures.

    Adapt the percentages to reality.

    6. Experiment With the 70/20/10 Method

    Another simple approach is:

    70% — living expenses
    20% — savings and investments
    10% — debt repayment, giving or other financial priorities

    The advantage is simplicity.

    Again, adjust the percentages according to your circumstances. The system should serve you—not the other way around.

    7. Use Envelope Budgeting

    Envelope budgeting assigns spending limits to categories such as groceries, transportation, entertainment, clothing, and household expenses.

    Traditionally, people placed physical cash into separate envelopes.

    Today you can create digital equivalents using separate accounts, banking categories, spreadsheets, or budgeting apps.

    When the entertainment allocation is exhausted, entertainment spending stops until the next budget period.

    8. Build a Digital Budget

    You do not need complicated financial software.

    A spreadsheet, banking application, mobile-money history, or budgeting app can provide enough information to create a useful system.

    Readers who want a free online example can explore the UK’s MoneyHelper Budget Planner, which calculates income and outgoing expenses and shows what remains.

    The underlying budgeting concepts can be useful regardless of where you live, although financial products and regulations differ by country.

    9. Create a Family Budget

    Household budgeting works best when the people making financial decisions understand the plan.

    Discuss major expenses, debt, savings goals, children’s needs, education costs, transportation, housing, and upcoming purchases.

    Avoid turning budgeting discussions into arguments over every small expense.

    Instead, establish shared goals such as:

    “We want to build a three-month emergency reserve.”

    A common objective makes financial discipline easier to understand.

    10. Create a Student Budget

    Students should learn budgeting before earning large incomes.

    Start with tuition or school costs, housing, transportation, food, communication, books, entertainment, and personal expenses.

    Then compare those expenses with scholarships, family support, employment income, grants, or other legitimate income.

    Even saving a small amount regularly develops an important lifelong habit.

    11. Budget for Inflation

    Inflation reduces purchasing power.

    If groceries, fuel, electricity, rent, transportation, or other necessities increase in price, an old budget may no longer work.

    Review essential categories and update them.

    Rather than eliminating savings automatically, first examine discretionary expenses that can be reduced.

    This principle is relevant globally because inflation can affect households in both advanced and emerging economies.

    12. Separate Needs From Wants

    Housing, basic food, essential transportation, medicine, and necessary utilities are generally needs.

    Premium entertainment subscriptions, frequent restaurant meals, luxury upgrades, and impulse purchases are generally wants.

    The distinction is not always perfect, but asking “Do I need this or simply want it?” creates a valuable pause before spending.

    13. Pay Yourself First

    Do not wait until the end of the month to discover whether anything remains.

    Include savings directly in your budget.

    For example:

    Income → Savings → Essential expenses → Other spending

    Automatic transfers can make this easier.

    Investor.gov describes automatic deposits into savings or investment accounts as one practical way to develop the habit of paying yourself first. Read more about managing income and expenses.

    14. Build an Emergency-Fund Category

    Unexpected expenses are inevitable.

    A medical bill, broken appliance, vehicle repair, family emergency, or temporary loss of income can destroy a budget if there is no reserve.

    Create an emergency-fund contribution inside your monthly budget—even if you initially contribute only a small amount.

    15. Budget With Irregular Income

    Freelancers, farmers, contractors, gig workers, seasonal employees, and small-business owners may not receive identical monthly income.

    Build your core budget around a conservative income estimate.

    When income is higher than expected, direct part of the surplus toward savings and future low-income months rather than immediately increasing spending.

    This strategy is particularly valuable where informal or seasonal employment is common.

    16. Use a Budgeting App—But Don’t Depend on It

    Budgeting apps can categorize transactions, monitor spending, issue alerts, and display progress.

    But an app cannot create discipline for you.

    Before choosing one, investigate cost, security, privacy, banking compatibility, supported countries, and whether your financial institutions can connect to it.

    A spreadsheet or notebook can still be an excellent budgeting system.

    17. Attack Expensive Debt

    High-interest debt can consume money that could otherwise build wealth.

    List debts by balance, interest rate, minimum payment, and due date.

    Two common approaches are the debt avalanche, which prioritizes the highest interest rate, and the debt snowball, which targets the smallest balance first for psychological momentum.

    Investor.gov specifically warns that high-interest credit-card debt can make purchases significantly more expensive and interfere with long-term wealth building. See its wealth-building guidance.

    18. Negotiate and Reduce Regular Bills

    Review recurring bills several times a year.

    Look at:

    • Mobile-phone plans
    • Internet
    • Insurance
    • Banking fees
    • Streaming services
    • Utilities
    • Memberships
    • Software subscriptions

    Ask whether you still need the service and whether a cheaper alternative exists.

    Saving $20 each month becomes $240 annually.

    19. Create a Grocery Budget

    Food is essential, but grocery spending can still be managed.

    Plan meals, prepare a shopping list, compare unit prices, use seasonal foods, avoid unnecessary waste, and limit impulse purchases.

    Buying locally produced staples may be economical in some countries, while bulk purchasing may work better elsewhere.

    The goal is not simply finding the cheapest food. It is obtaining good nutritional value without unnecessary waste.

    20. Control Transportation Costs

    Transportation can consume a significant percentage of household income.

    Calculate the total cost—not merely a vehicle payment.

    Consider fuel, insurance, maintenance, registration, parking, public transportation, ride-hailing, and repairs. Walking, cycling, carpooling, public transportation, or choosing a less expensive vehicle may free significant money for other goals where those alternatives are safe and practical.

    21. Give Entertainment Its Own Budget

    A wealth-building budget does not require eliminating enjoyment.

    Create a reasonable entertainment allowance.

    Once that amount is exhausted, postpone additional entertainment spending until the next budgeting period.

    This helps prevent guilt while still maintaining boundaries.

    22. Use the 24-Hour Purchase Rule

    Impulse spending destroys many good budgets.

    Before buying a nonessential item, wait at least 24 hours.

    For expensive purchases, consider waiting several days.

    Investor.gov similarly recommends a waiting period for impulse purchases and notes that small savings can accumulate significantly over time. See how small savings can add up.

    23. Create Sinking Funds

    Not every large expense is an emergency.

    Birthdays, holidays, school fees, annual insurance premiums, vehicle maintenance, weddings, travel, and home repairs can often be anticipated.

    Create separate sinking funds.

    If an annual expense will cost $600, saving $50 monthly makes the eventual payment far easier to absorb.

    24. Automate Important Financial Goals

    Automation can make financial discipline easier.

    Where your bank, employer, credit union, mobile-money provider, or financial platform supports it, automate contributions toward savings and long-term goals.

    Automation reduces the temptation to spend first and save later.

    25. Budget for Retirement

    Retirement planning should not begin at retirement.

    Include long-term saving or investing in your budget as early as reasonably possible.

    The exact system varies dramatically by country—workplace pensions, government programs, retirement accounts, provident funds, personal investments, or other arrangements may be available.

    The universal principle is start early and contribute consistently.

    Investor.gov explains that regular contributions plus time can be powerful for long-term wealth creation. Learn about saving and investing for long-term goals. Its compound interest calculator can also illustrate how recurring contributions may grow over time.

    26. Increase Savings When Income Increases

    A raise should improve your financial future, not only your lifestyle.

    Suppose your income increases by $300 monthly.

    Instead of spending the entire increase, you might automatically redirect $150 toward savings, investments, or debt repayment.

    You still enjoy some lifestyle improvement while accelerating wealth creation.

    27. Budget Before Receiving Extra Money

    Bonuses, tax refunds, gifts, commissions, harvest income, overtime pay, and business windfalls are easier to waste when they arrive without a plan.

    Decide beforehand how unexpected income will be divided.

    For example:

    40% savings or investing
    30% debt reduction
    20% planned purchases
    10% enjoyment

    Your percentages can differ. What matters is deciding intentionally.

    28. Set Financial Goals Behind Your Budget

    Budgeting becomes easier when every sacrifice has a reason.

    Your goals might include:

    • Becoming debt-free
    • Building an emergency fund
    • Buying a home
    • Funding education
    • Starting a business
    • Supporting your family
    • Buying productive equipment
    • Investing
    • Preparing for retirement

    Give each goal an amount and target date.

    Investor.gov’s free financial planning tools include savings and compound-interest calculators that can help readers translate goals into regular contributions.

    29. Build Financial Discipline, Not Financial Perfection

    You will occasionally overspend.

    An unexpected expense may appear. Prices may rise. Income may fall.

    That does not mean your budget has failed.

    Adjust it.

    Long-term financial progress depends more on repeatedly returning to good habits than maintaining a perfect spreadsheet.

    The World Bank’s work on financial capability similarly looks beyond financial knowledge alone toward behaviors such as planning, monitoring money, saving, and balancing income with expenses. Explore the World Bank’s financial capability resources.

    30. Review Your Budget Every Month

    A budget should evolve with your life.

    At the end of every month, compare your plan with what actually happened.

    Ask:

    Did I spend more than I earned?
    Did I meet my savings target?
    Which categories exceeded the budget?
    Which expenses can be reduced?
    Did my debt decrease?
    Did my emergency fund increase?
    Do I have upcoming annual expenses?
    Has my income changed?
    Should I increase my savings or investments?

    Then build the next month’s budget using what you learned.

    Monthly Budget Review Checklist

    Before beginning a new month, complete this simple review:

    ☐ Record total income
    ☐ Record total expenses
    ☐ Compare planned versus actual spending
    ☐ Review groceries and transportation
    ☐ Check recurring subscriptions
    ☐ Review debt balances
    ☐ Transfer money to emergency savings
    ☐ Review investment or retirement contributions
    ☐ Prepare for upcoming irregular expenses
    ☐ Update financial goals
    ☐ Adjust next month’s spending limits

    A 20-minute monthly review can reveal financial problems before they become much larger.

    From Budgeting to Wealth Building

    Budgeting alone will not make everyone wealthy. Its real power is that it creates the financial space from which wealth can potentially be built.

    Consider the progression:

    Earn → Budget → Spend Less Than You Earn → Save → Build Emergency Reserves → Reduce Expensive Debt → Invest for Long-Term Goals → Repeat

    The final stages matter.

    Money that will be needed soon generally has a different purpose from money intended for long-term wealth building. Investing involves risk, but over longer periods it can provide opportunities for growth that ordinary cash savings may not provide.

    Investor.gov summarizes the long-term concept simply: regular investing plus time can contribute to wealth creation.

    Budgeting in Developed and Developing Countries

    Personal finance advice should recognize that financial realities differ around the world.

    Someone in Canada may use a credit card, employer retirement plan, and online bank. Someone in Uganda may combine a commercial bank account, mobile money, cash income, family obligations, and informal business earnings. A worker in Germany, India, Australia, Brazil, Tanzania, South Africa, or the United Kingdom will encounter different taxes, currencies, financial institutions, social programs, and living costs.

    Yet several principles travel remarkably well:

    Know your income.
    Track expenses.
    Prioritize necessities.
    Avoid unnecessary high-cost debt.
    Prepare for emergencies.
    Save consistently.
    Plan for long-term goals.
    Use regulated financial institutions where appropriate.
    Review your progress regularly.

    The World Bank’s research into financial capability in low- and middle-income economies specifically recognizes that household financial decisions must account for different income sources, informal employment, family responsibilities, and varying access to pensions, insurance, and formal financial services.

    That is why there is no single budget percentage that works everywhere.

    The best budget is the one built around your income, your country, your household, your obligations and your financial goals.

    Final Thoughts: Make Every Dollar—or Every Unit of Currency—Have a Purpose

    Building wealth is rarely the result of one dramatic financial decision.

    It is usually the accumulation of thousands of smaller decisions.

    You decide whether to spend or save. You decide whether to borrow unnecessarily. You decide whether to track your expenses. You decide what happens when your income increases. And you decide whether today’s money will only support today’s lifestyle or also help finance tomorrow’s opportunities.

    Start with a simple budget.

    Track what you spend for 30 days. Choose a budgeting method. Build an emergency fund. Reduce expensive debt. Automate savings where possible. Review your progress every month.

    Then, as your financial position strengthens, begin directing more of the gap between what you earn and what you spend toward productive long-term goals.

    Your income matters.

    But what you consistently do with that income can matter even more.

    Budget with purpose. Save consistently. Invest thoughtfully. Give your financial plan enough time to work.Educational disclaimer: This article provides general financial education, not individualized financial, investment, tax, credit, or legal advice. Financial products, consumer protections, taxes, retirement systems, inflation, investment risks, and regulations differ by country. Readers should verify local requirements and, when necessary, consult an appropriately qualified professional

  • Why Saving Is the Foundation of Wealth: A Complete Step-by-Step Guide for Beginners (Even on a Small Income)

    Why Saving Is the Foundation of Wealth: A Complete Step-by-Step Guide for Beginners (Even on a Small Income)

    Learn Practical Saving Systems, Budgeting Strategies, and Wealth-Building Habits That Can Transform Your Financial Future

    Introduction

    Building wealth does not begin with earning a huge salary—it begins with learning how to manage and save the money you already have. Whether you are a student, employee, entrepreneur, supporting a family, living on a small income, or dealing with irregular earnings, developing consistent saving habits can create the foundation for greater financial security and long-term wealth. In this complete beginner’s guide, you will learn how to save money and build wealth through practical saving strategies, budgeting, emergency funds, the Pay Yourself First method, automated savings, and other proven money-management habits. You will also discover how to protect your savings and eventually turn accumulated savings into investment capital, helping you move step by step toward greater financial stability and financial freedom.

    Saving creates the financial foundation from which emergency security, investing, homeownership, entrepreneurship, retirement planning, and long-term wealth can grow.

    You may earn $1,000, $3,000, or $10,000 a month, but income alone does not determine financial security. What matters is how much of your income you keep, how effectively you manage it, and what you eventually do with the money you accumulate. This beginner-friendly guide explains practical saving techniques you can use whether you have a regular salary, irregular income, are a student, supporting a family, temporarily unemployed, or simply starting your financial journey

    Why Saving Is the Foundation of Wealth

    Saving creates a gap between what you earn and what you spend. That gap is where financial progress begins.

    Without savings, an unexpected car repair, medical expense, job interruption, or family emergency can force you to borrow. With savings, the same event may become an inconvenience rather than a financial crisis.

    The U.S. Consumer Financial Protection Bureau explains that even a small dedicated emergency fund can help people recover more quickly from unexpected expenses. CFPB Emergency Fund Guide

    Saving also creates capital. The first $500 you save may become an emergency cushion. Later, $5,000 or $10,000 could help finance education, a business, a home purchase, or long-term investments.

    Common Myths About Saving Money

    One of the biggest myths is: “I will start saving when I earn more.”

    Higher income certainly makes saving easier, but earning more does not automatically create wealth. If spending rises every time income increases, there may still be nothing left.

    Another myth is that small amounts are meaningless. They are not. Saving $5 a day equals $1,825 in one year before interest. The SEC’s Investor.gov explains how small amounts can become considerably larger over time when saving and investing are combined with compound growth. See How Small Savings Can Add Up

    The habit matters before the amount becomes large.

    Why Income Alone Doesn’t Create Wealth

    Imagine two workers.

    Person A earns $8,000 monthly but spends $8,200. Person B earns $4,000 but consistently saves $600.

    Who is moving toward greater financial stability?

    Income provides opportunity. Financial discipline determines what happens to that opportunity.

    Increasing your earnings is important, but building wealth usually requires controlling expenses, saving consistently, managing debt carefully, and eventually putting appropriate long-term money to productive use.

    Set SMART Savings Goals

    “Save more money” is a wish. A specific savings target is a plan.

    Use the SMART framework: make your goal Specific, Measurable, Achievable, Relevant, and Time-bound.

    Instead of saying, “I want an emergency fund,” say:

    “I will save $1,200 during the next 12 months by automatically transferring $100 each month into a separate savings account.”

    You immediately know the destination, deadline, and required monthly contribution.

    Investor.gov also provides a free Savings Goal Calculator that can help estimate how much you need to save regularly to reach a financial target.

    Create Your First Emergency Fund

    Before chasing high investment returns, establish financial protection.

    Start with an achievable milestone such as $500 or $1,000. Then work toward one month of essential expenses and gradually increase your reserve according to your circumstances.

    Some financial professionals commonly suggest eventually holding roughly three to six months of essential expenses, although the appropriate amount depends on employment stability, household responsibilities, health expenses, insurance, and other risks.

    Keep emergency savings somewhere safe and reasonably accessible rather than exposing money needed soon to unnecessary market risk.

    Use the Pay Yourself First Principle

    Most people follow this formula:

    Income → Expenses → Save whatever remains.

    Try reversing it:

    Income → Savings → Necessary expenses → Discretionary spending.

    This is the Pay Yourself First principle.

    When your paycheck arrives, transfer a predetermined amount into savings before optional spending begins. Even 5% is a meaningful starting point if that is what your budget allows.

    Saving becomes a financial obligation to your future self rather than an afterthought.

    Daily, Weekly and Monthly Saving Systems

    Different saving schedules work for different personalities.

    For a daily system, save a small fixed amount, transfer spare change, or redirect the cost of one unnecessary purchase. A $3 daily habit becomes more than $1,000 over a year.

    For a weekly system, choose one day—perhaps every Friday—to review spending and transfer a predetermined amount.

    For a monthly system, treat savings like rent or another recurring bill. Schedule it immediately after payday.

    Consistency is more important than choosing the “perfect” schedule.

    Try the 52-Week Saving Challenge

    The 52-week challenge turns saving into a gradual habit.

    Traditionally, you save $1 in week one, $2 in week two, $3 in week three, continuing until $52 in week 52. Completing the challenge produces $1,378.

    You can also reverse the challenge, starting with $52 and decreasing each week, or use a fixed weekly amount that better matches your income.

    The objective is not the specific formula. It is developing consistency.

    Automate Your Savings

    Automation removes repeated decision-making.

    Schedule an automatic transfer from checking to savings shortly after each payday. If your employer permits split direct deposit, you may be able to send part of every paycheck directly into savings.

    The CFPB specifically identifies automatic deposits and recurring transfers as practical ways to build savings consistently. CFPB Guide to Saving Automatically When saving happens automatically, you are less dependent on motivation

    Choose a Budgeting Method You Can Maintain

    A budget tells your money where it should go.

    One popular starting framework is the 50/30/20 approach: roughly 50% toward needs, 30% toward wants, and 20% toward savings and/or financial priorities. Those percentages are guidelines, not rules. Someone with high housing costs or a low income may need a different allocation.

    Another approach is zero-based budgeting, where every dollar of expected income receives a purpose before the month begins.

    The best budget is not necessarily the most complicated one. It is the system you can realistically follow month after month.

    Consider a High-Yield Savings Account

    Leaving substantial savings in an account paying very little interest can reduce its growth potential.

    A competitive high-yield savings account may provide a better return while retaining relatively easy access. Rates change, so compare APY, minimum balances, withdrawal options, fees, and deposit protection rather than choosing an account based only on an advertisement.

    In the United States, eligible deposits at an FDIC-insured bank are automatically insured to at least $250,000 per depositor, per insured bank, subject to ownership-category rules. Learn About FDIC Deposit Insurance

    Readers outside the United States should check their country’s equivalent deposit-protection system.

    Cut Unnecessary Expenses Without Making Life Miserable

    Saving does not require eliminating everything you enjoy.

    Start by identifying expenses providing little value: forgotten subscriptions, frequent delivery fees, impulse purchases, excessive banking fees, unused memberships, or expensive habits that have cheaper alternatives.

    Try a 24-hour rule before nonessential purchases. For larger purchases, consider waiting several days.

    Redirect at least part of the money you avoid spending directly into savings. Otherwise, “saving money” on one purchase can easily become spending it somewhere else.

    How to Save With Irregular Income or While Unemployed

    Freelancers, seasonal workers, gig workers, and entrepreneurs can save using percentages rather than fixed amounts.

    For example, decide that 5% or 10% of every payment received goes into savings. During high-income months, save more to create a buffer for slower periods.

    If unemployed, the immediate goal may change from aggressive saving to protecting existing cash. Prioritize housing, food, utilities, transportation, insurance, and other essentials. Reduce nonessential expenses and investigate legitimate benefits or assistance for which you qualify.

    Saving $5 during a difficult month still maintains the habit—but essential needs come first.

    Saving as a Student

    Students have one enormous financial advantage: time.

    Begin with manageable amounts. Save part of income from a part-time job, scholarship refund that is genuinely available for personal use, gifts, or other discretionary income.

    Learning budgeting, avoiding unnecessary debt, comparing prices, cooking more often, using student discounts, and saving even $10 or $20 regularly can establish habits that continue long after graduation.

    Family Saving Strategies

    Household saving works better when financial goals become shared goals.

    Families can create separate savings categories for emergencies, education, vacations, home repairs, vehicles, and major purchases. Parents can also involve children in age-appropriate discussions about needs, wants, saving, and delayed gratification.

    A family target—such as saving $3,000 for emergencies—can be divided into smaller monthly milestones so everyone can see progress.

    Use Mobile Banking and Savings Apps Carefully

    Modern banking makes saving easier. Mobile banking apps can provide automatic transfers, balance alerts, savings goals, spending notifications, and recurring deposits.

    Budgeting tools such as YNAB can help users plan where their money goes, while Acorns combines automated saving and investing features.

    No app is universally “best.” Compare subscription costs, security, account protection, features, withdrawal restrictions, and whether the service involves saving or investing. Investment accounts can lose value and should not be confused with insured bank savings.

    Common Saving Mistakes to Avoid

    The biggest mistakes include waiting for the “perfect” income, setting unrealistic targets, keeping no emergency reserve, repeatedly withdrawing savings for non-emergencies, ignoring high-interest debt, failing to track expenses, and increasing lifestyle spending every time income rises.

    Another mistake is treating every saved dollar as investment money. Emergency savings and long-term investments have different purposes

    Protect Your Savings

    Building money is only half the job. You must protect it.

    Use strong unique passwords, multi-factor authentication where available, account alerts, and reputable financial institutions. Be suspicious of unsolicited messages promising guaranteed profits or unusually high returns.

    Investor.gov warns that promises of high investment returns with little or no risk, pressure to act immediately, fake testimonials, and suspicious payment methods are common investment-fraud warning signs. Investor.gov Fraud and Investor Education Resources

    Turn Savings Into Investment Capital

    Saving provides security. Investing can provide long-term growth.

    Once you have appropriate emergency reserves and control over expensive debt, some money intended for long-term goals may potentially move toward diversified investments appropriate to your objectives, time horizon, and risk tolerance.

    Do not invest emergency money you may need next month.

    Investor.gov describes regular investing plus time as a powerful approach to building wealth and recommends establishing emergency savings alongside long-term investing. SEC Guide to Building Wealth Through Saving and Investing

    Case Studies: How Small Savings Can Build Financial Momentum

    Case Study 1 — The beginner: Maria can save only $25 each week. Instead of waiting until she earns more, she automates the transfer. After 52 weeks, she has contributed $1,300 before any interest. Her first financial victory is not becoming rich—it is proving she can consistently keep money.

    Case Study 2 — The irregular-income worker: Daniel’s monthly income changes. Rather than promising himself a fixed $300 contribution he cannot always afford, he saves 10% whenever he gets paid. Strong months automatically produce larger contributions, while difficult months remain manageable.

    Case Study 3 — The lifestyle reset: Aisha reviews several months of transactions and discovers approximately $180 per month going toward subscriptions, delivery fees, and impulse purchases she barely remembers. She cuts $100 and automatically transfers it monthly. In one year, she contributes $1,200 toward her emergency fund without increasing her salary.

    These examples are illustrative, but the principle is universal: wealth-building starts when part of today’s income is deliberately reserved for tomorrow.

    Final Thoughts: Start Small, Start Today

    You do not need to become wealthy before you begin saving. Saving is one of the habits that can help you build wealth.

    Start with an amount you can sustain. Create an emergency fund. Pay yourself first. Automate your contributions. Control unnecessary spending. Increase the amount when your income rises. Protect the money you accumulate. Then learn how to responsibly put long-term capital to work.

    Your first $10 may not appear life-changing. Neither may your first $100.

    But the habit behind those dollars can change the direction of your financial life.

    Start today. Save consistently. Protect what you build. Then give your money time to grow.

    Educational disclaimer: This article provides general financial education and does not constitute individualized financial, investment, tax, or legal advice. Financial products, regulations, interest rates, risks, and deposit-protection rules vary by country and can change over time.