Category: Global Economy

  • Forex Trading for Beginners: The Complete Step-by-Step Guide to Understanding the World’s Largest Financial Market

    Forex Trading for Beginners: The Complete Step-by-Step Guide to Understanding the World’s Largest Financial Market

    Learn How the Foreign Exchange Market Works, Manage Risk, Read Currency Charts, and Avoid Costly Beginner Mistakes

    Introduction

    Every day, currencies move around the world.

    A tourist converts euros into Japanese yen.

    A company in Kenya pays a supplier in China.

    A multinational corporation converts foreign revenue back into its home currency.

    An investment fund buys overseas assets.

    A central bank manages reserves.

    A trader speculates on whether one currency will strengthen against another.

    All of these activities connect in some way to the enormous global foreign exchange market, commonly called the forex or FX market.

    According to the Bank for International Settlements, average over-the-counter foreign-exchange turnover reached approximately $9.6 trillion per day in April 2025, up from about $7.5 trillion in 2022.

    That enormous figure helps explain why forex is commonly described as the world’s largest financial market.

    But size does not mean easy profits.

    Forex trading—particularly leveraged retail trading—can result in substantial losses. Regulators around the world repeatedly warn consumers about excessive leverage, unregulated platforms, unrealistic profit promises and fraudulent forex schemes.

    This guide therefore has a different objective from the countless advertisements promising to teach you how to “get rich trading forex.”

    The objective is to help you understand:

    How the forex market works.
    Why currencies move.
    How currency pairs are quoted.
    How brokers operate.
    How leverage and margin work.
    How charts are interpreted.
    How traders analyze markets.
    How risk should be managed.
    How scams can be recognized.
    How to research regulation before depositing money.

    Learning should come before trading.

    And protecting your capital should come before chasing profits.

    1. What Is Forex Trading?

    Forex stands for foreign exchange.

    Foreign exchange involves exchanging one currency for another.

    If you travel from one country to another and exchange your home currency for the destination’s currency, you have participated in foreign exchange.

    Forex trading takes the concept further.

    A trader takes a position based on how the value of one currency may change relative to another.

    Currencies therefore trade in pairs.

    Examples include:

    EUR/USD — Euro vs. U.S. dollar

    USD/JPY — U.S. dollar vs. Japanese yen

    GBP/USD — British pound vs. U.S. dollar

    AUD/USD — Australian dollar vs. U.S. dollar

    USD/CAD — U.S. dollar vs. Canadian dollar

    A trader is not simply asking:

    “Will the euro rise?”

    The question is:

    “Will the euro strengthen or weaken relative to the other currency in this pair?”

    That relationship is fundamental to understanding forex.

    2. A Brief History of the Foreign Exchange Market

    Currency exchange is centuries old, but the modern forex market developed through major changes in the international monetary system.

    One important twentieth-century framework was the Bretton Woods system, established during the 1940s.

    Under that international monetary arrangement, currencies operated within a system of fixed exchange-rate relationships centered on the U.S. dollar, while the dollar itself had a defined relationship with gold.

    That system eventually broke down.

    By March 1973, the world’s major currencies had moved toward floating exchange rates, marking the end of the Bretton Woods fixed-rate regime.

    You can explore international monetary and financial history through the Bank for International Settlements.

    Technology later transformed the market.

    Electronic brokerage systems expanded in the 1990s, followed by increasingly sophisticated electronic and algorithmic trading.

    Today the forex market connects:

    Banks
    Central banks
    Investment funds
    Corporations
    Asset managers
    Hedge funds
    Trading firms
    Governments
    Brokers
    Individual traders

    across the world.

    3. Why Forex Is the World’s Largest Financial Market

    The forex market is enormous because currencies sit at the center of international economic activity.

    Currencies are needed for:

    International trade
    Cross-border investment
    Tourism
    Foreign debt payments
    Corporate transactions
    Government activity
    Currency reserves
    Portfolio management
    Hedging
    Speculation

    The Bank for International Settlements conducts its comprehensive Triennial Central Bank Survey to measure activity across global FX markets.

    The BIS reported that average OTC FX turnover reached approximately:

    $9.6 trillion per day in April 2025.

    The U.S. dollar remained dominant, appearing on one side of roughly 89% of FX transactions measured in that survey.

    But forex is truly global.

    Emerging-market currencies collectively reached a record share of global FX turnover in 2025, according to BIS analysis.

    This means forex is not merely a market for the dollar, euro, yen and pound.

    It connects economies throughout:

    Africa
    Asia
    Europe
    North America
    South America
    Oceania
    The Middle East

    4. Understanding Currency Pairs

    Forex prices are quoted as currency pairs.

    Consider:

    EUR/USD = 1.1500

    EUR is the base currency.

    USD is the quote currency.

    The quote means approximately:

    1 euro = 1.15 U.S. dollars

    Now consider:

    USD/JPY = 150.00

    This means approximately:

    1 U.S. dollar = 150 Japanese yen

    When EUR/USD rises, the euro has strengthened relative to the dollar, or the dollar has weakened relative to the euro—or some combination of both.

    Forex is always relative.

    5. Major Currency Pairs

    “Major” pairs generally involve the U.S. dollar paired with another heavily traded currency.

    Common examples include:

    EUR/USD
    USD/JPY
    GBP/USD
    USD/CHF
    AUD/USD
    USD/CAD
    NZD/USD

    These markets tend to have substantial trading activity.

    The BIS foreign-exchange statistics provide detailed international information about currencies and FX activity.

    6. Minor or Cross-Currency Pairs

    Currency pairs that do not include the U.S. dollar are often called crosses or, in retail terminology, minor pairs when they involve major currencies.

    Examples include:

    EUR/GBP
    EUR/JPY
    GBP/JPY
    AUD/JPY
    EUR/AUD

    Crosses allow traders and businesses to consider relationships between currencies without directly trading against the dollar.

    7. Exotic Currency Pairs

    An exotic pair generally combines a major currency with the currency of a smaller or emerging economy.

    Depending on broker availability and jurisdiction, examples might involve currencies such as:

    Mexican peso
    South African rand
    Turkish lira
    Brazilian real
    Indian rupee
    Thai baht

    These currencies can have wider spreads, lower liquidity or greater volatility than heavily traded major pairs.

    “Exotic” does not mean bad.

    It means the market characteristics can differ substantially.

    Beginners should understand those differences before trading them.

    8. How Currency Prices Move

    Currency values are influenced by supply and demand.

    When demand for one currency rises relative to another, its exchange rate can strengthen.

    When demand falls, it can weaken.

    But what changes demand?

    Many things:

    Interest rates
    Inflation
    Economic growth
    Employment
    Trade
    Capital flows
    Government policy
    Central-bank policy
    Political developments
    Commodity prices
    Investor sentiment
    Market expectations

    Forex traders therefore study economies as well as charts

    9. Exchange Rates Explained

    An exchange rate tells you how much one currency is worth relative to another.

    Suppose:

    EUR/USD = 1.1000

    Later:

    EUR/USD = 1.1200

    The euro has appreciated relative to the dollar over that interval.

    Alternatively:

    EUR/USD = 1.0800

    The euro has depreciated relative to the dollar.

    The Bank for International Settlements exchange-rate statistics and its broader statistics portal provide international exchange-rate datasets.

    Central banks around the world also publish currency and economic information.

    10. Bid Price vs. Ask Price

    Forex quotations commonly contain two prices.

    Suppose EUR/USD displays:

    Bid: 1.1000

    Ask: 1.1002

    The bid is generally the price at which the dealer is prepared to buy the base currency from you.

    The ask is generally the price at which the dealer is prepared to sell it to you.

    The difference between them is the:

    Spread

    Here:

    1.1002 − 1.1000 = 0.0002

    For a pair quoted to four decimal places in the conventional way, that would commonly represent approximately 2 pips.

    11. Spreads and Commissions

    Trading is not free.

    Depending on the broker and account structure, costs may include:

    Spreads
    Commissions
    Financing/rollover charges
    Conversion charges
    Withdrawal charges
    Other account fees

    A broker advertising “zero commission” does not necessarily mean zero trading cost.

    The cost may instead be incorporated into the spread or elsewhere.

    Always read the broker’s full fee schedule.

    12. What Is a Pip?

    A pip is a commonly used unit for describing small movements in currency prices.

    For many currency pairs:

    1 pip = 0.0001

    For example:

    EUR/USD moves from:

    1.1000 → 1.1001

    That is a one-pip movement under the conventional quotation.

    Pairs involving the Japanese yen are commonly quoted differently, so the conventional pip location is typically different as well.

    Some brokers also quote fractional pips.

    13. What Is Lot Size?

    Lot size describes the size of a forex position.

    Retail platforms may use terms such as:

    Standard lot
    Mini lot
    Micro lot

    A commonly used convention is:

    Standard lot = 100,000 currency units

    Mini lot = 10,000 currency units

    Micro lot = 1,000 currency units

    But never assume every platform uses exactly the same terminology or contract specifications.

    Check the broker’s documentation.

    The larger your position, the greater the potential monetary impact of a price movement.

    14. Who Participates in the Forex Market?

    Forex is much larger than retail trading.

    Major participants include:

    Commercial Banks

    Banks facilitate international transactions and trade currencies for clients and themselves.

    Central Banks

    Institutions such as the:

    European Central Bank

    Bank of England

    Bank of Japan

    U.S. Federal Reserve

    and central banks throughout Africa, Asia, Latin America, the Middle East and Oceania can strongly influence currencies through monetary policy.

    Corporations

    International businesses exchange currencies when paying employees, suppliers, customers and investors across borders.

    Institutional Investors

    Pension funds, asset managers, insurance companies and investment funds may hold assets in multiple currencies.

    Hedge Funds and Trading Firms

    Professional firms may trade currencies for hedging, arbitrage or speculation.

    Retail Traders

    Individuals participate through brokers and trading platforms.

    Retail trading represents only one part of the enormous global market.

    15. Understanding Forex Trading Sessions

    Forex trading follows global financial centers.

    Because major centers operate in different time zones, FX activity continues across much of the working week.

    Four sessions are commonly discussed in retail forex education:

    Sydney Session

    Associated with the opening of the Asia-Pacific trading day.

    Tokyo Session

    Important for Japanese yen and broader Asian market activity.

    London Session

    London remains the world’s largest FX trading center.

    New York Session

    New York is another major global financial center and overlaps with London for part of the trading day.

    The London-New York overlap can be particularly active because two major centers are operating simultaneously.

    Exact trading hours can vary by broker, instrument, daylight-saving changes and local holidays.

    16. How Forex Brokers Work

    Retail traders usually access forex markets through brokers or dealers.

    Depending on jurisdiction and business model, the provider may:

    Provide the trading platform
    Display bid and ask prices
    Execute orders
    Act as counterparty
    Route or hedge transactions
    Provide leverage
    Hold customer funds

    The exact relationship matters.

    The U.S. Commodity Futures Trading Commission warns retail customers to understand that in certain OTC forex arrangements, they trade against the dealer on the dealer’s platform.

    Different jurisdictions regulate retail forex differently.

    Therefore:

    Do not assume a broker’s business model or protections are identical worldwide.

    17. Leverage Explained

    Leverage allows a trader to control a position larger than the money committed to support it.

    Suppose you control:

    $10,000

    of currency exposure using:

    $500

    of your own capital.

    You have substantial leveraged exposure.

    Leverage magnifies:

    Potential gains AND potential losses.

    This is one of the most important concepts in forex.

    A small market movement can create a much larger percentage change in your account.

    The CFTC forex advisory warns that leverage amplifies both gains and losses and that, depending on the arrangement and protections applicable, losses can potentially exceed the original deposit.

    Never choose the maximum available leverage simply because the broker offers it.

    18. Margin Explained

    Margin is the amount of money required to open or maintain a leveraged position.

    For example, if a provider requires 2% margin for a $100,000 position:

    Required margin = $2,000

    But the market exposure remains:

    $100,000

    not $2,000.

    That distinction explains why leveraged trading can become dangerous.

    If losses reduce your available funds too far, the broker may require additional funds or automatically close positions, depending on its rules and applicable regulation.

    Always understand:

    Initial margin
    Maintenance requirements
    Margin close-out rules
    Negative-balance protections
    Liquidation procedures

    before trading.

    19. Why Leverage Rules Differ Around the World

    Forex regulation is not globally uniform.

    For example, the UK’s Financial Conduct Authority applies retail protections to CFDs and rolling spot forex, including leverage restrictions and other measures.

    Other countries have their own frameworks.

    A broker offering 500:1 or 1,000:1 leverage from one jurisdiction may not be permitted to offer the same terms to retail clients somewhere else.

    This is why choosing a broker based solely on leverage is a serious mistake.

    More leverage does not automatically mean a better broker.

    20. Understanding Long and Short Positions

    If you believe the base currency will strengthen against the quote currency, you might take a long position.

    If you expect it to weaken, you might take a short position.

    For example:

    You buy EUR/USD at:

    1.1000

    and later close at:

    1.1100

    The market moved in the direction of the long position.

    But if it falls to:

    1.0900

    the position moves against you.

    Trading is always uncertain.

    The fact that your analysis appears logical does not guarantee the market will follow it.

    21. Reading Candlestick Charts

    Candlestick charts display price activity across chosen periods.

    Each candle generally shows:

    Open
    High
    Low
    Close

    A candle might represent:

    1 minute
    5 minutes
    1 hour
    4 hours
    1 day
    1 week

    depending on the chart.

    Candlesticks can help traders visualize:

    Price direction
    Volatility
    Momentum
    Rejection
    Trading ranges

    But no candlestick pattern can predict the future with certainty.

    Charts organize information.

    They do not eliminate uncertainty.

    22. Technical Analysis Basics

    Technical analysis studies price and market behavior.

    Common tools include:

    Support and resistance
    Trendlines
    Moving averages
    Relative Strength Index (RSI)
    MACD
    Price patterns
    Volume-related information where relevant
    Volatility measures

    Support

    An area where buying interest has previously appeared.

    Resistance

    An area where selling pressure has previously appeared.

    Trend

    A general direction in price.

    Markets may move:

    Upward
    Downward
    Sideways

    Technical analysis is not magic.

    Two skilled traders can look at the same chart and reach different conclusions.

    23. Fundamental Analysis Basics

    Fundamental analysis focuses on economic and financial forces affecting currencies.

    Forex traders may study:

    Interest rates
    Inflation
    Employment
    Economic growth
    Trade balances
    Government finances
    Central-bank policy
    Political developments

    A currency is connected to the economy and monetary system behind it.

    Therefore, understanding macroeconomics can be useful for understanding forex.

    Useful global sources include:

    International Monetary Fund

    World Bank

    Bank for International Settlements

    OECD

    as well as official national statistical agencies and central banks

    24. Economic News That Can Move Forex

    Currencies can move sharply around economic announcements.

    Important releases can include:

    Inflation data
    Employment reports
    GDP
    Retail sales
    Manufacturing indicators
    Interest-rate decisions
    Central-bank statements

    Suppose inflation is unexpectedly high.

    Traders may change their expectations about future interest rates.

    That can influence bond markets, investment flows and currency demand.

    But market reactions are not always obvious.

    A currency can sometimes fall even after apparently positive economic news because traders had expected even stronger numbers.

    Forex markets often react to:

    Actual result vs. market expectation

    rather than simply whether the headline appears good or bad.

    25. Central Banks Matter Enormously

    Central banks influence currency markets through monetary policy.

    They may adjust:

    Policy interest rates
    Liquidity conditions
    Asset-purchase programs
    Reserve requirements
    Communication about future policy

    Central banks may also intervene directly or indirectly in foreign-exchange markets under certain circumstances.

    If you trade a currency, learn about the central bank responsible for it.

    Don’t rely solely on social-media summaries.

    Read original central-bank announcements whenever possible.

    26. Technical Analysis vs. Fundamental Analysis

    Technical traders emphasize:

    What is price doing?

    Fundamental traders emphasize:

    Why might the currency be moving?

    Many market participants combine both.

    For example:

    Fundamental analysis may suggest a currency has supportive economic conditions.

    Technical analysis may help identify possible entry, exit or invalidation levels.

    Neither approach guarantees success.

    Risk management remains necessary regardless of analytical method

    27. Trading Psychology

    Trading is not purely mathematical.

    Money creates emotion.

    Common psychological problems include:

    Fear
    Greed
    Overconfidence
    Impatience
    Revenge trading
    Fear of missing out
    Refusal to accept losses

    Imagine losing three trades.

    You become angry.

    You double the size of the fourth trade because you want your money back immediately.

    That is revenge trading.

    The fourth trade is no longer based purely on analysis.

    Emotion has taken control.

    A trader’s greatest risk is sometimes not the market.

    It is the trader’s own behavior.

    28. Risk Management: The Skill Beginners Must Learn First

    Many beginners focus on:

    How much can I make?

    Experienced risk thinking begins with:

    How much can I lose if I am wrong?

    Before entering a trade, consider:

    Entry price
    Position size
    Potential loss
    Exit level
    Risk/reward relationship
    Account exposure

    Never risk essential money.

    Do not trade with:

    Rent money
    Food money
    Emergency savings
    Medical funds
    Borrowed money
    Money needed for family obligations

    Capital protection must come before profit seeking.

    29. Position Sizing

    Suppose you have:

    $5,000

    in trading capital.

    Risking $1,000 on one speculative position means one bad decision could remove:

    20% of your account.

    Recovering from large losses becomes increasingly difficult.

    For example, after a 50% loss, you need a 100% gain on the remaining capital simply to return to the starting value.

    Position sizing therefore matters enormously.

    There is no universal percentage that is appropriate for every trader.

    The central principle is:

    A single trade should not be capable of destroying your financial future.

    30. Stop-Loss Orders

    Suppose a hypothetical setup risks:

    $50

    for a potential gain of:

    $100

    The theoretical reward is twice the amount at risk.

    But a favorable risk/reward ratio alone does not make a strategy profitable.

    You must also consider the probability of winning, trading costs and actual execution.

    Risk management combines:

    Position size + Probability + Loss size + Potential reward + Trading costs

    32. Keep a Trading Journal

    A trading journal can record:

    Date
    Currency pair
    Entry
    Exit
    Position size
    Reason for trade
    Risk
    Result
    Market conditions
    Emotional state
    Lessons

    After 50 or 100 demo trades, patterns may become visible.

    Perhaps you trade better during particular conditions.

    Perhaps your losses increase after economic announcements.

    Perhaps you repeatedly violate your own rules.

    Without records, you may never notice.

    33. Demo Trading Accounts

    A demo account uses simulated money rather than real capital.

    For beginners, this can be extremely useful.

    Use a demo account to learn:

    Order placement
    Chart navigation
    Position sizing
    Stops
    Targets
    Platform mechanics
    Trading plans
    Journal keeping

    Do not rush through demo trading simply because simulated profits feel less exciting.

    The purpose is education.

    A useful progression is:

    Learn → Observe → Demo Trade → Journal → Review → Improve

    Only then should someone even consider whether real-money trading is appropriate.

    34. Demo Trading Is Not Identical to Real Trading

    Demo trading has limitations.

    When fake money is at risk, emotional pressure is different.

    Losing $1,000 of virtual money is not psychologically equivalent to losing $1,000 you worked months to save.

    Live execution and market conditions may also differ.

    Therefore:

    Demo success does not guarantee live-trading success.

    Treat demo trading as education, not proof that future profits are guaranteed.

    35. Develop a Trading Plan Before Trading Real Money

    A trading plan should answer:

    Which currency pairs will I study?
    Which timeframes?
    What conditions create a setup?
    What invalidates the setup?
    How will position size be determined?
    When will I avoid trading?
    How will results be recorded?

    If your strategy is:

    “I will look at the chart and see what happens,”

    you do not have a strategy.

    Rules reduce emotional decision-making.

    36. Common Forex Beginner Mistakes

    Beginners frequently make predictable errors.

    Mistake 1: Using Excessive Leverage

    A small market movement can produce a disproportionately large loss.

    Mistake 2: Trading Without Understanding Margin

    Beginners may focus on potential profit while ignoring liquidation risk.

    Mistake 3: Trading Without a Plan

    Random decisions create inconsistent results.

    Mistake 4: Risking Too Much on One Trade

    One bad position can damage the account severely.

    Mistake 5: Revenge Trading

    Increasing risk after losses can compound the damage.

    Mistake 6: Overtrading

    More trades do not necessarily produce more profit.

    Mistake 7: Ignoring Economic News

    Unexpected volatility can destroy poorly managed positions.

    Mistake 8: Copying Social-Media Signals Blindly

    You may know nothing about the provider’s incentives, risk, history or competence.

    Mistake 9: Believing Guaranteed-Profit Claims

    No legitimate trader can guarantee that markets will produce a particular profit.

    Mistake 10: Choosing a Broker Based Only on Bonuses or Leverage

    Regulation, withdrawals, fees, execution and consumer protection matter much more.

    37. Forex Scams and How to Avoid Them

    Forex scams exist worldwide.

    Common schemes include:

    Fake brokers
    Fake trading platforms
    Guaranteed-return programs
    Account-management scams
    Signal scams
    Copy-trading fraud
    Fake investment groups
    Romance-investment scams
    Clone firms
    Social-media impersonators

    The UK’s Financial Conduct Authority warns that fraudulent forex firms may promise very high or guaranteed returns and sometimes initially show apparent profits to gain a victim’s trust.

    The U.S. Commodity Futures Trading Commission similarly warns that many forex frauds begin through social media, messaging applications, dating platforms or unsolicited communications.

    Major warning signs include:

    “Guaranteed daily profit.”

    “Zero risk.”

    “Send money now.”

    “Our secret AI bot never loses.”

    “Pay another fee to unlock your withdrawal.”

    “We are regulated everywhere.”

    Verify these claims independently.

    38. Never Pay More Money Just to Release Your Withdrawal

    This deserves special attention.

    A fraudulent platform may show:

    Account Balance: $25,000

    Then when you request a withdrawal, it demands:

    $2,000 tax

    then:

    $1,500 processing fee

    then:

    $3,000 account verification

    The numbers on the screen may be fabricated.

    The CFTC specifically warns about fraudulent dealers refusing withdrawals unless customers send additional money for supposed commissions, taxes or account-status requirements.

    If someone keeps demanding additional deposits to release your money, treat it as a major warning sign.

    39. Choosing a Regulated Forex Broker

    Do not begin by asking:

    “Which broker offers the highest leverage?”

    Begin with:

    “Who regulates this broker in my country?”

    Then verify it independently.

    Do not rely on a regulator’s logo displayed on the broker’s website.

    Visit the regulator’s official database.

    Check:

    Legal company name
    License/registration number
    Authorized activities
    Website/domain
    Contact information
    Warnings
    Disciplinary history

    40. How to Check Forex Regulation Around the World

    There is no single regulator controlling forex everywhere.

    Depending on where you live, supervision may involve securities, derivatives, financial-market or central-bank authorities.

    Useful official resources include:

    IOSCO — the International Organization of Securities Commissions, whose membership and resources can help users identify securities regulators internationally.

    IOSCO Investor Alerts Portal — aggregates alerts submitted by participating regulators about unauthorized firms.

    Financial Conduct Authority — United Kingdom.

    ASIC — Australia.

    MAS — Singapore financial institutions directory.

    CFTC — United States derivatives/forex resources.

    NFA BASIC — U.S. registration and disciplinary research.

    Other countries have their own authorities.

    The principle is universal:

    Find your country’s official regulator → Search its register → Verify the exact company → Verify the exact website → Check warnings → Only then consider depositing money.

    41. Offshore Does Not Automatically Mean Better

    Some brokers market themselves globally from jurisdictions with different regulatory frameworks.

    A trader may think:

    “This offshore broker gives me 1:1000 leverage, so it must be better.”

    But ask:

    What happens if it refuses my withdrawal?

    Which regulator can I contact?

    Are client funds segregated?

    Is negative-balance protection available?

    What legal rights do I have?

    Where would a dispute be resolved?

    Trading conditions are only one part of broker selection.

    Legal protection matters too.

    42. A Beginner’s Forex Learning Roadmap

    Stage 1 — Learn Currency Basics

    Understand:

    Currency pairs
    Exchange rates
    Bid/ask
    Spreads
    Pips
    Lots

    Stage 2 — Learn Market Structure

    Understand:

    Banks
    Central banks
    Brokers
    Institutions
    Trading sessions

    Stage 3 — Learn Risk

    Study:

    Leverage
    Margin
    Position sizing
    Stop losses
    Drawdowns

    Stage 4 — Learn Analysis

    Study:

    Charts
    Candlesticks
    Technical analysis
    Fundamental analysis
    Economic news

    Stage 5 — Demo Trade

    Practice without risking real money.

    Stage 6 — Journal Your Results

    Document mistakes and patterns.

    Stage 7 — Research Regulation

    Learn the legal framework where you live.

    Stage 8 — Decide Whether Trading Is Appropriate

    Not everyone needs to become a forex trader.

    Learning about currencies can still improve your understanding of the global economy.

    43. Forex Trading vs. Long-Term Investing

    Forex trading and long-term investing are not identical.

    Forex trading often focuses on relative movements between currencies.

    Long-term investing may involve owning productive assets such as:

    Stocks
    Bonds
    Businesses
    Real estate

    depending on the investor’s goals.

    Do not confuse short-term currency speculation with a complete wealth-building plan.

    A financially responsible person can understand forex while still deciding that diversified long-term investing is more appropriate for most of their capital

    44. The Most Important Forex Lesson

    The most important lesson is not:

    Which indicator should I use?

    It is not:

    Which currency pair will rise tomorrow?

    And it is definitely not:

    How can I turn $100 into $100,000?

    The most important lesson is:

    Markets are uncertain.

    Once you accept uncertainty, risk management becomes logical.

    You stop trying to be right every time.

    You begin thinking about:

    Capital preservation
    Probability
    Position sizing
    Discipline
    Consistency
    Long-term survival

    That mindset is more valuable than any supposed secret indicator.

    Frequently Asked Questions

    Is Forex Trading Legal?

    Forex trading is legal in many countries, but the rules governing brokers, leverage, derivatives and retail participation vary significantly.

    Check your country’s financial regulator before opening an account.

    Is Forex Trading Safe?

    Forex itself is a legitimate global financial market.

    That does not mean retail forex trading is safe.

    Leveraged trading can produce significant losses, and unregulated or fraudulent providers create additional risks.

    How Much Money Do I Need to Start Forex Trading?

    Minimum deposits vary between brokers.

    But the fact that a broker allows you to open an account with a small amount does not mean you are financially prepared to trade.

    Education, emergency savings, risk capacity and financial stability matter more than the advertised minimum deposit.

    Can I Start With $100?

    Some brokers may permit small accounts.

    However, a small account combined with high leverage can encourage excessive risk.

    The goal should not be:

    “How quickly can I turn $100 into thousands?”

    The better question is:

    “How can I learn without damaging my financial future?”

    Can Forex Make You Rich?

    It is possible to make money trading currencies.

    It is also possible to lose substantial amounts.

    No responsible educational source should promise that forex will make you rich.

    Treat guaranteed-return claims as warning signs.

    Is Forex Gambling?

    Forex trading is a financial-market activity, but behavior can become gambling-like when someone trades without analysis, risk controls or discipline, particularly when using excessive leverage.

    Simply calling an activity “trading” does not automatically make reckless speculation responsible.

    Which Currency Pair Is Best for Beginners?

    There is no universally best currency pair.

    Highly traded major pairs can offer greater liquidity and often tighter spreads, but they still carry market risk.

    Beginners should first understand how pairs behave rather than searching for a guaranteed winner.

    What Is the Best Forex Strategy?

    There is no strategy guaranteed to work under all market conditions.

    A strategy must be evaluated based on:

    Risk
    Costs
    Consistency
    Market conditions
    Execution
    Drawdowns
    Discipline

    Be skeptical of anyone selling a “100% winning strategy.”

    Can AI Predict Forex Markets?

    AI can analyze data, identify patterns and assist with research.

    It cannot guarantee future currency prices.

    Markets react to unexpected economic, political and financial events.

    Claims that an AI forex robot “never loses” should be treated with extreme skepticism.

    Are Forex Signals Reliable?

    Quality varies enormously.

    Some signal providers may use genuine analysis.

    Others may have poor track records, hidden incentives or fraudulent intentions.

    Never surrender responsibility for risk simply because someone sends buy and sell instructions.

    What Is the Difference Between Forex and Crypto?

    Forex involves national currencies such as:

    USD
    EUR
    JPY
    GBP
    CHF
    AUD

    Cryptocurrency markets involve digital assets such as Bitcoin and other tokens.

    Their market structures, regulation, custody arrangements, volatility and risks can differ significantly.

    What Is the Difference Between Forex and Stocks?

    Buying stock generally means acquiring an ownership interest in a company.

    Forex trading involves taking positions on the relative value of currencies.

    They are fundamentally different financial activities.

    Should Beginners Use High Leverage?

    High leverage can magnify losses dramatically.

    A broker offering extremely high leverage does not mean using it is wise.

    Understanding risk should come before maximizing exposure.

    Should I Pay Someone to Trade Forex for Me?

    Be extremely cautious.

    Managed-account fraud is a known problem.

    Verify authorization, regulation, custody arrangements, fees and the identity of everyone involved before transferring money.

    Never rely solely on screenshots or social-media testimonials.

    How Can I Tell Whether a Forex Broker Is Genuine?

    Verify the broker through the official regulator’s database.

    Do not click a “regulator” link supplied by an unknown broker and assume it is authentic.

    Independently locate the regulator’s official website and check the company’s:

    Name
    License
    Domain
    Address
    Permissions
    Warnings

    Clone firms sometimes impersonate legitimate regulated companies.

    Where Can I Learn More About the Global Forex Market?

    Reliable starting points include:

    Bank for International Settlements — global FX statistics, market structure and central-bank research.

    International Monetary Fund — exchange rates, international economics and monetary systems.

    World Bank — global economic data.

    IOSCO — international securities-regulatory resources.

    CFTC Learn & Protect — derivatives and forex risk education.

    FCA Consumer Information — consumer protection and financial-scam education.

    The best forex education combines market knowledge with skepticism, risk awareness and reliable sources.

    Conclusion

    Forex is one of the most fascinating parts of the global financial system.

    Every currency tells a story about an economy.

    Interest rates matter.

    Inflation matters.

    Economic growth matters.

    International trade matters.

    Central banks matter.

    Politics can matter.

    Investor expectations matter.

    And because currencies connect economies, forex provides a window into how the global financial system operates.

    But understanding forex and successfully trading leveraged forex are two very different things.

    A beginner should therefore follow a disciplined sequence:

    Learn first.
    Understand currency pairs.
    Understand exchange rates.
    Learn pips and lot sizes.
    Understand spreads and fees.
    Study leverage.
    Understand margin.
    Learn charts.
    Study economics.
    Practice on a demo account.
    Develop risk rules.
    Keep a journal.
    Research regulation.
    Verify your broker.
    Protect your capital.

    Do not rush because someone on social media shows a luxury car.

    Do not increase leverage because you want faster profits.

    Do not send money to someone promising guaranteed returns.

    Do not believe an AI bot can eliminate market risk.

    Do not assume a broker is regulated simply because its website displays an impressive badge.

    Forex trading is not a shortcut around financial education.

    It requires more education.

    For the global beginner, the strongest starting principle is simple:

    Understand the market before risking your money—and understand the risk before thinking about the reward.
  • How Compound Interest Can Make You Rich Even If You Start Small

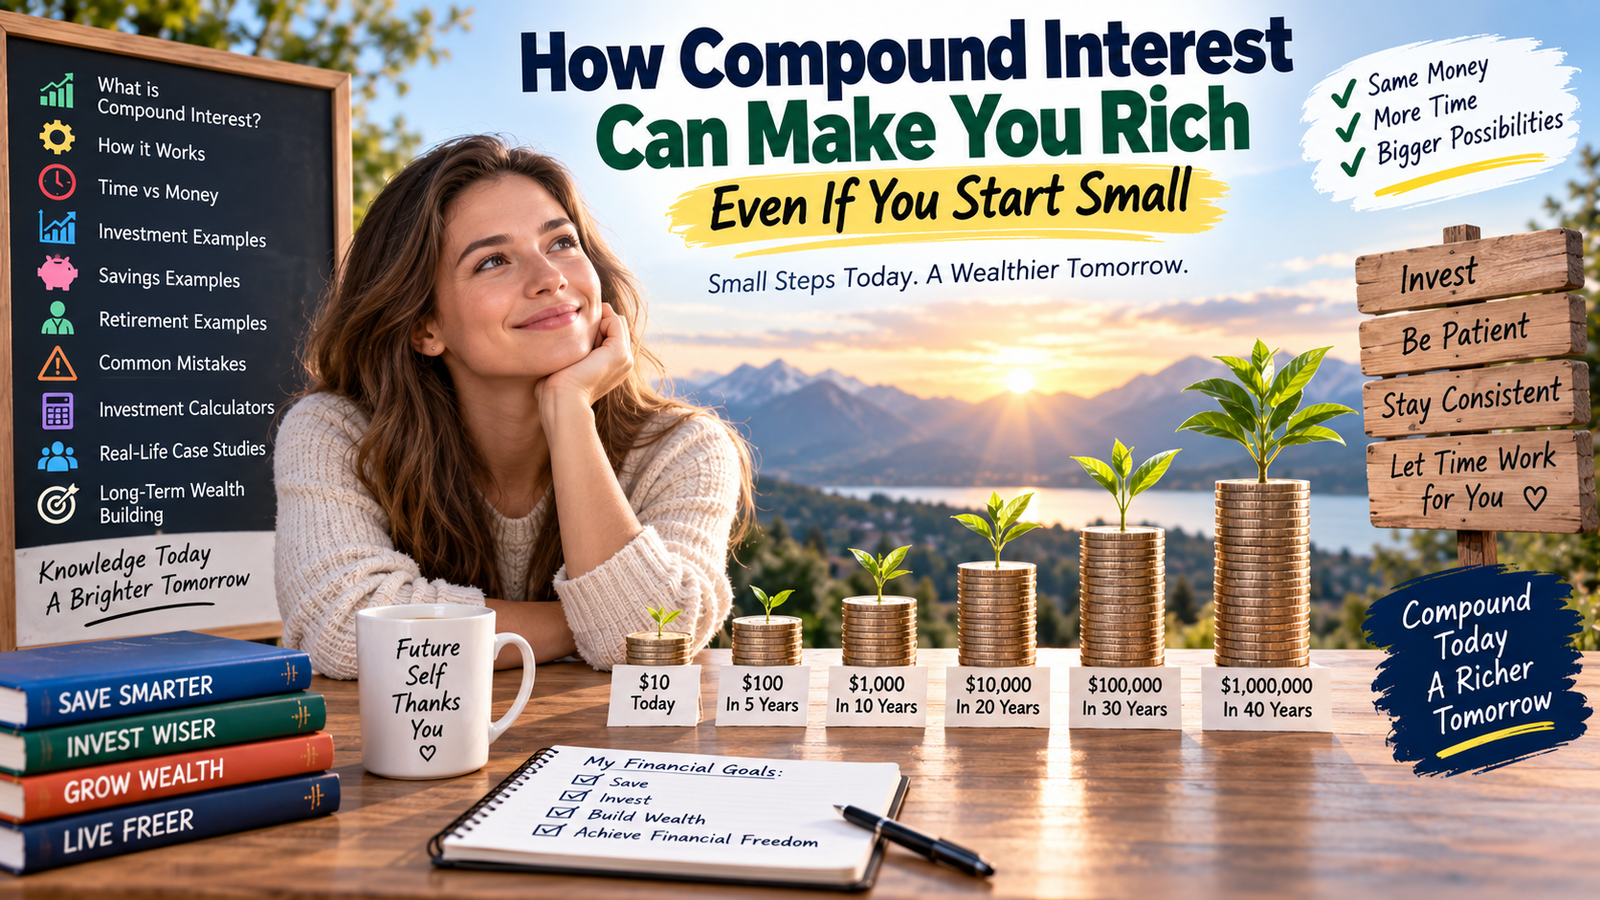
    How Compound Interest Can Make You Rich Even If You Start Small

    How Small Savings and Investments Can Grow Into Significant Long-Term Wealth Through Time and Consistency

    Introduction

    You Don’t Need to Start Rich to Build Wealth

    One of the biggest misconceptions about wealth building is that you need a large amount of money before investing becomes worthwhile.

    You don’t.

    Starting with $10, $50, $100 or $500 may seem insignificant when compared with the large investment portfolios discussed in financial media. But when money is invested consistently and allowed to grow over many years, something powerful can happen: compound growth.

    Compound interest means you can potentially earn returns not only on the money you originally saved or invested, but also on previous interest or investment returns.

    This creates a snowball effect.

    At first, progress can appear frustratingly slow. As time passes, however, the growth generated by your accumulated money can become increasingly important.

    The U.S. Securities and Exchange Commission’s Investor.gov provides a compound-interest calculator that demonstrates how savings can potentially grow over time, while the Consumer Financial Protection Bureau provides educational resources for establishing stronger saving habits.

    The lesson is simple:

    You don’t necessarily need a large starting amount. You need consistency, reasonable returns, and—most importantly—time.

    What Is Compound Interest?

    Compound interest is interest calculated on your original principal plus previously accumulated interest.

    Imagine depositing $1,000 into an account earning a hypothetical 5% annually.

    After the first year:

    $1,000 × 5% = $50

    Your balance becomes:

    $1,050

    If the money remains in the account, the second year’s interest is calculated on $1,050 rather than only the original $1,000.

    At 5%, that would produce:

    $52.50

    Your balance becomes:

    $1,102.50

    The extra $2.50 may appear insignificant.

    But over many compounding periods, the difference can become much larger.

    Investor.gov explains the concept through its educational material on compound interest, and its compound interest calculator allows investors to test different hypothetical scenarios.

    The fundamental principle is:

    Your money can potentially begin earning money on money it previously earned.

    How Does Compound Interest Work?

    A simplified annual compounding formula is:

    Future Value = Principal × (1 + Rate)^Time

    Suppose you invest $5,000 and hypothetically earn 7% annually for 20 years without adding additional money.

    The calculation would be approximately:

    $5,000 × (1.07)^20 = $19,348

    Your original $5,000 would have potentially grown to approximately $19,348.

    That does not mean every investment will return 7%. Investment returns fluctuate and can be negative. The example simply demonstrates the mathematics of compounding.

    The Investor.gov compound-interest calculator lets readers experiment with principal, contributions, interest rates and time, while FINRA’s investing resources explain important concepts investors should understand before putting money at risk.

    Time vs. Money: Why Starting Early Can Matter More Than Starting Big

    One of the most important lessons about compound growth is that time can compensate for a relatively small beginning.

    Consider two hypothetical investors.

    Investor A: Starts at Age 20

    Investor A invests $200 every month from age 20 until age 60.

    Total contributions:

    $200 × 12 × 40 = $96,000

    At a hypothetical 7% annual return compounded monthly, the portfolio could grow to roughly $525,000.

    Investor B: Starts at Age 40

    Investor B also invests $200 monthly but starts at age 40 and continues until 60.

    Total contributions:

    $200 × 12 × 20 = $48,000

    At the same hypothetical return, the portfolio could grow to roughly $104,000.

    The difference isn’t simply because Investor A contributed more.

    Investor A’s earliest contributions had decades longer to potentially compound.

    This illustrates why the Investor.gov saving and investing resources encourage understanding long-term investing, while the FINRA investor education center provides resources for making informed investment decisions.

    Starting early can be more powerful than waiting until you have a large amount of money.

    Small Monthly Investments Can Become Significant

    Suppose someone begins investing $100 per month at age 25.

    Assume, purely for illustration, an average annual return of 7%.

    If that person continues for 40 years, their personal contributions total:

    $48,000

    Yet the hypothetical investment balance could eventually reach approximately $262,000.

    Increase the contribution to $300 monthly under the same hypothetical assumptions, and the eventual balance could approach approximately $787,000.

    Again, these are illustrations—not guaranteed investment outcomes.

    Actual results depend on market performance, investment fees, taxes, contribution timing and other factors.

    The lesson is not that 7% is guaranteed.

    The lesson is that:

    Small Amount + Consistency + Return + Time = Potentially Significant Growth

    Compound Growth in a Savings Account

    Compounding does not apply only to stock-market investments.

    Interest-bearing savings accounts can also compound.

    Suppose you deposit $10,000 into a savings account earning a hypothetical 4% annually and leave the interest in the account.

    After one year, approximately:

    $10,400

    After five years:

    $12,167

    After ten years:

    $14,802

    The exact result depends on the account’s rate and compounding frequency.

    Savings accounts generally offer lower expected returns than riskier investments, but they can be appropriate for emergency funds and shorter-term financial goals where protecting principal and maintaining liquidity are priorities.

    The CFPB savings resources provide information about developing savings strategies, while U.S. readers can learn about insured bank deposits from the Federal Deposit Insurance Corporation.

    Readers outside the United States should check the deposit-protection rules and regulated financial institutions in their own countries.

    Compound Growth and Retirement

    etirement planning is one of the clearest examples of why compounding matters.

    Imagine a 25-year-old contributes $250 monthly toward long-term retirement investments.

    At a hypothetical 7% annual return, continuing until age 65 could potentially produce approximately $656,000.

    Personal contributions would total only:

    $250 × 12 × 40 = $120,000

    Much of the hypothetical difference would come from investment growth and compounding.

    A person who waits until 45 has only 20 years before reaching 65. Achieving a similar result would require dramatically larger contributions or substantially different investment outcomes.

    The Investor.gov retirement toolkit provides educational resources for retirement investors, while FINRA’s retirement resources explain important considerations when preparing financially for retirement.

    The Rule of 72: A Simple Compounding Shortcut

    A popular mental shortcut called the Rule of 72 estimates how long an investment might take to double at a fixed rate.

    Divide 72 by the hypothetical annual return.

    For example:

    72 ÷ 6 = approximately 12 years

    At 6%, money would take roughly 12 years to double.

    At 8%:

    72 ÷ 8 = approximately 9 years

    This is only an approximation, but it illustrates the relationship between returns and time.

    Be careful, however: higher potential returns generally involve greater investment risk. Never select an investment simply because it advertises a high return.

    Investment Example: $50 Per Week

    Suppose you invest $50 every week.

    That is approximately:

    $2,600 per year

    Over 30 years, your direct contributions would total approximately:

    $78,000

    If those contributions achieved a hypothetical long-term return, compound growth could potentially make the final portfolio significantly larger than the amount personally contributed.

    This is why consistency matters.

    Many people wait for a future moment when they expect to have thousands of dollars available to invest.

    That moment may never arrive.

    Starting with manageable recurring contributions can be more effective than endlessly waiting for perfect financial circumstances.

    Savings Example: The Young Worker

    Consider Maya, age 22.

    She earns a modest salary and believes investing is only for wealthy people.

    She decides to begin with $25 per week.

    That equals approximately $100–$110 monthly.

    As her income rises, she gradually increases the amount.

    At 25, she contributes $150 monthly.

    At 30, she increases it to $250.

    At 35, she contributes $400.

    Her greatest advantage isn’t that she started wealthy.

    She didn’t.

    Her advantage is that she established the habit early and increased contributions as her financial capacity improved.

    Retirement Example: Starting at 25 vs. Starting at 35

    Consider two hypothetical people.

    Daniel Starts at 25

    He invests $300 monthly until age 65.

    At a hypothetical 7% annual return, his account could grow to approximately $787,000.

    Michael Starts at 35

    Michael invests the same $300 monthly until age 65.

    At the same hypothetical return, his account could grow to approximately $366,000.

    Daniel had only ten additional years.

    But those ten years gave his earliest contributions significantly more time to compound.

    This demonstrates one of the most important principles in long-term wealth building:

    The cost of waiting can be enormous.

    What If You Are Already 40, 50 or Older?

    Do not interpret the importance of starting early as meaning it is too late to start.

    Starting today still gives your money more time than starting five years from now.

    Someone beginning later can potentially compensate in several ways:

    • Increase contributions
    • Reduce unnecessary expenses
    • Extend the investment horizon
    • Increase income
    • Use appropriate retirement accounts
    • Avoid excessive investment fees
    • Develop additional income sources

    The best time to start may have been years ago.

    The next available opportunity is now.

    Compound Interest Can Also Work Against You

    Compounding has another side.

    Debt can compound too.

    If you carry expensive debt and repeatedly fail to pay it down, interest can accumulate on the outstanding balance.

    This is particularly dangerous with high-interest credit cards and certain short-term loans.

    Instead of your money generating more money for you, interest charges can transfer increasing amounts of your future income to lenders.

    The Consumer Financial Protection Bureau’s credit-card resources provide educational information about credit cards, while the CFPB debt collection and financial education resources can help consumers better understand debt-related issues.

    The goal is to put compounding on your side of the financial equation whenever possible.

    Common Compound-Interest Mistakes

    1. Waiting Until You Earn More

    People frequently say:

    “I’ll start investing when I earn more.”

    Then income rises—and expenses rise with it.

    Start with an affordable amount and increase it gradually.

    2. Expecting Unrealistically High Returns

    Be suspicious of anyone promising extremely high, guaranteed investment returns.

    The Investor.gov fraud resources explain common warning signs of investment fraud, while FINRA BrokerCheck allows U.S. investors to research investment professionals and firms.

    3. Constantly Withdrawing Investments

    Compounding needs time.

    Frequently withdrawing long-term investments interrupts the process and may create taxes, fees or missed growth opportunities.

    4. Ignoring Investment Fees

    Small percentage fees can have large long-term effects.

    The SEC’s Investor Bulletin on fees and expenses explains why investment costs deserve attention.

    5. Taking Too Much Risk

    Compounding cannot help if catastrophic losses destroy your capital.

    Diversification and appropriate risk management matter.

    Investor.gov provides an explanation of diversification, and FINRA offers broader investing guidance.

    Use Compound Interest Calculators Before Setting Goals

    You do not have to calculate decades of compound growth manually.

    Online calculators allow you to experiment with:

    Starting amount
    Monthly contribution
    Estimated return
    Investment period
    Compounding frequency

    The Investor.gov Compound Interest Calculator is a useful starting point.

    You can also explore Investor.gov’s broader collection of financial calculators.

    Try several scenarios.

    What happens if you invest $100 monthly instead of $50?

    What happens if you start five years earlier?

    What if you increase contributions by $50 every year?

    What happens if returns are lower than expected?

    Scenario planning can help transform an abstract financial goal into a practical monthly target.

    Real-Life Case Study 1: Starting Small

    Imagine Anna, age 21, can afford only $50 per month.

    She feels embarrassed because friends online discuss investing thousands.

    But Anna begins anyway.

    After receiving salary increases, she gradually moves from:

    $50 → $100 → $200 → $300 monthly

    Her first $50 contribution wasn’t important because it instantly made her rich.

    It was important because it established the behavior that could continue for decades.

    Her wealth-building engine started early.

    Real-Life Case Study 2: The High Earner Who Waited

    James earns considerably more than Anna.

    But he continually postpones investing.

    At 25, he says he’ll begin at 30.

    At 30, he buys a more expensive vehicle.

    At 35, he upgrades his lifestyle again.

    At 40, he finally begins investing aggressively.

    James may still build substantial wealth because his income allows larger contributions.

    But money invested at 40 does not have the same amount of time to compound before traditional retirement age as money invested at 20 or 25.

    High income is valuable.

    High income combined with time is considerably more powerful.

    Real-Life Case Study 3: The Consistent Family

    Consider a family that automatically saves and invests part of every paycheck.

    They don’t try to predict which investment will become the next global sensation.

    They establish emergency savings, manage expensive debt, contribute regularly to diversified long-term investments and increase contributions whenever household income rises.

    Some years markets perform strongly.

    Other years investments decline.

    They remain focused on their long-term financial plan rather than reacting emotionally to every headline.

    Their primary advantage is not prediction.

    It is discipline and consistency.

    How to Use Compound Growth for Long-Term Wealth Building

    Compound interest becomes most powerful when combined with several other financial habits.

    Start Early

    Give your money as much time as reasonably possible.

    Contribute Consistently

    Automate recurring savings or investments where appropriate.

    Increase Contributions

    Whenever income increases, consider increasing your contribution before lifestyle inflation absorbs the entire raise.

    Reinvest Returns

    Allowing interest, dividends or other investment returns to remain invested can support compounding.

    Diversify

    Avoid depending entirely on one company, industry or speculative asset.

    Keep Costs Reasonable

    Fees reduce the amount of money remaining in your portfolio to compound.

    Avoid Emotional Decisions

    Fear can cause investors to sell during downturns, while greed can encourage buying speculative investments after dramatic price increases.

    Protect Your Financial Foundation

    Maintain appropriate emergency savings so you are less likely to liquidate long-term investments whenever an unexpected expense occurs.

    The Long-Term Wealth Formula

    Sustainable wealth building can be summarized simply:

    Earn → Save → Invest → Reinvest → Compound → Increase Contributions → Repeat

    You don’t need to execute this perfectly.

    You need to continue doing it.

    The first years can feel slow because your contributions create most of the growth.

    Eventually, if investments perform positively over time, investment growth itself can become a much larger part of the portfolio.

    That is when the compounding snowball becomes easier to see.

    A Simple Action Plan to Start Today

    Step 1: Calculate how much you can realistically save every month.

    Step 2: Build an appropriate emergency reserve.

    Step 3: Address expensive consumer debt.

    Step 4: Learn the basics of diversified investing.

    Step 5: Choose regulated financial products appropriate to your country and circumstances.

    Step 6: Automate contributions where possible.

    Step 7: Reinvest investment income when appropriate for your goals.

    Step 8: Increase contributions as your income rises.

    Step 9: Review your progress annually rather than obsessing over daily market movements.

    Step 10: Give your strategy time.

    The process is not glamorous.

    But successful long-term wealth building often isn’t.

    Conclusion

    Start Small, but Give Your Money Time to Grow

    Compound interest teaches one of the most encouraging lessons in personal finance:

    Your starting amount does not have to determine your final destination.

    Someone beginning with $25 or $50 may not feel like an investor.

    But that small beginning establishes something extremely valuable—a habit.

    As income increases, $50 can become $100.

    $100 can become $250.

    $250 can become $500.

    Meanwhile, earlier contributions have more time to potentially generate returns, and those returns can potentially generate additional returns.

    That is the power of compounding.

    Do not mistake the examples in this article for guaranteed investment outcomes. Markets fluctuate, savings rates change, inflation reduces purchasing power, taxes and fees matter, and every investment carries some degree of risk.

    But the fundamental mathematics remains powerful:

    Start early.
    Save consistently.
    Invest intelligently.
    Reinvest.
    Increase your contributions.
    Be patient.

    You do not need to wait until you are rich to begin investing.

    Consistent saving and investing over a long enough period may be one of the ways you build wealth in the first place.

    Educational Disclaimer: This article provides general financial education and does not constitute individualized financial, investment, retirement, tax or legal advice. Hypothetical returns are illustrations only and are not guaranteed. Investments can lose value, including principal. Financial products, taxes and regulations vary by country.

  • Why Saving Is the Foundation of Wealth: A Complete Step-by-Step Guide for Beginners (Even on a Small Income)

    Why Saving Is the Foundation of Wealth: A Complete Step-by-Step Guide for Beginners (Even on a Small Income)

    Learn Practical Saving Systems, Budgeting Strategies, and Wealth-Building Habits That Can Transform Your Financial Future

    Introduction

    Building wealth does not begin with earning a huge salary—it begins with learning how to manage and save the money you already have. Whether you are a student, employee, entrepreneur, supporting a family, living on a small income, or dealing with irregular earnings, developing consistent saving habits can create the foundation for greater financial security and long-term wealth. In this complete beginner’s guide, you will learn how to save money and build wealth through practical saving strategies, budgeting, emergency funds, the Pay Yourself First method, automated savings, and other proven money-management habits. You will also discover how to protect your savings and eventually turn accumulated savings into investment capital, helping you move step by step toward greater financial stability and financial freedom.

    Saving creates the financial foundation from which emergency security, investing, homeownership, entrepreneurship, retirement planning, and long-term wealth can grow.

    You may earn $1,000, $3,000, or $10,000 a month, but income alone does not determine financial security. What matters is how much of your income you keep, how effectively you manage it, and what you eventually do with the money you accumulate. This beginner-friendly guide explains practical saving techniques you can use whether you have a regular salary, irregular income, are a student, supporting a family, temporarily unemployed, or simply starting your financial journey

    Why Saving Is the Foundation of Wealth

    Saving creates a gap between what you earn and what you spend. That gap is where financial progress begins.

    Without savings, an unexpected car repair, medical expense, job interruption, or family emergency can force you to borrow. With savings, the same event may become an inconvenience rather than a financial crisis.

    The U.S. Consumer Financial Protection Bureau explains that even a small dedicated emergency fund can help people recover more quickly from unexpected expenses. CFPB Emergency Fund Guide

    Saving also creates capital. The first $500 you save may become an emergency cushion. Later, $5,000 or $10,000 could help finance education, a business, a home purchase, or long-term investments.

    Common Myths About Saving Money

    One of the biggest myths is: “I will start saving when I earn more.”

    Higher income certainly makes saving easier, but earning more does not automatically create wealth. If spending rises every time income increases, there may still be nothing left.

    Another myth is that small amounts are meaningless. They are not. Saving $5 a day equals $1,825 in one year before interest. The SEC’s Investor.gov explains how small amounts can become considerably larger over time when saving and investing are combined with compound growth. See How Small Savings Can Add Up

    The habit matters before the amount becomes large.

    Why Income Alone Doesn’t Create Wealth

    Imagine two workers.

    Person A earns $8,000 monthly but spends $8,200. Person B earns $4,000 but consistently saves $600.

    Who is moving toward greater financial stability?

    Income provides opportunity. Financial discipline determines what happens to that opportunity.

    Increasing your earnings is important, but building wealth usually requires controlling expenses, saving consistently, managing debt carefully, and eventually putting appropriate long-term money to productive use.

    Set SMART Savings Goals

    “Save more money” is a wish. A specific savings target is a plan.

    Use the SMART framework: make your goal Specific, Measurable, Achievable, Relevant, and Time-bound.

    Instead of saying, “I want an emergency fund,” say:

    “I will save $1,200 during the next 12 months by automatically transferring $100 each month into a separate savings account.”

    You immediately know the destination, deadline, and required monthly contribution.

    Investor.gov also provides a free Savings Goal Calculator that can help estimate how much you need to save regularly to reach a financial target.

    Create Your First Emergency Fund

    Before chasing high investment returns, establish financial protection.

    Start with an achievable milestone such as $500 or $1,000. Then work toward one month of essential expenses and gradually increase your reserve according to your circumstances.

    Some financial professionals commonly suggest eventually holding roughly three to six months of essential expenses, although the appropriate amount depends on employment stability, household responsibilities, health expenses, insurance, and other risks.

    Keep emergency savings somewhere safe and reasonably accessible rather than exposing money needed soon to unnecessary market risk.

    Use the Pay Yourself First Principle

    Most people follow this formula:

    Income → Expenses → Save whatever remains.

    Try reversing it:

    Income → Savings → Necessary expenses → Discretionary spending.

    This is the Pay Yourself First principle.

    When your paycheck arrives, transfer a predetermined amount into savings before optional spending begins. Even 5% is a meaningful starting point if that is what your budget allows.

    Saving becomes a financial obligation to your future self rather than an afterthought.

    Daily, Weekly and Monthly Saving Systems

    Different saving schedules work for different personalities.

    For a daily system, save a small fixed amount, transfer spare change, or redirect the cost of one unnecessary purchase. A $3 daily habit becomes more than $1,000 over a year.

    For a weekly system, choose one day—perhaps every Friday—to review spending and transfer a predetermined amount.

    For a monthly system, treat savings like rent or another recurring bill. Schedule it immediately after payday.

    Consistency is more important than choosing the “perfect” schedule.

    Try the 52-Week Saving Challenge

    The 52-week challenge turns saving into a gradual habit.

    Traditionally, you save $1 in week one, $2 in week two, $3 in week three, continuing until $52 in week 52. Completing the challenge produces $1,378.

    You can also reverse the challenge, starting with $52 and decreasing each week, or use a fixed weekly amount that better matches your income.

    The objective is not the specific formula. It is developing consistency.

    Automate Your Savings

    Automation removes repeated decision-making.

    Schedule an automatic transfer from checking to savings shortly after each payday. If your employer permits split direct deposit, you may be able to send part of every paycheck directly into savings.

    The CFPB specifically identifies automatic deposits and recurring transfers as practical ways to build savings consistently. CFPB Guide to Saving Automatically When saving happens automatically, you are less dependent on motivation

    Choose a Budgeting Method You Can Maintain

    A budget tells your money where it should go.

    One popular starting framework is the 50/30/20 approach: roughly 50% toward needs, 30% toward wants, and 20% toward savings and/or financial priorities. Those percentages are guidelines, not rules. Someone with high housing costs or a low income may need a different allocation.

    Another approach is zero-based budgeting, where every dollar of expected income receives a purpose before the month begins.

    The best budget is not necessarily the most complicated one. It is the system you can realistically follow month after month.

    Consider a High-Yield Savings Account

    Leaving substantial savings in an account paying very little interest can reduce its growth potential.

    A competitive high-yield savings account may provide a better return while retaining relatively easy access. Rates change, so compare APY, minimum balances, withdrawal options, fees, and deposit protection rather than choosing an account based only on an advertisement.

    In the United States, eligible deposits at an FDIC-insured bank are automatically insured to at least $250,000 per depositor, per insured bank, subject to ownership-category rules. Learn About FDIC Deposit Insurance

    Readers outside the United States should check their country’s equivalent deposit-protection system.

    Cut Unnecessary Expenses Without Making Life Miserable

    Saving does not require eliminating everything you enjoy.

    Start by identifying expenses providing little value: forgotten subscriptions, frequent delivery fees, impulse purchases, excessive banking fees, unused memberships, or expensive habits that have cheaper alternatives.

    Try a 24-hour rule before nonessential purchases. For larger purchases, consider waiting several days.

    Redirect at least part of the money you avoid spending directly into savings. Otherwise, “saving money” on one purchase can easily become spending it somewhere else.

    How to Save With Irregular Income or While Unemployed

    Freelancers, seasonal workers, gig workers, and entrepreneurs can save using percentages rather than fixed amounts.

    For example, decide that 5% or 10% of every payment received goes into savings. During high-income months, save more to create a buffer for slower periods.

    If unemployed, the immediate goal may change from aggressive saving to protecting existing cash. Prioritize housing, food, utilities, transportation, insurance, and other essentials. Reduce nonessential expenses and investigate legitimate benefits or assistance for which you qualify.

    Saving $5 during a difficult month still maintains the habit—but essential needs come first.

    Saving as a Student

    Students have one enormous financial advantage: time.

    Begin with manageable amounts. Save part of income from a part-time job, scholarship refund that is genuinely available for personal use, gifts, or other discretionary income.

    Learning budgeting, avoiding unnecessary debt, comparing prices, cooking more often, using student discounts, and saving even $10 or $20 regularly can establish habits that continue long after graduation.

    Family Saving Strategies

    Household saving works better when financial goals become shared goals.

    Families can create separate savings categories for emergencies, education, vacations, home repairs, vehicles, and major purchases. Parents can also involve children in age-appropriate discussions about needs, wants, saving, and delayed gratification.

    A family target—such as saving $3,000 for emergencies—can be divided into smaller monthly milestones so everyone can see progress.

    Use Mobile Banking and Savings Apps Carefully

    Modern banking makes saving easier. Mobile banking apps can provide automatic transfers, balance alerts, savings goals, spending notifications, and recurring deposits.

    Budgeting tools such as YNAB can help users plan where their money goes, while Acorns combines automated saving and investing features.

    No app is universally “best.” Compare subscription costs, security, account protection, features, withdrawal restrictions, and whether the service involves saving or investing. Investment accounts can lose value and should not be confused with insured bank savings.

    Common Saving Mistakes to Avoid

    The biggest mistakes include waiting for the “perfect” income, setting unrealistic targets, keeping no emergency reserve, repeatedly withdrawing savings for non-emergencies, ignoring high-interest debt, failing to track expenses, and increasing lifestyle spending every time income rises.

    Another mistake is treating every saved dollar as investment money. Emergency savings and long-term investments have different purposes

    Protect Your Savings

    Building money is only half the job. You must protect it.

    Use strong unique passwords, multi-factor authentication where available, account alerts, and reputable financial institutions. Be suspicious of unsolicited messages promising guaranteed profits or unusually high returns.

    Investor.gov warns that promises of high investment returns with little or no risk, pressure to act immediately, fake testimonials, and suspicious payment methods are common investment-fraud warning signs. Investor.gov Fraud and Investor Education Resources

    Turn Savings Into Investment Capital

    Saving provides security. Investing can provide long-term growth.

    Once you have appropriate emergency reserves and control over expensive debt, some money intended for long-term goals may potentially move toward diversified investments appropriate to your objectives, time horizon, and risk tolerance.

    Do not invest emergency money you may need next month.

    Investor.gov describes regular investing plus time as a powerful approach to building wealth and recommends establishing emergency savings alongside long-term investing. SEC Guide to Building Wealth Through Saving and Investing

    Case Studies: How Small Savings Can Build Financial Momentum

    Case Study 1 — The beginner: Maria can save only $25 each week. Instead of waiting until she earns more, she automates the transfer. After 52 weeks, she has contributed $1,300 before any interest. Her first financial victory is not becoming rich—it is proving she can consistently keep money.

    Case Study 2 — The irregular-income worker: Daniel’s monthly income changes. Rather than promising himself a fixed $300 contribution he cannot always afford, he saves 10% whenever he gets paid. Strong months automatically produce larger contributions, while difficult months remain manageable.

    Case Study 3 — The lifestyle reset: Aisha reviews several months of transactions and discovers approximately $180 per month going toward subscriptions, delivery fees, and impulse purchases she barely remembers. She cuts $100 and automatically transfers it monthly. In one year, she contributes $1,200 toward her emergency fund without increasing her salary.

    These examples are illustrative, but the principle is universal: wealth-building starts when part of today’s income is deliberately reserved for tomorrow.

    Final Thoughts: Start Small, Start Today

    You do not need to become wealthy before you begin saving. Saving is one of the habits that can help you build wealth.

    Start with an amount you can sustain. Create an emergency fund. Pay yourself first. Automate your contributions. Control unnecessary spending. Increase the amount when your income rises. Protect the money you accumulate. Then learn how to responsibly put long-term capital to work.

    Your first $10 may not appear life-changing. Neither may your first $100.

    But the habit behind those dollars can change the direction of your financial life.

    Start today. Save consistently. Protect what you build. Then give your money time to grow.

    Educational disclaimer: This article provides general financial education and does not constitute individualized financial, investment, tax, or legal advice. Financial products, regulations, interest rates, risks, and deposit-protection rules vary by country and can change over time.