Tag: #BuildWealth

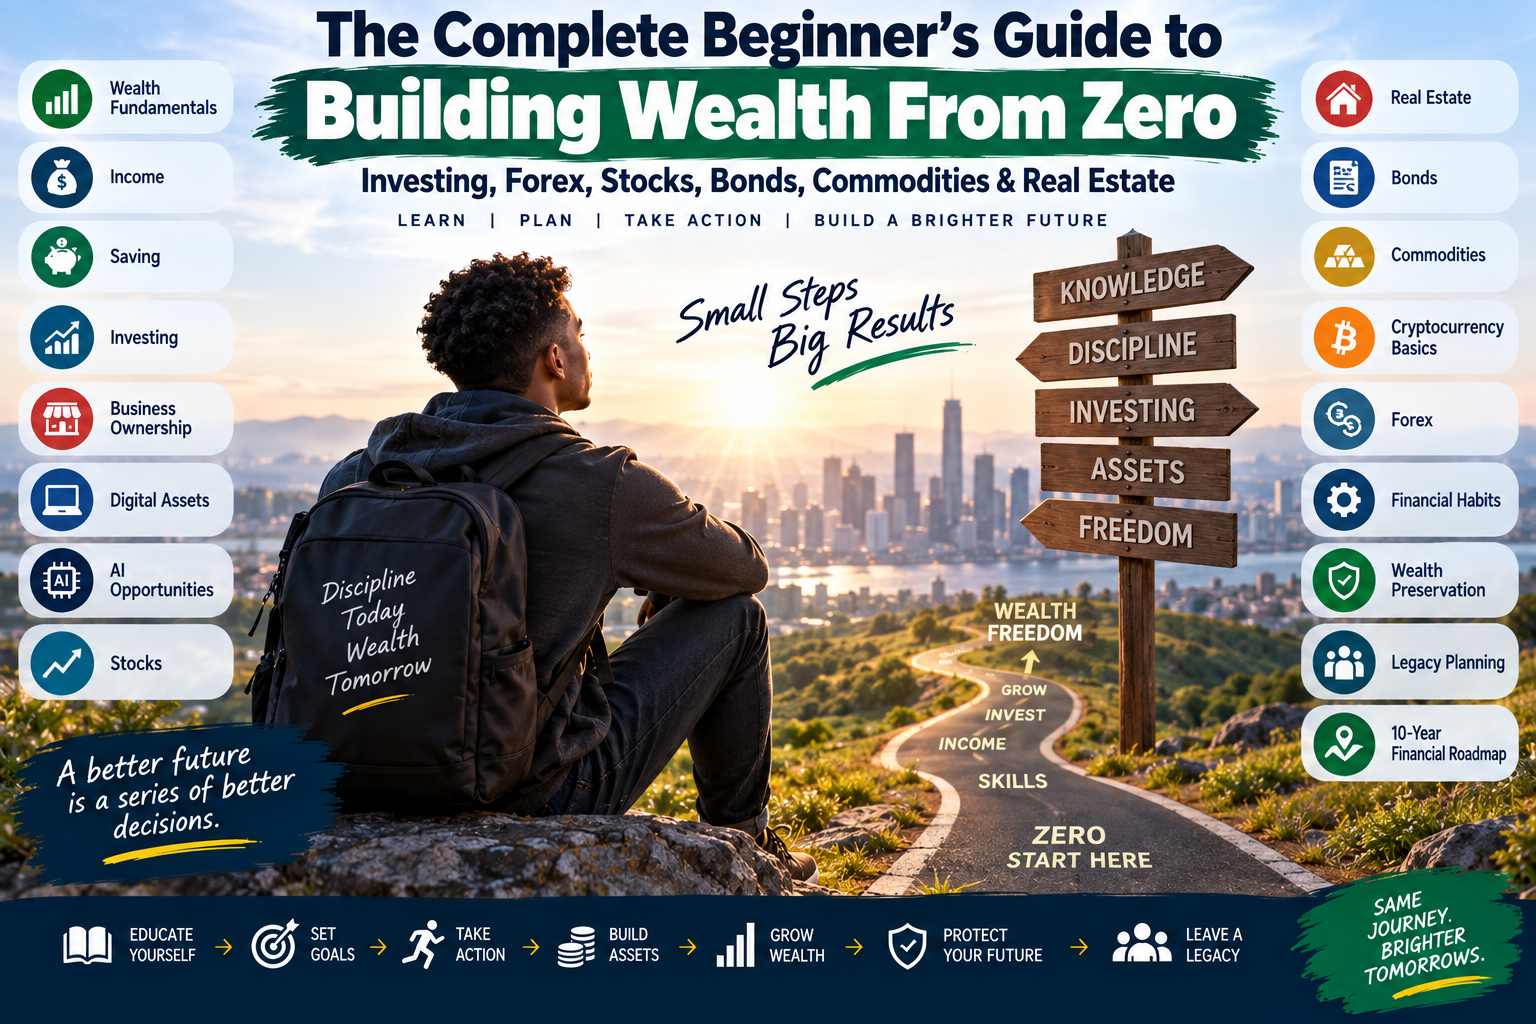
  • The Complete Beginner’s Guide to Building Wealth From Zero

    The Complete Beginner’s Guide to Building Wealth From Zero

    Building Wealth from Zero is possible. it depends on how you look at it

    Introduction

    Building wealth from zero can feel impossible when you have a small income, little savings, debt, or no investments.

    But wealth usually does not begin with a million-dollar investment.

    It begins with something much smaller:

    Knowledge.

    Then comes income.

    Then saving.

    Then investing.

    Then productive assets.

    Then time.

    The basic wealth-building process can be summarized as:

    Learn → Earn → Save → Invest → Build Assets → Increase Income → Diversify → Protect → Reinvest → Repeat

    Investor.gov explains that investing can help build wealth over time, while emphasizing that investment decisions should reflect your goals, time horizon and risk tolerance.

    Investor.gov Introduction to Investing

    This guide explains how someone starting with very little can begin building a stronger financial foundation through income, saving, investing, business ownership, stocks, bonds, real estate, digital assets and other opportunities—without pretending that any investment guarantees wealth.

    1. Understand What Wealth Really Means

    Wealth is not the same as income.

    Someone can earn $150,000 annually and spend $160,000.

    Another person might earn $70,000, control expenses, invest consistently and gradually accumulate productive assets.

    Income tells you how much money comes in.

    Wealth is more closely connected to what you own minus what you owe.

    A simple calculation is:

    Net Worth = Assets − Liabilities

    Assets may include:

    Cash + Savings + Investments + Retirement Accounts + Business Equity + Property

    Liabilities can include:

    Credit Cards + Personal Loans + Student Loans + Auto Loans + Mortgages + Other Debts

    Your starting net worth might be $500.

    It might be $0.

    It might even be negative.

    The important question is:

    Can you improve it year after year?

    2. Build Your Wealth Foundation Before Chasing Investments

    People sometimes begin their wealth journey by asking:

    “Which stock should I buy?”

    or:

    “Which cryptocurrency will make me rich?”

    Those are usually the wrong first questions.

    A stronger foundation begins with:

    Reliable income
    Controlled spending
    Emergency savings
    Manageable debt
    Financial education
    Clear goals

    Only then does investing become part of a broader wealth-building strategy.

    Think of your financial life as a house.

    Your income is the ground.

    Your budget is the foundation.

    Emergency savings provide stability.

    Investments and businesses build the upper floors.

    Trying to build the roof first creates unnecessary risk.

    3. Income: Your First Wealth-Building Engine

    When you are starting from zero, your most valuable financial asset may be your ability to earn.

    If you have $200 available to invest, finding a miraculous investment isn’t the most realistic path to major wealth.

    Increasing your income by $10,000 annually could have a much larger impact.

    Ways to increase income include:

    Career advancement
    Additional qualifications
    Higher-value skills
    Freelancing
    Overtime
    Consulting
    Small businesses
    Digital services
    Entrepreneurship

    Ask yourself:

    What skill could I develop over the next 12 months that employers or customers would pay me more to perform?

    Improving earning capacity gives you additional capital to save and invest.

    4. Control Spending Without Making Yourself Miserable

    Building wealth does not require eliminating everything enjoyable from life.

    It requires making sure consumption does not absorb everything you earn.

    Suppose your income rises by $500 per month.

    If spending immediately increases by $500, your wealth-building capacity has not improved.

    Instead, consider directing part of every raise toward:

    Savings
    Investments
    Debt reduction
    Business capital

    Lifestyle improvement is fine.

    Just make sure your net worth improves along with your lifestyle.

    5. Saving: Create Your First Financial Safety Net

    Before taking substantial investment risk, build emergency savings.

    Unexpected expenses happen:

    Car repairs
    Medical bills
    Job loss
    Family emergencies
    Home repairs
    Urgent travel

    Without savings, these events can become debt.

    Start with an achievable milestone.

    For example:

    $500 → $1,000 → One month of essential expenses → Three months → Several months

    The appropriate emergency reserve depends on your income stability, household responsibilities and other circumstances.

    The Consumer Financial Protection Bureau provides guidance on establishing emergency savings.

    6. Automate Your Wealth-Building Habits

    Willpower is unreliable.

    Systems are stronger.

    Consider automatically transferring money when income arrives.

    For example:

    Paycheck → Bills → Emergency Savings → Investments → Other Goals → Spending

    Automation makes wealth building part of your financial routine.

    Even $25 or $50 per paycheck establishes the habit.

    As your income increases, increase the amount.

    7. Investing: Understand the Purpose Before You Begin

    Saving and investing serve different purposes.

    Savings are generally appropriate for emergencies and shorter-term needs where accessibility and capital preservation are priorities.

    Investing involves accepting risk in pursuit of potential returns.

    Investor.gov explains that investment returns can come from increases in asset value, interest or dividends, but also emphasizes that all investments involve risk.

    Investor.gov Investment Products Guide

    Your investment strategy should consider:

    Financial goals
    Time horizon
    Risk tolerance
    Diversification
    Fees
    Taxes
    Liquidity

    Never invest in something simply because it is popular.

    8. Compound Growth: Give Your Money Time

    Compound growth occurs when investment returns potentially generate additional returns over time.

    Imagine investing $200 every month.

    In one year, you contribute:

    $2,400

    In ten years:

    $24,000

    In thirty years:

    $72,000

    If those investments also generate positive returns over the period, the portfolio could potentially become substantially larger than your direct contributions.

    This is why starting small can still matter.

    Use the official Investor.gov Compound Interest Calculator to test different contribution, return and time assumptions.

    Time can become one of your most powerful wealth-building resources.

    9. Stocks: Own Part of a Business

    A stock represents an ownership interest in a company.

    If the business becomes more valuable, the stock price may increase.

    Some companies also distribute part of their profits to shareholders through dividends.

    But stocks can decline significantly.

    A successful company today can struggle tomorrow.

    Investor.gov provides a detailed beginner’s explanation of stocks and how investors can buy them.

    The biggest beginner mistake is assuming:

    Popular company = Guaranteed investment return

    It doesn’t.

    Business performance, valuation, economic conditions, competition and investor expectations all influence stock prices.

    10. Individual Stocks vs. Diversified Funds

    Buying one company means your result depends heavily on that company.

    Diversified funds can spread exposure across many securities.

    Mutual funds and exchange-traded funds can make diversification easier, although narrowly focused funds may still be concentrated. Investor.gov emphasizes diversification both between asset classes and within them.

    Investor.gov Guide to Asset Allocation and Diversification

    Diversification does not guarantee against losses.

    It is a method of managing concentration risk

    11. Bonds: Understand Lending as an Investment

    When you buy certain bonds, you are essentially lending money to an issuer such as a government, municipality or company.

    In return, the issuer generally promises interest and repayment according to specified terms.

    Bonds are often considered less volatile than stocks, but they are not risk-free.

    Risks can include:

    Interest-rate risk
    Inflation risk
    Credit/default risk
    Liquidity risk

    Investor.gov notes that bonds generally have lower volatility and more modest return potential than stocks, although higher-yield bonds can carry substantially greater risk.

    Investor.gov Investment Options

    12. Real Estate: Build Wealth Through Property Carefully

    Real estate has created wealth for many people, but property is not automatically a profitable investment.

    Potential ways to participate include:

    Primary residences
    Rental properties
    Commercial property
    Real estate investment trusts
    Real-estate-related funds

    For rental property, calculate:

    Rent − Mortgage − Taxes − Insurance − Maintenance − Vacancies − Management − Other Expenses = Approximate Cash Flow

    Do not assume:

    $2,000 monthly rent = $2,000 monthly profit.

    Real estate can provide rental income and potential appreciation, but it can also create concentrated risk, debt, repair costs and illiquidity.

    13. Business Ownership: Build an Asset You Control

    Employment produces income.

    Business ownership can potentially produce both income and equity.

    A successful company may eventually become an asset that has value beyond the owner’s monthly salary.

    You don’t necessarily need millions of dollars to start.

    Small businesses can include:

    Cleaning
    Tutoring
    Graphic design
    Marketing
    Baking
    Photography
    Consulting
    Landscaping
    Web development
    Transportation
    E-commerce
    Digital services

    The U.S. Small Business Administration provides extensive information about planning and launching businesses.

    Business structure also matters because liability, taxation and ownership rules differ. The SBA notes, for example, that a sole proprietorship generally does not create a separate legal business entity, while other structures can have different liability characteristics.

    Readers outside the United States should consult their local business-registration and tax authorities.

    14. Digital Assets: Turn Knowledge and Creativity Into Products

    Not every productive asset is physical.

    You can create digital assets such as:

    Websites
    eBooks
    Online courses
    Templates
    Software
    Apps
    Educational resources
    Membership platforms
    Original media libraries

    A useful digital asset may continue producing revenue after the original work is completed, although maintenance, marketing and customer support are usually still necessary.

    Think of digital wealth creation as:

    Knowledge → Product → Audience → Distribution → Revenue → Reinvestment

    The strongest digital products solve specific problems.

    15. AI Opportunities: Use Technology to Increase Productivity

    Artificial intelligence is creating opportunities for entrepreneurs and workers to perform certain tasks faster.

    Potential applications include:

    Business automation
    Research assistance
    Customer support
    Data organization
    Marketing workflows
    Educational products
    Software development
    Content assistance
    Design workflows

    But don’t build a business around the phrase “AI.”

    Build it around a customer problem.

    Ask:

    What valuable problem can I solve better, faster or more affordably using AI?

    Also protect confidential business and personal information when using AI services.

    AI should increase human productivity—not replace judgment where accuracy, privacy or professional expertise is required.

    16. Forex: Understand the Risk Before Trading

    Forex means foreign exchange—the trading of currencies.

    Currencies constantly fluctuate relative to one another because of factors such as:

    Interest rates
    Inflation
    Economic growth
    Central-bank policies
    Trade
    Political developments
    Market expectations

    Forex is frequently promoted online as an easy wealth-building opportunity.

    That framing can be dangerous.

    The U.S. Commodity Futures Trading Commission warns that most customers at registered over-the-counter forex dealers lose money after costs, and leverage can amplify losses; in some circumstances, losses can exceed the initial deposit.

    CFTC: Eight Things You Should Know Before Trading Forex

    For a beginner building wealth from zero, forex trading should not be confused with a basic savings or diversified long-term investment plan.

    Never trade essential household money, emergency savings or borrowed money.

    17. Commodities: Gold, Oil, Agriculture and More

    Commodities include physical resources such as:

    Gold
    Silver
    Oil
    Natural gas
    Corn
    Wheat
    Coffee
    Other agricultural and industrial products

    Investors may gain exposure through different financial products.

    Commodity futures are particularly specialized and can involve substantial risk.

    Investor.gov explains that commodity futures involve agreements to buy or sell specified quantities at predetermined terms and notes that futures and forex are areas where regulators warn about fraudulent high-yield offers.

    Investor.gov Commodities Guide

    Beginners should understand exactly what product they are buying before gaining commodity exposure.

    18. Gold and Precious Metals

    Gold is sometimes used as a portfolio diversifier or store-of-value asset.

    But gold does not automatically increase in value.

    It can experience long periods of disappointing performance.

    Precious metals also do not produce business earnings in the way a profitable company can.

    If you include commodities in your portfolio, understand why they are there.

    Do not buy simply because someone predicts economic collapse.

    19. Cryptocurrency Basics

    Cryptocurrency and other crypto assets use blockchain or related distributed-ledger technologies.

    They can include:

    Coins
    Tokens
    Stablecoins
    Other blockchain-based assets

    Crypto markets can experience extreme price movements.

    The CFTC warns that virtual currencies can be highly volatile and that leverage can amplify both gains and losses.

    Custody introduces additional considerations. Investor.gov explains that crypto wallets generally hold the private keys used to access crypto assets, making secure custody an important part of understanding ownership.

    Investor.gov Crypto Asset Custody Basics

    Never assume crypto accounts provide the same protections as insured bank deposits. Some crypto products carry materially different protections and risks.

    For beginners, crypto should be approached as a high-risk area requiring substantial education, not as guaranteed wealth.

    20. Never Build Your Wealth Plan Around Speculation

    There is an important distinction between:

    Building wealth

    and

    trying to get rich quickly.

    Wealth building generally emphasizes:

    Income
    Saving
    Productive assets
    Diversification
    Compounding
    Patience

    Speculation focuses heavily on predicting future price movements.

    Speculative assets may rise dramatically.

    They can also collapse.

    The more your strategy depends on predicting tomorrow’s price, the more risk you may be taking.

    21. Diversification: Don’t Let One Investment Determine Your Future

    A diversified portfolio spreads exposure across multiple investments or asset categories.

    Depending on the investor, these might include:

    Cash
    Stocks
    Bonds
    Real estate
    Business interests
    Other appropriate assets

    Investor.gov explains that diversification cannot guarantee against losses, but it can reduce dependence on any single investment.

    Investor.gov Diversification Guide

    Your appropriate allocation depends on your goals, time horizon, financial position and tolerance for loss.

    22. Understand Risk Before Thinking About Return

    Beginners frequently ask:

    “How much can I make?”

    A better first question is:

    “How much could I lose?”

    Investor.gov emphasizes that higher potential returns generally come with higher risk and that investors should consider risk, fees, goals and time horizon when evaluating investments.

    Before buying any investment, understand:

    How it generates returns
    What could make it lose value
    How easily you can sell it
    What fees you pay
    What taxes may apply
    Whether leverage is involved
    Whether the provider is regulated

    If you cannot explain how an investment works, continue learning before committing money.

    23. Avoid High-Cost Consumer Debt

    Compound growth can work for you through investments.

    Interest can also work against you through debt.

    High-interest credit-card or consumer debt can absorb money that could otherwise build assets.

    A sensible wealth-building sequence often involves controlling expensive debt while establishing emergency savings and gradually preparing to invest.

    Do not borrow at extremely high rates hoping to earn even higher investment returns.

    That can transform investing into dangerous speculation.

    24. Financial Habits Matter More Than Financial Motivation

    Motivation comes and goes.

    Habits remain.

    Useful wealth-building habits include:

    Tracking spending
    Saving automatically
    Investing regularly
    Reviewing debt
    Reading financial information
    Increasing contributions with income
    Avoiding emotional purchases
    Reviewing net worth annually

    A $100 monthly habit maintained for years can be more valuable than an ambitious financial plan abandoned after three months.

    25. Build Multiple Income Streams Gradually

    Your wealth journey may begin with one salary.

    Eventually it might evolve into:

    Salary + Freelancing + Business + Investment Income + Digital Assets

    You don’t need seven side hustles.

    Build one additional income stream.

    Make it profitable.

    Improve the system.

    Then consider another.

    Income diversification can reduce dependence on a single paycheck and provide additional capital for acquiring assets.

    26. Reinvest Instead of Consuming Every Profit

    Suppose your side business generates an additional $500 monthly.

    You could immediately spend the entire $500.

    Or you could divide it:

    Emergency Savings
    Business Reinvestment
    Long-Term Investments
    Debt Reduction
    Personal Enjoyment

    Reinvestment is how additional income can gradually become productive capital.

    The goal is:

    Income → Assets → More Potential Income → More Assets

    27. Protect the Wealth You Build

    Building wealth is only half the journey.

    You must also protect it.

    Wealth preservation may involve:

    Emergency reserves
    Diversification
    Appropriate insurance
    Cybersecurity
    Fraud prevention
    Responsible debt
    Tax planning
    Legal structures where appropriate
    Estate planning

    As your wealth grows, one preventable financial disaster becomes increasingly expensive.

    28. Protect Yourself From Investment Scams

    Wealth-building beginners are prime targets for scammers.

    Warning signs include:

    Guaranteed profits
    No-risk returns
    Secret investment opportunities
    Pressure to act immediately
    Unregistered forex brokers
    Fake crypto platforms
    Celebrity impersonations
    Requests to transfer money privately

    For forex, the CFTC specifically recommends researching dealers and checking regulatory registration before depositing money.

    For securities investing, use Investor.gov and appropriate national securities regulators.

    Never let fear of missing out replace due diligence.

    29. Legacy Planning: Decide What Your Wealth Is For

    Wealth is not only about what happens during your lifetime.

    As assets grow, think about:

    Who depends on you?
    What happens if you die unexpectedly?
    Who should receive your assets?
    Who can manage important affairs if you cannot?

    Depending on local law and your circumstances, legacy planning might involve:

    Wills
    Beneficiary designations
    Insurance
    Powers of attorney
    Trusts
    Business succession planning
    Charitable giving

    Estate and inheritance laws differ substantially by country, so obtain qualified local legal and tax guidance when needed.

    The objective is to make sure the wealth you spent decades building is transferred according to your intentions

    30. Your 10-Year Financial Roadmap From Zero

    Building wealth becomes easier when you stop thinking only about next month.

    Think in years.

    Year 1 — Financial Stabilization

    Focus on:

    Budgeting
    Tracking expenses
    Initial emergency savings
    High-cost debt
    Financial education
    Increasing employable skills

    Goal:

    Stop financial instability from controlling your decisions.

    Year 2 — Increase Your Financial Capacity

    Work on:

    Increasing income
    Improving skills
    Building emergency reserves
    Reducing expensive debt
    Beginning basic investing education

    Goal:

    Create consistent monthly financial surplus.

    Year 3 — Become an Investor

    Once financially prepared, establish an appropriate long-term investment strategy.

    Learn about:

    Stocks
    Bonds
    Diversified funds
    Retirement accounts
    Risk
    Fees
    Taxes

    Goal:

    Begin acquiring productive financial assets consistently.

    Year 4 — Build Your Second Income Stream

    Choose one realistic opportunity:

    Freelancing
    Consulting
    Digital products
    Service business
    Online business
    Part-time enterprise

    Goal:

    Reduce dependence on one paycheck.

    Year 5 — Increase Your Asset Ownership

    Increase contributions as income improves.

    Your financial picture might now include:

    Emergency savings + Investments + Retirement assets + Business assets

    Goal:

    Make asset ownership a normal part of your financial life.

    Year 6 — Explore Additional Asset Classes

    Once you understand basic investing, learn about other opportunities such as:

    Real estate
    Bonds
    Business equity
    Digital assets
    Appropriate alternative investments

    This does not mean buying everything.

    Goal:

    Understand opportunities before deciding whether they belong in your plan.

    Year 7 — Scale What Works

    By now, you should have evidence about which income and investment strategies work for you.

    Scale successful areas.

    Stop wasting resources on unsuccessful ones.

    Goal:

    Concentrate effort without creating dangerous financial concentration.

    Year 8 — Strengthen Wealth Protection

    Review:

    Insurance
    Emergency reserves
    Investment diversification
    Cybersecurity
    Taxes
    Legal structures
    Estate planning

    Goal:

    Protect accumulated assets from avoidable risks.

    Year 9 — Build Greater Financial Independence

    Calculate:

    Annual expenses
    Investment assets
    Business income
    Passive or portfolio income
    Net worth
    Debt

    Ask:

    How dependent am I on employment income today compared with nine years ago?

    Goal:

    Increase your financial options.

    Year 10 — Review, Rebalance and Design the Next Decade

    Measure your progress.

    Compare:

    Year 1 Income → Year 10 Income

    Year 1 Savings → Year 10 Savings

    Year 1 Investments → Year 10 Investments

    Year 1 Debt → Year 10 Debt

    Year 1 Net Worth → Year 10 Net Worth

    Then build the next ten-year plan.

    Your financial journey doesn’t end at Year 10.

    You have simply built a stronger starting point for the next decade.

    The Wealth-Building Pyramid

    Think about wealth in layers.

    Level 1 — Knowledge

    Learn money fundamentals.

    Level 2 — Income

    Develop valuable skills and increase earnings.

    Level 3 — Financial Stability

    Budget, save and manage expensive debt.

    Level 4 — Investing

    Acquire diversified productive assets.

    Level 5 — Ownership

    Build business, property and other appropriate assets.

    Level 6 — Diversification

    Avoid depending on one income source or investment.

    Level 7 — Wealth Preservation

    Protect assets through appropriate risk management.

    Level 8 — Legacy

    Transfer wealth intentionally.

    Trying to jump directly from Level 1 to speculative trading at Level 6 is not a shortcut.

    It may simply expose you to risks you are not financially prepared to absorb.

    A Beginner’s Wealth-Building Checklist

    Before considering yourself ready for increasingly complex investments, ask:

    Do I understand my monthly cash flow?

    Do I have emergency savings?

    Is expensive consumer debt under control?

    Am I consistently saving?

    Do I understand what I am investing in?

    Do I understand potential losses?

    Am I diversified appropriately?

    Am I paying reasonable fees?

    Am I investing for a defined goal?

    Am I protecting myself from fraud?

    Am I increasing my earning capacity?

    Am I building productive assets?

    Do I have a long-term financial plan?

    If several answers are no, those areas may deserve attention before chasing higher-risk opportunities.

    Conclusion

    Building wealth from zero does not begin with finding the perfect stock, predicting currency markets, buying cryptocurrency or discovering the next investment sensation.

    It begins with fundamentals.

    Learn how money works.
    Increase your income.
    Control unnecessary spending.
    Build emergency savings.
    Manage destructive debt.
    Invest consistently.
    Diversify.
    Build businesses and productive assets.
    Protect what you accumulate.
    Plan for the next generation.

    Stocks can contribute to wealth.

    Bonds can have a role.

    Real estate can create opportunities.

    Business ownership can become enormously valuable.

    Digital assets can generate income.

    AI can improve productivity.

    Commodities may serve particular portfolio purposes.

    Crypto assets may offer opportunities alongside substantial risks.

    Forex exists as a massive global market—but leveraged retail forex trading should never be mistaken for a guaranteed wealth-building system.

    There is no single asset that every person must own.

    Your appropriate strategy depends on your income, goals, responsibilities, time horizon and ability to withstand losses.

    The most important thing about starting from zero is understanding that zero does not have to be your permanent financial position.

    Your first $100 matters.

    Your first emergency fund matters.

    Your first investment matters.

    Your first profitable business matters.

    Your first $10,000 matters.

    And every responsible financial decision can move you further from dependence and closer to ownership.

    The journey may take ten, twenty or thirty years.

    That is not failure.

    That is how long-term wealth is often built:

    One skill.
    One paycheck.
    One saved dollar.
    One investment.
    One productive asset.
    One disciplined decision at a time.
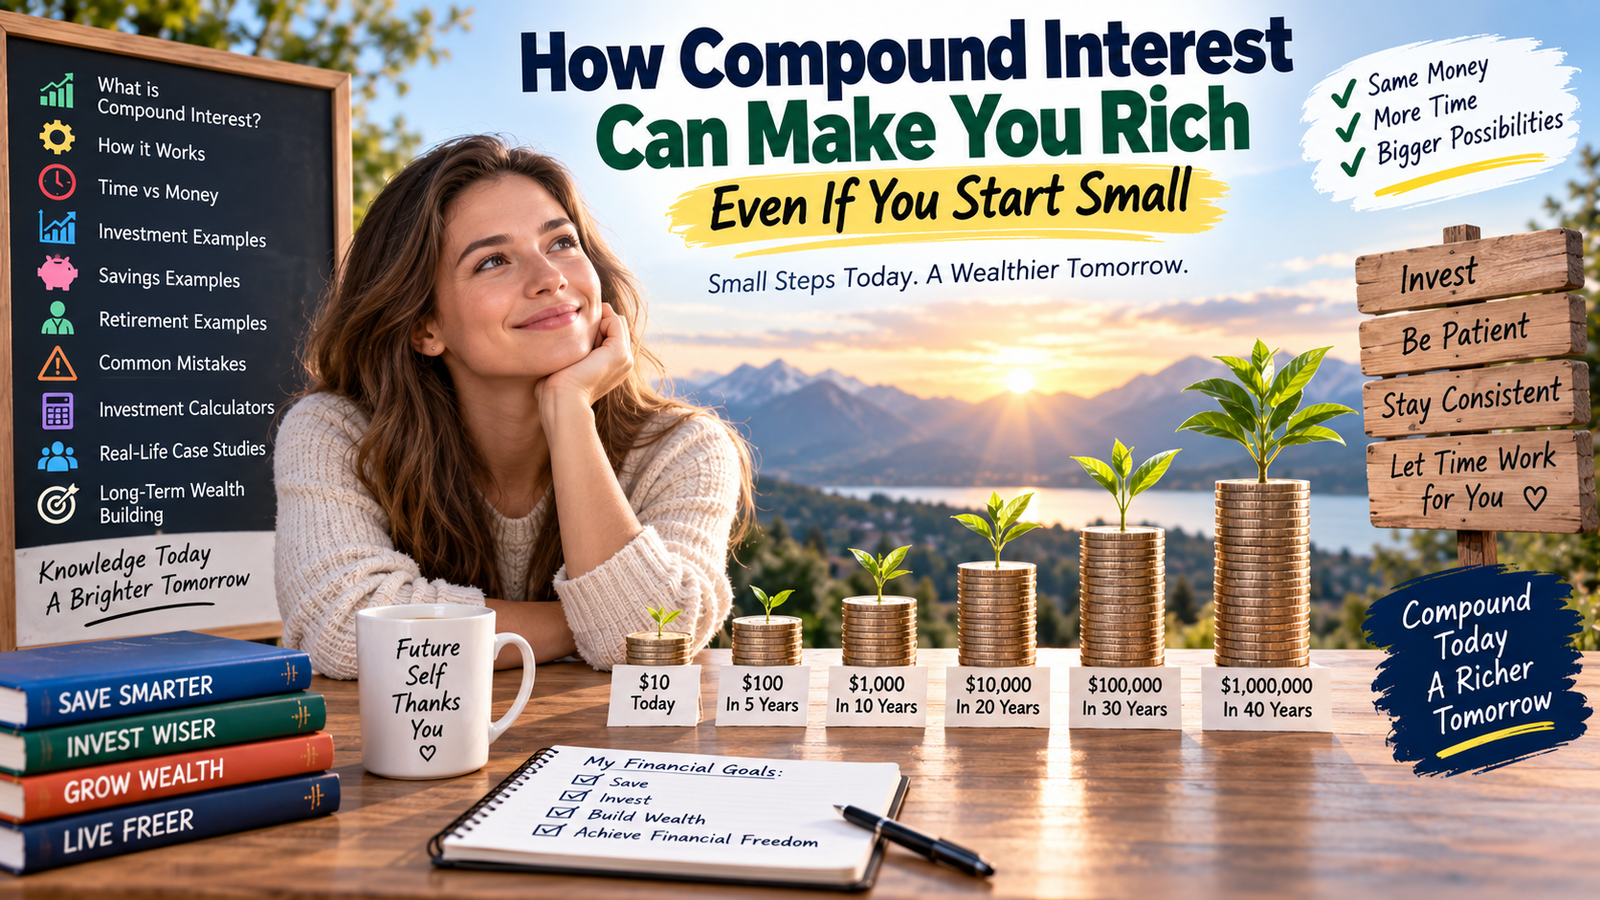
  • How Compound Interest Can Make You Rich Even If You Start Small

    How Compound Interest Can Make You Rich Even If You Start Small

    How Small Savings and Investments Can Grow Into Significant Long-Term Wealth Through Time and Consistency

    Introduction

    You Don’t Need to Start Rich to Build Wealth

    One of the biggest misconceptions about wealth building is that you need a large amount of money before investing becomes worthwhile.

    You don’t.

    Starting with $10, $50, $100 or $500 may seem insignificant when compared with the large investment portfolios discussed in financial media. But when money is invested consistently and allowed to grow over many years, something powerful can happen: compound growth.

    Compound interest means you can potentially earn returns not only on the money you originally saved or invested, but also on previous interest or investment returns.

    This creates a snowball effect.

    At first, progress can appear frustratingly slow. As time passes, however, the growth generated by your accumulated money can become increasingly important.

    The U.S. Securities and Exchange Commission’s Investor.gov provides a compound-interest calculator that demonstrates how savings can potentially grow over time, while the Consumer Financial Protection Bureau provides educational resources for establishing stronger saving habits.

    The lesson is simple:

    You don’t necessarily need a large starting amount. You need consistency, reasonable returns, and—most importantly—time.

    What Is Compound Interest?

    Compound interest is interest calculated on your original principal plus previously accumulated interest.

    Imagine depositing $1,000 into an account earning a hypothetical 5% annually.

    After the first year:

    $1,000 × 5% = $50

    Your balance becomes:

    $1,050

    If the money remains in the account, the second year’s interest is calculated on $1,050 rather than only the original $1,000.

    At 5%, that would produce:

    $52.50

    Your balance becomes:

    $1,102.50

    The extra $2.50 may appear insignificant.

    But over many compounding periods, the difference can become much larger.

    Investor.gov explains the concept through its educational material on compound interest, and its compound interest calculator allows investors to test different hypothetical scenarios.

    The fundamental principle is:

    Your money can potentially begin earning money on money it previously earned.

    How Does Compound Interest Work?

    A simplified annual compounding formula is:

    Future Value = Principal × (1 + Rate)^Time

    Suppose you invest $5,000 and hypothetically earn 7% annually for 20 years without adding additional money.

    The calculation would be approximately:

    $5,000 × (1.07)^20 = $19,348

    Your original $5,000 would have potentially grown to approximately $19,348.

    That does not mean every investment will return 7%. Investment returns fluctuate and can be negative. The example simply demonstrates the mathematics of compounding.

    The Investor.gov compound-interest calculator lets readers experiment with principal, contributions, interest rates and time, while FINRA’s investing resources explain important concepts investors should understand before putting money at risk.

    Time vs. Money: Why Starting Early Can Matter More Than Starting Big

    One of the most important lessons about compound growth is that time can compensate for a relatively small beginning.

    Consider two hypothetical investors.

    Investor A: Starts at Age 20

    Investor A invests $200 every month from age 20 until age 60.

    Total contributions:

    $200 × 12 × 40 = $96,000

    At a hypothetical 7% annual return compounded monthly, the portfolio could grow to roughly $525,000.

    Investor B: Starts at Age 40

    Investor B also invests $200 monthly but starts at age 40 and continues until 60.

    Total contributions:

    $200 × 12 × 20 = $48,000

    At the same hypothetical return, the portfolio could grow to roughly $104,000.

    The difference isn’t simply because Investor A contributed more.

    Investor A’s earliest contributions had decades longer to potentially compound.

    This illustrates why the Investor.gov saving and investing resources encourage understanding long-term investing, while the FINRA investor education center provides resources for making informed investment decisions.

    Starting early can be more powerful than waiting until you have a large amount of money.

    Small Monthly Investments Can Become Significant

    Suppose someone begins investing $100 per month at age 25.

    Assume, purely for illustration, an average annual return of 7%.

    If that person continues for 40 years, their personal contributions total:

    $48,000

    Yet the hypothetical investment balance could eventually reach approximately $262,000.

    Increase the contribution to $300 monthly under the same hypothetical assumptions, and the eventual balance could approach approximately $787,000.

    Again, these are illustrations—not guaranteed investment outcomes.

    Actual results depend on market performance, investment fees, taxes, contribution timing and other factors.

    The lesson is not that 7% is guaranteed.

    The lesson is that:

    Small Amount + Consistency + Return + Time = Potentially Significant Growth

    Compound Growth in a Savings Account

    Compounding does not apply only to stock-market investments.

    Interest-bearing savings accounts can also compound.

    Suppose you deposit $10,000 into a savings account earning a hypothetical 4% annually and leave the interest in the account.

    After one year, approximately:

    $10,400

    After five years:

    $12,167

    After ten years:

    $14,802

    The exact result depends on the account’s rate and compounding frequency.

    Savings accounts generally offer lower expected returns than riskier investments, but they can be appropriate for emergency funds and shorter-term financial goals where protecting principal and maintaining liquidity are priorities.

    The CFPB savings resources provide information about developing savings strategies, while U.S. readers can learn about insured bank deposits from the Federal Deposit Insurance Corporation.

    Readers outside the United States should check the deposit-protection rules and regulated financial institutions in their own countries.

    Compound Growth and Retirement

    etirement planning is one of the clearest examples of why compounding matters.

    Imagine a 25-year-old contributes $250 monthly toward long-term retirement investments.

    At a hypothetical 7% annual return, continuing until age 65 could potentially produce approximately $656,000.

    Personal contributions would total only:

    $250 × 12 × 40 = $120,000

    Much of the hypothetical difference would come from investment growth and compounding.

    A person who waits until 45 has only 20 years before reaching 65. Achieving a similar result would require dramatically larger contributions or substantially different investment outcomes.

    The Investor.gov retirement toolkit provides educational resources for retirement investors, while FINRA’s retirement resources explain important considerations when preparing financially for retirement.

    The Rule of 72: A Simple Compounding Shortcut

    A popular mental shortcut called the Rule of 72 estimates how long an investment might take to double at a fixed rate.

    Divide 72 by the hypothetical annual return.

    For example:

    72 ÷ 6 = approximately 12 years

    At 6%, money would take roughly 12 years to double.

    At 8%:

    72 ÷ 8 = approximately 9 years

    This is only an approximation, but it illustrates the relationship between returns and time.

    Be careful, however: higher potential returns generally involve greater investment risk. Never select an investment simply because it advertises a high return.

    Investment Example: $50 Per Week

    Suppose you invest $50 every week.

    That is approximately:

    $2,600 per year

    Over 30 years, your direct contributions would total approximately:

    $78,000

    If those contributions achieved a hypothetical long-term return, compound growth could potentially make the final portfolio significantly larger than the amount personally contributed.

    This is why consistency matters.

    Many people wait for a future moment when they expect to have thousands of dollars available to invest.

    That moment may never arrive.

    Starting with manageable recurring contributions can be more effective than endlessly waiting for perfect financial circumstances.

    Savings Example: The Young Worker

    Consider Maya, age 22.

    She earns a modest salary and believes investing is only for wealthy people.

    She decides to begin with $25 per week.

    That equals approximately $100–$110 monthly.

    As her income rises, she gradually increases the amount.

    At 25, she contributes $150 monthly.

    At 30, she increases it to $250.

    At 35, she contributes $400.

    Her greatest advantage isn’t that she started wealthy.

    She didn’t.

    Her advantage is that she established the habit early and increased contributions as her financial capacity improved.

    Retirement Example: Starting at 25 vs. Starting at 35

    Consider two hypothetical people.

    Daniel Starts at 25

    He invests $300 monthly until age 65.

    At a hypothetical 7% annual return, his account could grow to approximately $787,000.

    Michael Starts at 35

    Michael invests the same $300 monthly until age 65.

    At the same hypothetical return, his account could grow to approximately $366,000.

    Daniel had only ten additional years.

    But those ten years gave his earliest contributions significantly more time to compound.

    This demonstrates one of the most important principles in long-term wealth building:

    The cost of waiting can be enormous.

    What If You Are Already 40, 50 or Older?

    Do not interpret the importance of starting early as meaning it is too late to start.

    Starting today still gives your money more time than starting five years from now.

    Someone beginning later can potentially compensate in several ways:

    • Increase contributions
    • Reduce unnecessary expenses
    • Extend the investment horizon
    • Increase income
    • Use appropriate retirement accounts
    • Avoid excessive investment fees
    • Develop additional income sources

    The best time to start may have been years ago.

    The next available opportunity is now.

    Compound Interest Can Also Work Against You

    Compounding has another side.

    Debt can compound too.

    If you carry expensive debt and repeatedly fail to pay it down, interest can accumulate on the outstanding balance.

    This is particularly dangerous with high-interest credit cards and certain short-term loans.

    Instead of your money generating more money for you, interest charges can transfer increasing amounts of your future income to lenders.

    The Consumer Financial Protection Bureau’s credit-card resources provide educational information about credit cards, while the CFPB debt collection and financial education resources can help consumers better understand debt-related issues.

    The goal is to put compounding on your side of the financial equation whenever possible.

    Common Compound-Interest Mistakes

    1. Waiting Until You Earn More

    People frequently say:

    “I’ll start investing when I earn more.”

    Then income rises—and expenses rise with it.

    Start with an affordable amount and increase it gradually.

    2. Expecting Unrealistically High Returns

    Be suspicious of anyone promising extremely high, guaranteed investment returns.

    The Investor.gov fraud resources explain common warning signs of investment fraud, while FINRA BrokerCheck allows U.S. investors to research investment professionals and firms.

    3. Constantly Withdrawing Investments

    Compounding needs time.

    Frequently withdrawing long-term investments interrupts the process and may create taxes, fees or missed growth opportunities.

    4. Ignoring Investment Fees

    Small percentage fees can have large long-term effects.

    The SEC’s Investor Bulletin on fees and expenses explains why investment costs deserve attention.

    5. Taking Too Much Risk

    Compounding cannot help if catastrophic losses destroy your capital.

    Diversification and appropriate risk management matter.

    Investor.gov provides an explanation of diversification, and FINRA offers broader investing guidance.

    Use Compound Interest Calculators Before Setting Goals

    You do not have to calculate decades of compound growth manually.

    Online calculators allow you to experiment with:

    Starting amount
    Monthly contribution
    Estimated return
    Investment period
    Compounding frequency

    The Investor.gov Compound Interest Calculator is a useful starting point.

    You can also explore Investor.gov’s broader collection of financial calculators.

    Try several scenarios.

    What happens if you invest $100 monthly instead of $50?

    What happens if you start five years earlier?

    What if you increase contributions by $50 every year?

    What happens if returns are lower than expected?

    Scenario planning can help transform an abstract financial goal into a practical monthly target.

    Real-Life Case Study 1: Starting Small

    Imagine Anna, age 21, can afford only $50 per month.

    She feels embarrassed because friends online discuss investing thousands.

    But Anna begins anyway.

    After receiving salary increases, she gradually moves from:

    $50 → $100 → $200 → $300 monthly

    Her first $50 contribution wasn’t important because it instantly made her rich.

    It was important because it established the behavior that could continue for decades.

    Her wealth-building engine started early.

    Real-Life Case Study 2: The High Earner Who Waited

    James earns considerably more than Anna.

    But he continually postpones investing.

    At 25, he says he’ll begin at 30.

    At 30, he buys a more expensive vehicle.

    At 35, he upgrades his lifestyle again.

    At 40, he finally begins investing aggressively.

    James may still build substantial wealth because his income allows larger contributions.

    But money invested at 40 does not have the same amount of time to compound before traditional retirement age as money invested at 20 or 25.

    High income is valuable.

    High income combined with time is considerably more powerful.

    Real-Life Case Study 3: The Consistent Family

    Consider a family that automatically saves and invests part of every paycheck.

    They don’t try to predict which investment will become the next global sensation.

    They establish emergency savings, manage expensive debt, contribute regularly to diversified long-term investments and increase contributions whenever household income rises.

    Some years markets perform strongly.

    Other years investments decline.

    They remain focused on their long-term financial plan rather than reacting emotionally to every headline.

    Their primary advantage is not prediction.

    It is discipline and consistency.

    How to Use Compound Growth for Long-Term Wealth Building

    Compound interest becomes most powerful when combined with several other financial habits.

    Start Early

    Give your money as much time as reasonably possible.

    Contribute Consistently

    Automate recurring savings or investments where appropriate.

    Increase Contributions

    Whenever income increases, consider increasing your contribution before lifestyle inflation absorbs the entire raise.

    Reinvest Returns

    Allowing interest, dividends or other investment returns to remain invested can support compounding.

    Diversify

    Avoid depending entirely on one company, industry or speculative asset.

    Keep Costs Reasonable

    Fees reduce the amount of money remaining in your portfolio to compound.

    Avoid Emotional Decisions

    Fear can cause investors to sell during downturns, while greed can encourage buying speculative investments after dramatic price increases.

    Protect Your Financial Foundation

    Maintain appropriate emergency savings so you are less likely to liquidate long-term investments whenever an unexpected expense occurs.

    The Long-Term Wealth Formula

    Sustainable wealth building can be summarized simply:

    Earn → Save → Invest → Reinvest → Compound → Increase Contributions → Repeat

    You don’t need to execute this perfectly.

    You need to continue doing it.

    The first years can feel slow because your contributions create most of the growth.

    Eventually, if investments perform positively over time, investment growth itself can become a much larger part of the portfolio.

    That is when the compounding snowball becomes easier to see.

    A Simple Action Plan to Start Today

    Step 1: Calculate how much you can realistically save every month.

    Step 2: Build an appropriate emergency reserve.

    Step 3: Address expensive consumer debt.

    Step 4: Learn the basics of diversified investing.

    Step 5: Choose regulated financial products appropriate to your country and circumstances.

    Step 6: Automate contributions where possible.

    Step 7: Reinvest investment income when appropriate for your goals.

    Step 8: Increase contributions as your income rises.

    Step 9: Review your progress annually rather than obsessing over daily market movements.

    Step 10: Give your strategy time.

    The process is not glamorous.

    But successful long-term wealth building often isn’t.

    Conclusion

    Start Small, but Give Your Money Time to Grow

    Compound interest teaches one of the most encouraging lessons in personal finance:

    Your starting amount does not have to determine your final destination.

    Someone beginning with $25 or $50 may not feel like an investor.

    But that small beginning establishes something extremely valuable—a habit.

    As income increases, $50 can become $100.

    $100 can become $250.

    $250 can become $500.

    Meanwhile, earlier contributions have more time to potentially generate returns, and those returns can potentially generate additional returns.

    That is the power of compounding.

    Do not mistake the examples in this article for guaranteed investment outcomes. Markets fluctuate, savings rates change, inflation reduces purchasing power, taxes and fees matter, and every investment carries some degree of risk.

    But the fundamental mathematics remains powerful:

    Start early.
    Save consistently.
    Invest intelligently.
    Reinvest.
    Increase your contributions.
    Be patient.

    You do not need to wait until you are rich to begin investing.

    Consistent saving and investing over a long enough period may be one of the ways you build wealth in the first place.

    Educational Disclaimer: This article provides general financial education and does not constitute individualized financial, investment, retirement, tax or legal advice. Hypothetical returns are illustrations only and are not guaranteed. Investments can lose value, including principal. Financial products, taxes and regulations vary by country.

  • The Psychology of Wealth: How Millionaires Think Differently About Money

    The Psychology of Wealth: How Millionaires Think Differently About Money

    Wealth-Building Mindsets, Investing Habits and Long-Term Strategies for Creating Financial Independence

    Introduction

    Wealth Often Begins With a Different Way of Thinking

    Why do some people continually increase their wealth while others earn good incomes for decades yet accumulate relatively few assets?

    Income certainly matters, but income alone does not determine wealth. The way people think about earning, spending, saving, investing, risk, opportunity and time can strongly influence what eventually happens to their money.

    Millionaires are not one homogeneous group, and there is no secret mindset guaranteed to make someone wealthy. Some inherit wealth. Others build businesses, develop high-income careers, invest consistently, own property or combine several strategies. Economic opportunity, education, family circumstances, government policies and luck can also influence outcomes.

    Nevertheless, many financially successful people demonstrate behaviors worth studying: they tend to think beyond today’s paycheck, acquire productive assets, continually improve valuable skills, cultivate useful relationships, manage rather than blindly avoid risk, and understand that sustainable wealth generally requires time.

    Here are some of the most important lessons behind the psychology of wealth and how you can apply them to your own financial journey.

    1. Wealthy Thinking Focuses on Ownership, Not Just Income

    Most people naturally think about money in terms of income:

    How much do I earn every month?

    A wealth-building perspective adds another question:

    What do I own that can potentially increase in value or produce income?

    Someone can earn a large salary and still accumulate little wealth if nearly everything is consumed.

    Another person may earn less but consistently acquire productive assets.

    The distinction between earning money and building assets is fundamental.

    2. Millionaires Often Think in Years, Not Weeks

    Short-term thinking asks:

    What can this money buy today?

    Long-term thinking asks:

    What could this money become over the next 10, 20 or 30 years?

    This does not mean wealthy people never enjoy their money. It means immediate consumption is weighed against future opportunity.

    Time is one of the most powerful resources available to investors and entrepreneurs.

    3. They Understand the Power of Compounding

    Compounding occurs when returns potentially generate additional returns over time.

    Consider a hypothetical example.

    Someone who invests $500 monthly for 30 years and hypothetically earns an average 7% annual return would contribute $180,000 personally, while the account could potentially grow to considerably more because of compounding.

    Actual investment returns are never guaranteed, but the example illustrates an important principle:

    Time can be as important as the amount invested.

    That is why starting earlier can provide a major advantage.

    4. They Pay Themselves Before Expanding Their Lifestyle

    When income increases, many people immediately increase consumption.

    A wealth-building approach directs part of additional income toward assets before upgrading lifestyle.

    Suppose your monthly income rises by $1,000.

    Instead of automatically adding $1,000 to monthly spending, you might allocate part toward investments, emergency savings, education or productive business assets.

    The result is simple:

    Income rises → Asset accumulation rises.

    5. They Understand the Difference Between Looking Rich and Being Wealthy

    Visible consumption can easily be mistaken for wealth.

    A luxury vehicle, designer clothing or expensive home says little about someone’s actual net worth if those purchases are heavily financed.

    Much of genuine wealth is invisible.

    It exists in investment accounts, business ownership, savings, property equity and other assets.

    A powerful psychological shift is learning to value financial independence more than the appearance of financial success.

    6. They Develop Consistent Investing Habits

    Successful long-term investing rarely depends on finding one magical investment.

    It more often involves consistency.

    That can mean regularly allocating money toward diversified investments appropriate to one’s objectives, time horizon and risk tolerance.

    The amount may initially be small.

    The habit comes first.

    As income grows, contributions can potentially grow with it.

    7. They Don’t Confuse Investing With Gambling

    Investing should involve understanding what you own, why you own it, what risks exist and how the investment fits your overall strategy.

    Buying something simply because its price is rising is speculation—not automatically sound investing.

    A wealth-oriented investor asks:

    What is the potential return?
    What could go wrong?
    How much could I lose?
    How long can I hold this investment?
    How does it fit my portfolio?

    Risk is evaluated rather than ignored.

    8. They Read to Solve Problems

    Reading can be one of the least expensive ways to access other people’s knowledge.

    Successful entrepreneurs and investors often learn from books, industry publications, financial reports, biographies, courses, research and other experienced people.

    The important lesson isn’t simply “millionaires read books.”

    It is:

    Successful people continually acquire information that improves their decisions.

    Read with a purpose.

    9. They Invest in Continuous Learning

    The modern economy changes rapidly.

    Technology changes.

    Industries change.

    Consumer preferences change.

    Artificial intelligence changes how certain jobs are performed.

    Skills that were valuable ten years ago may become less valuable, while entirely new opportunities emerge.

    Continuous learning helps protect your earning power.

    10. They Invest in Skills That Increase Their Value

    Not all education has the same economic return.

    Wealth-oriented learners often ask:

    What skill would make me more valuable?

    Depending on your location and industry, that could mean technology, healthcare, manufacturing, engineering, sales, finance, construction, digital marketing, management or entrepreneurship.

    Education becomes particularly powerful when it increases earning capacity.

    11. They Build Valuable Networks

    Relationships create access to information.

    A strong professional network can introduce you to employers, customers, investors, mentors, suppliers, partners and new ideas.

    Effective networking is not collecting hundreds of contacts.

    It is developing genuine, mutually valuable relationships.

    Give value before expecting value in return.

    12. They Learn From People Ahead of Them

    A good mentor can shorten the learning curve.

    Instead of repeating every mistake personally, you can learn from someone else’s experience.

    Ask successful people specific questions.

    What mistakes did they make?

    What skills mattered most?

    What would they do differently?

    Which opportunities do they see developing?

    Experience can provide lessons that textbooks cannot

    13. They Look for Problems Worth Solving

    Entrepreneurship fundamentally revolves around solving problems.

    Successful businesses generally provide something customers value:

    Convenience
    Entertainment
    Transportation
    Food
    Technology
    Education
    Healthcare
    Communication
    Financial services
    Productivity
    Security

    Instead of asking only, “How can I make money?”, entrepreneurs often ask:

    “What problem can I solve profitably?”

    Money becomes the result of creating value.

    14. They Think About Scalability

    An employee typically exchanges time for income.

    Some businesses and investments can potentially generate value without requiring an identical increase in personal hours.

    Software is an example: developing a product may require substantial work initially, but the same software can potentially serve many customers.

    Digital courses, intellectual property, media, automated systems and certain business models may offer similar scalability.

    Scalability is one reason entrepreneurship can create significant wealth—but it also involves considerable risk.

    15. They Develop Multiple Income Streams Carefully

    Depending exclusively on one income source can create vulnerability.

    Potential income sources include:

    Employment income
    Business income
    Freelance income
    Investment income
    Rental income
    Royalties
    Interest
    Dividends

    You do not need seven income streams immediately.

    Trying to build everything simultaneously can actually reduce progress.

    Establish one reliable income source and gradually diversify when appropriate.

    16. They Turn Income Into Assets

    This is one of the most important wealth-building habits.

    Consider two people who each receive an additional $10,000.

    One spends it entirely.

    The other uses some for enjoyment but directs the remainder toward investments, business equipment, education or another productive asset.

    The difference becomes larger when this behavior is repeated for decades.

    Wealth is not simply what flows into your hands.

    17. They Monitor Net Worth

    Income measures earnings.

    Net worth measures:

    Assets – Liabilities = Net Worth

    Tracking net worth can provide a clearer picture of long-term financial progress than salary alone.

    Review it periodically.

    Is debt falling?

    Are savings increasing?

    Are investments growing?

    Are productive assets accumulating?

    The direction matters.

    18. They Respect Cash Flow

    A business can appear successful yet fail because it cannot meet immediate obligations.

    A household can face the same problem.

    Wealthy financial management pays close attention to cash flow:

    Money coming in versus money going out.

    Knowing your cash flow helps you determine how much can realistically be saved, invested or reinvested.

    19. They Maintain Emergency Liquidity

    Investing every available dollar may sound aggressive, but emergencies require accessible money.

    A financial reserve can prevent someone from having to sell long-term investments at an unfavorable time or borrow at expensive interest rates.

    Wealth building requires both growth and resilience.

    20. They Take Calculated Risks

    Avoiding every risk can limit opportunity.

    Taking every risk can destroy wealth.

    The better approach is calculated risk.

    Before making a significant decision, consider:

    Potential upside
    Potential downside
    Probability of failure
    Maximum possible loss
    Time horizon
    Alternative options

    Successful wealth building is often about deciding which risks are worth taking.

    21. They Protect Against Catastrophic Losses

    Making money receives enormous attention.

    Protecting money deserves equal attention.

    Depending on circumstances, protection can involve emergency reserves, appropriate insurance, diversification, cybersecurity, legal structures and careful debt management.

    One catastrophic event can erase years of financial progress.

    Risk management is therefore part of wealth creation.

    22. They Avoid Concentrating Everything in One Place

    No investment is guaranteed.

    Putting nearly all your wealth into one company, asset, business, cryptocurrency or property can create enormous concentration risk.

    Diversification spreads exposure across different assets or investments.

    It cannot eliminate market losses, but it can help manage the consequences of one investment performing badly.

    23. They Protect Their Reputation

    Trust is an economic asset.

    Business owners need customers to trust them.

    Professionals need employers and colleagues to trust them.

    Investors need partners.

    A reputation for reliability, honesty and competence can produce opportunities for decades.

    Short-term dishonesty can destroy long-term economic value.

    24. They Understand Taxes and Financial Rules

    Ignoring taxes can become expensive.

    Financially sophisticated people understand the basic tax consequences of income, investments, businesses and major transactions.

    Tax systems vary dramatically around the world, so qualified local professional guidance can be important.

    The goal should be lawful tax planning—not illegal tax avoidance or concealment.

    25. They Make Decisions Based on Value, Not Only Price

    Cheap does not always mean economical.

    An inexpensive tool that constantly breaks may cost more than a durable one.

    Likewise, the most expensive option isn’t automatically superior.

    A wealth-building mindset considers:

    Price + Quality + Durability + Productivity + Opportunity Cost

    The objective is maximizing value.

    26. They Understand Opportunity Cost

    Every financial decision eliminates another possibility.

    Spending $20,000 on a luxury purchase means that same $20,000 cannot simultaneously finance education, an investment or a business.

    This doesn’t automatically make the purchase wrong.

    It simply means every significant purchase should be evaluated against what else the money could accomplish.

    27. They Protect Their Time

    Money can be earned again.

    Time cannot.

    Financially successful people often become increasingly selective about where their time goes.

    They automate repetitive work, delegate when economically sensible and prioritize high-value activities.

    Ask yourself:

    Which activities create the greatest improvement in my income, skills or future opportunities?

    Give those activities priority.

    28. They Use Money to Buy Options

    One of wealth’s greatest benefits is freedom of choice.

    Financial reserves can allow someone to:

    Leave an unsuitable job.

    Move to another location.

    Start a business.

    Return to school.

    Care for family.

    Take a career risk.

    Retire.

    The objective of wealth does not have to be luxury.

    It can be control over your time and decisions.

    29. They Define Financial Independence

    Financial independence means different things to different people.

    For one person it may mean becoming debt-free.

    For another, owning a home without a mortgage.

    Another may want enough investments to cover living expenses without employment.

    Define your own target.

    Without a definition, “more money” can become an endless pursuit.

    30. They Don’t Expect Overnight Wealth

    Social media frequently compresses a ten-year journey into a 30-second success story.

    Real wealth often takes much longer.

    Careers take years to develop.

    Businesses take time to mature.

    Investments need time to compound.

    Patience is not inactivity.

    It is continuing the right behaviors long enough for them to produce meaningful results.

    31. They Learn From Financial Mistakes

    Successful entrepreneurs and investors make mistakes.

    Businesses fail.

    Investments lose money.

    Products flop.

    Hiring decisions go wrong.

    The important question is:

    What did this mistake teach me?

    A mistake becomes especially expensive when nothing is learned from it.

    32. They Preserve Wealth After Creating It

    Making money and keeping money require different skills.

    Once meaningful wealth has been accumulated, priorities may gradually shift from aggressive growth toward a combination of growth, income, diversification, liquidity and capital preservation.

    Someone approaching retirement, for example, may have different risk needs from someone beginning a career.

    Wealth strategy should evolve with circumstances.

    33. They Think About Legacy

    Wealth can outlive its creator.

    Legacy planning may involve family, charitable giving, education, businesses, property, investments or community impact.

    Financial legacy also includes knowledge.

    Teaching children how to budget, save, invest and manage risk may be as important as transferring assets.

    34. They Create Systems That Can Continue Without Them

    Successful entrepreneurs eventually ask:

    Can this organization function without my constant presence?

    Documented processes, trained employees, technology, delegation and management systems can transform self-employment into a more durable enterprise.

    A business completely dependent on its founder may have limited transferable value.

    35. They Think in Generations

    Long-term wealth planning can extend beyond retirement.

    How can assets benefit children or future generations?

    How can a business continue?

    How should property be transferred?

    How can heirs be financially educated?

    Building wealth without preparing future generations to manage it can undermine the legacy.

    Lessons From Successful Entrepreneurs

    There is no single formula behind successful entrepreneurs, but several recurring principles deserve attention.

    Warren Buffett is strongly associated with long-term investing, patience and focusing on businesses rather than short-term market excitement.

    Sara Blakely built her company from a product idea aimed at solving a specific consumer problem, illustrating the entrepreneurial importance of identifying unmet needs and persistently developing solutions.

    Oprah Winfrey transformed expertise and audience trust into a much broader media and business platform, demonstrating the potential economic value of reputation, communication skills and intellectual property.

    Their circumstances and paths were very different. The lesson is not to imitate their exact investments or businesses. It is to study broader principles: create value, think long term, learn continuously, protect your reputation and reinvest intelligently.

    Case Study 1: The High-Income Spender

    Imagine James earns $120,000 annually but increases his lifestyle every time his salary rises.

    After many years, his income looks impressive but his net worth remains relatively modest.

    He changes one behavior: every future salary increase is divided between lifestyle improvement and asset accumulation.

    His income hasn’t suddenly transformed.

    His relationship between income and ownership has.

    Case Study 2: The Consistent Investor

    Maria earns considerably less than James but begins regularly investing a manageable percentage of her income for long-term goals.

    As her salary rises, she gradually increases her contributions.

    She avoids chasing every market trend and maintains emergency savings separately.

    Her advantage is not secret investment knowledge.

    It is consistency + diversification + patience + time.

    Case Study 3: The Entrepreneur Who Starts Small

    Daniel wants to start a food business.

    Instead of immediately borrowing heavily for a restaurant, he tests demand by selling a limited menu through pre-orders.

    Customers respond positively.

    He reinvests profits into equipment, improves packaging, builds repeat customers and expands gradually.

    His wealth-building lesson is:

    Test → Learn → Generate revenue → Reinvest → Scale.

    Starting small allowed him to gather evidence before taking larger risks.

    The Wealth-Building Cycle

    The psychology of wealth can be summarized through a repeating cycle:

    Learn → Increase Your Value → Earn → Control Spending → Save → Acquire Productive Assets → Invest → Protect → Reinvest → Repeat

    The cycle can operate at almost any income level, although the speed will differ dramatically according to earnings and circumstances.

    Someone earning a low income may need to concentrate first on skills and increasing earnings.

    Someone with strong income but no savings may need to control lifestyle inflation.

    Someone with substantial assets may need to focus more heavily on diversification and wealth preservation.

    The correct strategy depends on where you are today.

    How to Start Thinking Differently About Money Today

    You don’t need to become a millionaire before adopting stronger financial habits.

    Begin by asking yourself five questions:

    1. What percentage of my income am I keeping?

    2. Which valuable skill could increase my earning power?

    3. What productive assets am I accumulating?

    4. What financial risks could seriously damage my progress?

    5. Where could consistent action put me in 10 years?

    Write down the answers.

    Then identify one change you can begin this month.

    Perhaps you automate savings.

    Maybe you begin professional training.

    Perhaps you finally calculate your net worth.

    Maybe you reduce expensive debt.

    Or perhaps you begin researching long-term investments appropriate to your circumstances.

    The action does not need to be dramatic.

    It needs to move you in the right direction.

    Conclusion

    Wealth Is Built Through Behavior, Assets and Time

    The psychology of wealth is not about pretending that positive thinking alone creates money.

    It doesn’t.

    Wealth creation is influenced by income, education, opportunity, geography, economic conditions, family circumstances, access to capital, government policy and sometimes luck.

    But behavior still matters enormously.

    People who build sustainable wealth often learn to think beyond immediate consumption. They continually improve their earning ability, acquire productive assets, invest for long-term goals, manage risk, develop strong networks, learn from mistakes and resist unnecessary lifestyle inflation.

    Most importantly, they understand the difference between earning money and owning wealth.

    Your goal does not have to be becoming a millionaire.

    Your goal can be something more meaningful:

    Greater security.
    Greater independence.
    Greater control over your time.
    More opportunities for your family.
    And the ability to make decisions based on what you value rather than what you can afford this week.

    Start where you are.

    Learn continuously. Increase your value. Control what you spend. Build assets. Manage risk. Think long term.

    Because sustainable wealth is rarely created by one extraordinary financial decision.

    It is usually built through ordinary intelligent decisions repeated for an extraordinary amount of time.

    Educational Disclaimer: This article provides general financial education and does not constitute individualized investment, financial, tax or legal advice. Investing involves risk, including possible loss of principal. Investment products, taxes, regulations and consumer protections vary by country.

  • How to Become Financially Independent Before Age 40

    How to Become Financially Independent Before Age 40

    A Practical Roadmap to Saving, Investing, Multiple Income Streams and Long-Term Financial Freedom

    Introduction

    Financial Independence Is About Freedom, Not Just Becoming Rich

    Imagine reaching your late 30s and knowing that losing your job would not immediately threaten your home, food, healthcare or basic lifestyle. Imagine having enough savings, investments, business income or other assets that employment becomes a choice rather than your only means of financial survival.

    That is the basic idea behind financial independence.

    Becoming financially independent before age 40 is an ambitious goal, and it will not be realistic for everyone. Income levels, family responsibilities, housing costs, healthcare systems, taxes, economic conditions and access to investment opportunities differ dramatically around the world.

    However, the principles behind financial independence can benefit almost anyone—even if reaching complete independence happens at 45, 55 or later.

    The journey generally requires several things working together:

    Increasing income.
    Controlling expenses.
    Saving consistently.
    Investing for long-term growth.
    Building assets.
    Avoiding destructive debt.
    Creating additional income sources.
    Giving compound growth enough time to work.

    Financial independence rarely comes from one brilliant investment. It is usually the result of hundreds of sensible financial decisions repeated for many years

    What Does Financial Independence Mean?

    Financial independence generally means reaching a position where your accumulated financial resources and sustainable income sources can support your living expenses without depending entirely on employment.

    It does not necessarily mean never working again.

    Many financially independent people continue working because they enjoy their careers, run businesses, pursue creative projects or want to continue accumulating wealth.

    The difference is choice.

    A financially independent person may have income from investments, businesses, property or other assets that reduces dependence on a monthly salary.

    A useful starting point is calculating your current financial position:

    Net Worth = Total Assets − Total Liabilities

    Assets may include cash, investments, retirement accounts, business interests and property equity. Liabilities can include credit-card debt, personal loans, student loans, mortgages and other financial obligations.

    The Consumer Financial Protection Bureau provides educational resources for building savings, while Investor.gov provides beginner-friendly information about investing and financial markets.

    Understanding the FIRE Movement

    FIRE stands for Financial Independence, Retire Early.

    The movement became popular among people who wanted an alternative to the traditional pattern of working until their 60s before gaining significant control over their time.

    FIRE followers often focus on three major principles:

    Earn more.
    Spend intentionally.
    Invest the difference.

    Some pursue very high savings rates and deliberately maintain modest lifestyles so they can invest a substantial percentage of their income.

    However, FIRE does not have to mean extreme deprivation.

    Different approaches include:

    Lean FIRE — achieving independence with relatively low annual expenses.

    Fat FIRE — accumulating enough wealth to maintain a more expensive lifestyle.

    Coast FIRE — accumulating enough investments relatively early so that, assuming sufficient future growth, additional retirement contributions may eventually become less important.

    Barista FIRE — accumulating substantial assets but continuing some employment or business activity to cover part of current expenses.

    Whichever version appeals to you, remember that future investment returns are uncertain. The Investor.gov retirement resources can help explain retirement planning, while the FINRA retirement resources provide additional education about long-term investing and retirement.

    Increase Your Income Before Trying to Cut Everything

    Reducing unnecessary expenses is useful, but there is a limit to how much you can cut.

    Income has much greater upside.

    Suppose someone earns $2,000 per month and already spends $1,700 on essential living costs. Extreme budgeting has limited potential.

    Increasing income to $3,000 or $4,000 could transform that person’s ability to save and invest.

    Ways to increase earning potential may include:

    • Professional certifications
    • Technical skills
    • Skilled trades
    • Sales
    • Healthcare careers
    • Technology
    • Management
    • Freelancing
    • Digital marketing
    • Entrepreneurship
    • Online services
    • Consulting

    Ask yourself:

    What skill could increase my income significantly over the next three years?

    Investing in your earning ability can sometimes produce a greater initial financial impact than obsessing over tiny spending reductions.

    Diversify Your Income Sources

    Depending entirely on one employer creates concentration risk.

    If that job disappears, your entire primary income may disappear with it.

    Income diversification means gradually developing additional ways of earning money.

    Potential income streams include:

    Employment income
    Freelance income
    Business profits
    Investment income
    Rental income
    Interest
    Dividends
    Royalties
    Digital products

    You do not need to create seven income streams immediately.

    That can actually become counterproductive.

    Start by strengthening your primary income. Then develop one additional source that fits your abilities, available time, capital and market opportunities.

    Eventually, multiple income streams can provide greater financial resilience and accelerate wealth accumulation.

    Save Aggressively—but Sustainably

    Your savings rate is one of the most important variables in the financial-independence journey.

    If someone earns $50,000 and saves $2,500 annually, the savings rate is approximately 5%.

    If that person saves $15,000, it is approximately 30%.

    Higher savings rates can dramatically accelerate asset accumulation, although taxes and definitions of income need to be considered when making precise calculations.

    Aggressive saving does not mean ignoring health, nutrition, family responsibilities or basic quality of life.

    Instead, focus first on major recurring expenses:

    Housing
    Transportation
    Food
    Debt
    Insurance
    Subscriptions
    Utilities

    Saving $300 every month on a major recurring expense is generally more powerful than occasionally saving $3 on coffee.

    The CFPB savings resources provide practical saving guidance, while the FDIC’s Money Smart program provides broader financial education.

    Build an Emergency Fund Before Aggressive Investing

    Financial independence requires resilience as well as growth.

    Before putting all available money into long-term investments, establish accessible emergency savings.

    An emergency fund can help cover unexpected expenses such as job loss, medical costs, urgent repairs or temporary income disruption.

    Without one, you may be forced to borrow or sell investments during unfavorable market conditions.

    The CFPB emergency-fund guide explains how dedicated emergency savings can protect against financial shocks, while FINRA provides educational resources for people preparing to invest.

    Invest Wisely for Long-Term Growth

    Saving builds capital.

    Investing gives that capital an opportunity to grow.

    Long-term investments can include diversified stock and bond funds and other regulated investment products appropriate to your country, circumstances, objectives and risk tolerance.

    The objective is not to chase whatever asset has recently produced spectacular returns.

    Ask:

    What am I investing in?
    How does it generate value?
    What are the fees?
    What risks am I taking?
    How diversified am I?
    When will I need this money?

    Diversification can help manage investment risk, although it cannot guarantee profits or eliminate losses. Investor.gov explains diversification, while FINRA’s investing resources provide additional education on investing and risk.

    Understand the Power of Compound Growth

    Compound growth means your investment returns can potentially generate additional returns.

    Imagine investing $500 every month for 20 years.

    Your personal contributions would total:

    $500 × 12 × 20 = $120,000

    If those investments earned a hypothetical average return over time, the eventual value could be significantly higher because returns may compound.

    The example is illustrative rather than a promise of future performance.

    The key lesson is:

    Money + Return + Time = Potential Compound Growth

    Starting earlier gives compounding more time to operate.

    Investor.gov provides a useful compound interest calculator for experimenting with different contribution amounts, time periods and hypothetical returns.

    Create Passive and Semi-Passive Income Carefully

    “Passive income” is one of the most overused phrases online.

    Most income streams require something first:

    Money, time, expertise, systems—or all four.

    Potential sources can include dividends, interest, rental property, royalties, licensing, digital products and businesses that eventually operate with limited owner involvement.

    But none should automatically be assumed to be effortless.

    Rental property requires maintenance and management.

    Dividend-paying companies can reduce dividends.

    Businesses can fail.

    Digital products require development and marketing.

    Instead of asking:

    “How can I make money without working?”

    Ask:

    “What asset or system can I build today that may continue generating value later?”

    That is a much stronger approach to passive income.

    Use Digital Business to Expand Your Opportunities

    The internet has reduced some barriers to entrepreneurship.

    A person can potentially serve customers beyond their immediate town or country through:

    • Freelance services
    • Online education
    • Digital publishing
    • Software
    • Content businesses
    • E-commerce
    • Consulting
    • Affiliate marketing
    • Graphic design
    • Marketing services
    • Subscription businesses

    Digital business is not automatic income.

    Competition is intense, and success generally requires useful skills, customer demand, marketing, persistence and continuous improvement.

    But digital distribution can give entrepreneurs access to markets that were previously impossible to reach without substantial capital.

    Entrepreneurship Can Accelerate Financial Independence

    Employment usually provides more predictable income.

    Entrepreneurship can provide greater upside—but greater risk.

    A successful business may create income and an asset that has value beyond the founder’s salary.

    However, businesses can also lose money.

    A safer approach for many beginners is:

    Identify a problem → Test demand → Start small → Generate sales → Improve → Reinvest → Scale

    Avoid borrowing enormous amounts of money simply because you have an exciting idea.

    Customers—not enthusiasm alone—validate a business.

    Build evidence before increasing risk.

    Avoid Lifestyle Inflation

    Lifestyle inflation happens when expenses automatically rise alongside income.

    You earn $3,000 monthly and spend $2,900.

    Your income increases to $4,000—and eventually you spend $3,900.

    Then you earn $5,000 and spend $4,900.

    Your salary grows, but your wealth barely changes.

    One powerful strategy is to establish a raise allocation rule.

    For example:

    Whenever income increases, automatically direct part of the increase toward investments or other financial goals before increasing lifestyle spending.

    You can still improve your standard of living.

    The objective is simply to make sure your assets rise when your income rises.

    Eliminate Expensive Consumer Debt

    High-interest debt can work against financial independence.

    If an investment hypothetically earns 7% while a credit-card balance costs substantially more in interest, the expensive debt can overwhelm investment progress.

    Prioritize high-cost consumer debt while continuing to maintain appropriate emergency reserves and considering any important employer benefits available to you.

    Once expensive debt disappears, redirect the former monthly payment toward savings and investments.

    Do not simply absorb it into lifestyle spending.

    Plan for Retirement Even If You Want to Retire Early

    Early financial independence requires more retirement planning—not less.

    Someone planning to stop traditional employment at 40 may need assets to support decades of future expenses.

    Consider:

    Housing
    Food
    Healthcare
    Taxes
    Insurance
    Inflation
    Family responsibilities
    Investment volatility
    Longevity
    Unexpected expenses

    Retirement rules, pensions and tax-advantaged accounts vary by country. U.S. readers can explore Investor.gov’s retirement toolkit, while readers elsewhere should consult their country’s official pension, tax and financial regulators.

    Do not assume today’s expenses will remain unchanged for 40 years.

    Calculate Your Financial Independence Number Carefully

    A popular FIRE concept is estimating how large a portfolio might be needed to support annual spending.

    You may encounter simplified rules such as multiplying annual expenses by 25, which corresponds to an initial 4% withdrawal assumption.

    For example:

    $40,000 annual expenses × 25 = $1,000,000

    But this should not be treated as a guarantee.

    Taxes, inflation, investment returns, retirement duration, healthcare expenses, portfolio allocation and future spending can materially change outcomes.

    Someone retiring at 40 potentially faces a much longer retirement horizon than someone retiring at 65.

    Use withdrawal rules as planning tools—not promises.

    Build Assets, Not Just a Bigger Salary

    But financial independence ultimately depends more on what you own relative to what you need to spend.

    Assets may include:

    Investments
    Business ownership
    Property equity
    Cash reserves
    Retirement assets
    Intellectual property

    Someone earning $150,000 while spending $145,000 may be less financially resilient than someone earning $80,000, living on $45,000 and consistently acquiring productive assets.

    Income provides the fuel.

    Asset ownership helps build independence.

    Protect the Wealth You Are Building

    Building financial independence without risk management can leave years of progress vulnerable.

    Depending on your circumstances, protection may include:

    Emergency savings
    Appropriate insurance
    Diversification
    Secure passwords and cybersecurity
    Estate planning
    Responsible debt management
    Tax planning

    Avoid putting your entire financial future into one stock, cryptocurrency, property, employer or business.

    Building wealth and protecting wealth should happen together.

    A Financial Freedom Roadmap: From Starting Point to Independence

    Stage 1: Stabilize Your Finances

    Track income and expenses.

    Create a basic budget.

    Stop accumulating unnecessary high-interest debt.

    Build your first emergency reserve.

    Stage 2: Increase Your Financial Capacity

    Improve valuable skills.

    Negotiate compensation where appropriate.

    Pursue career advancement.

    Build an additional income source.

    Stage 3: Increase Your Savings Rate

    Automate savings.

    Control major recurring expenses.

    Avoid unnecessary lifestyle inflation.

    Save part of every income increase.

    Stage 4: Begin Long-Term Investing

    Understand risk.

    Choose regulated investments appropriate to your circumstances.

    Diversify.

    Keep fees in mind.

    Invest consistently rather than emotionally chasing markets.

    Stage 5: Build Additional Assets and Income

    Develop a business if appropriate.

    Build digital assets.

    Acquire productive investments.

    Reinvest part of additional income.

    Stage 6: Protect Your Progress

    Maintain emergency reserves.

    Review insurance.

    Diversify assets.

    Avoid catastrophic financial risks.

    Stage 7: Calculate Your Independence Target

    Estimate future annual expenses.

    Consider taxes and inflation.

    Estimate healthcare and family obligations.

    Review potential retirement income.

    Model several investment-return scenarios rather than assuming one outcome.

    Stage 8: Review Your Progress Every Year

    Calculate:

    Net worth
    Savings rate
    Investment contributions
    Debt
    Annual expenses
    Additional income
    Progress toward your financial-independence target

    Then adjust the strategy.

    A Hypothetical Journey to Financial Independence Before 40

    Consider Maya, age 25.

    She has a full-time job but little invested.

    Instead of expecting instant wealth, she develops a 15-year strategy.

    From 25–28, she focuses on eliminating expensive debt, building emergency savings and developing a higher-income professional skill.

    From 28–32, her income increases. Instead of upgrading every aspect of her lifestyle, she invests a meaningful portion of the additional income.

    From 32–35, she develops a small digital business alongside employment and invests part of the profits.

    From 35–38, she continues accumulating diversified assets while keeping living expenses manageable.

    By 38–40, her investments and additional income sources have grown substantially.

    Whether she reaches complete financial independence depends on her income, savings rate, investment performance, expenses and circumstances.

    But even if she reaches only 60% or 70% of her original target, she may still be dramatically more financially secure than when she started.

    That is an important lesson:

    Financial independence is not all-or-nothing.

    Every step toward it increases your financial options.

    The Financial Independence Formula

    The entire strategy can be summarized as:

    Learn → Earn More → Spend Intentionally → Save → Invest → Build Assets → Diversify Income → Protect Wealth → Reinvest → Repeat

    Do this for long enough, and the relationship between your work and your money can begin to change.

    At first:

    You work for money.

    Eventually:

    Your accumulated assets can begin working alongside you.

    The ultimate objective is reaching the point where those assets can support a meaningful portion—or eventually all—of your financial needs.

    Conclusion

    Financial Independence Before 40 Requires a Plan, Not a Miracle

    Becoming financially independent before age 40 is ambitious.

    It usually requires much more than finding the perfect investment.

    You need to understand your expenses, increase your earning power, maintain a strong savings rate, control lifestyle inflation, avoid destructive debt, build emergency reserves and invest consistently.

    You may also accelerate progress through entrepreneurship, digital business and carefully developed additional income streams.

    Most importantly, give yourself time.

    Compound growth needs time.

    Businesses need time.

    Careers need time.

    Skills need time.

    Financial independence is built by repeatedly converting income into assets and assets into greater financial freedom.

    If you are 20, start now.

    If you are 30, start now.

    If you are already over 40, the principles remain valuable. The objective is not to compete with someone else’s age or net worth.

    The objective is to make your future financially stronger than your present.

    Earn intentionally. Save aggressively but sustainably. Invest intelligently. Build assets. Protect what you create. And keep moving toward the point where money gives you more control over your life rather than less.

    Educational Disclaimer: This article is for general educational purposes and does not constitute individualized financial, investment, tax, retirement or legal advice. Investments involve risk, including possible loss of principal. Financial products, retirement systems, taxes and regulations vary by country.

  • How to Escape Poverty: 35 Practical Financial Habits That Change Lives

    How to Escape Poverty: 35 Practical Financial Habits That Change Lives

    A Step-by-Step Guide to Building Skills, Increasing Income, Managing Money and Creating Long-Term Financial Security

    Introduction

    Breaking the Cycle of Poverty Starts With a Practical Plan

    Escaping poverty is rarely the result of one lucky opportunity, one investment, or one dramatic increase in income. For most people, improving their financial position is a gradual process involving better skills, stronger financial habits, increased earning capacity, careful spending, savings, productive relationships, and long-term planning. At the same time, poverty is not caused solely by individual choices. Job availability, wages, education, economic conditions, access to banking, family responsibilities, health costs, inflation, and where a person lives can significantly affect financial opportunity.

    That means there is no universal formula guaranteed to move everyone out of poverty. However, there are practical financial habits that can improve your ability to manage limited resources, pursue opportunities, withstand emergencies, and gradually build assets.

    Whether you live in the United States, Canada, Europe, Australia, Africa, Asia, Latin America, the Caribbean, or elsewhere, these 35 practical financial habits can help you develop a stronger financial foundation and work toward greater economic independence.

    1. Understand What Poverty Really Means

    Poverty is more complicated than simply “not having enough money.”

    It can include inadequate or unstable income, limited savings, high debt, lack of access to education, unemployment or underemployment, insecure housing, limited access to financial services, and an inability to absorb emergencies.

    Understanding your particular financial situation is the first step toward changing it.

    Write down your income, essential expenses, debts, assets, skills, and financial obligations. You cannot build an effective plan until you know your starting point.

    2. Replace a Poverty Mindset With a Growth-Oriented Money Mindset

    A so-called “poverty mindset” should not be used to blame people for circumstances outside their control.

    A more useful concept is developing a growth-oriented financial mindset.

    Instead of thinking, “I will never earn enough,” ask:

    What valuable skill can I learn?
    How could I increase my income?
    Which expenses can I control?
    What opportunities exist around me or online?
    What can I start doing today?

    A wealth-building mindset focuses on possibilities while remaining realistic about risks and circumstances.

    3. Treat Education as an Investment

    Education can extend far beyond earning a university degree.

    Vocational training, apprenticeships, professional certifications, community colleges, technical institutes, online courses, employer training, and self-directed learning can all increase your economic value.

    Before paying for training, ask whether employers actually demand the skill and whether the likely income improvement justifies the cost.

    The goal is not collecting certificates. The goal is acquiring marketable knowledge.

    4. Build Employable Skills

    Learn skills people or businesses are willing to pay for.

    Depending on your location, opportunities could include healthcare, construction, plumbing, electrical work, welding, manufacturing, bookkeeping, sales, logistics, digital marketing, software development, data analysis, graphic design, caregiving, culinary work, agriculture, or equipment operation.

    Study local job advertisements. Look for qualifications that repeatedly appear.

    Then build those qualifications systematically.

    5. Learn One High-Value Skill Deeply

    Trying to learn ten skills simultaneously often produces shallow knowledge.

    Choose one marketable skill and become competent enough to earn from it.

    For example, instead of vaguely “learning computers,” you could learn bookkeeping software, web development, spreadsheet analysis, video editing, digital advertising, or another specific skill.

    Specialized competence can make you more valuable than general familiarity.

    6. Increase Your Primary Income

    Cutting expenses has limits. Income growth has much greater potential.

    Ask whether you can:

    • Work additional hours
    • Move into a higher-paying position
    • Earn a professional certification
    • Negotiate compensation
    • Change employers
    • Learn a trade
    • Develop a specialized skill
    • Relocate where economically realistic
    • Pursue remote employment

    Even a modest permanent increase in monthly income can significantly change your financial trajectory if lifestyle expenses do not increase equally.

    7. Diversify Your Sources of Income

    Depending entirely on one income source creates vulnerability.

    A second source might include freelance work, weekend employment, tutoring, consulting, agriculture, delivery work, selling products, online services, or a small business.

    Do not try everything simultaneously. Build one additional reliable income stream before adding another.

    8. Create a Realistic Budget

    A budget is a plan for your money.

    Start with:

    Income – Essential expenses – Debt obligations – Savings = Available discretionary money

    Track housing, food, transportation, utilities, communication, healthcare, education, debt, and other necessities.

    Budgeting cannot solve inadequate income by itself, but it can help you use available income more intentionally.

    9. Track Where Your Money Goes

    Track every expense for 30 days.

    Small daily purchases can become significant monthly expenses.

    You may discover unused subscriptions, excessive transportation costs, unnecessary fees, frequent takeout meals, impulse purchases, or other expenses that can be reduced.

    Do not guess where your money goes. Measure it.

    10. Set Specific Financial Goals

    Replace vague goals such as “I want to become rich” with measurable targets.

    For example:

    “I will save $1,000 within 10 months.”

    Or:

    “I will complete my professional certification by June and apply for five higher-paying positions every week.”

    A goal needs an amount, action, and deadline whenever possible.

    11. Save Before Increasing Your Lifestyle

    When your income rises, resist immediately upgrading everything.

    This phenomenon is often called lifestyle inflation.

    If your income increases by $200 per month, consider directing part of that increase toward savings, debt reduction, education, or investment before increasing discretionary spending.

    This is one of the most powerful ways to convert higher income into actual financial progress.

    12. Practice Delayed Gratification

    Learn to distinguish “I want it” from “I need it now.”

    For nonessential purchases, wait 24 hours before buying. For expensive purchases, wait several days.

    Investor.gov similarly suggests a 24-hour waiting rule for impulse purchases and explains how small recurring savings can accumulate over time.

    Delayed gratification is not about never enjoying money. It is about controlling when and why you spend it.

    13. Build Your First Emergency Fund

    An emergency fund protects you when life becomes unpredictable.

    Start with an achievable amount—perhaps $100, $500, or the equivalent in your local currency. Then work toward a larger reserve based on your essential expenses and circumstances.

    An emergency fund can reduce the need to borrow when your vehicle breaks down, work hours are reduced, or another unexpected expense occurs.

    Investor.gov identifies an emergency fund as an important component of long-term financial security.

    14. Avoid High-Cost Consumer Debt

    Debt can either support productive goals or destroy financial progress.

    High-interest consumer debt is particularly dangerous because interest consumes future income.

    Before borrowing, ask:

    Will this debt help me generate income or build something valuable—or am I borrowing simply to consume something today?

    Investor.gov recommends aggressively addressing high-interest debt because interest charges can significantly interfere with saving and wealth building.

    15. Pay Bills on Time

    Late fees are money lost without receiving anything valuable in return.

    Create reminders, calendar alerts, or automatic payments where appropriate and safe.

    Good payment habits can also contribute to stronger creditworthiness in countries where formal credit reporting systems are used.

    16. Read About Personal Finance Regularly

    Financial education is a lifelong process.

    Read books and reputable resources about budgeting, saving, investing, entrepreneurship, taxes, insurance, debt, and retirement.

    Do not rely solely on social-media influencers.

    For introductory investing education, Investor.gov provides free information about saving, investing, diversification, risk, and financial planning.

    17. Build Relationships With Ambitious People

    Your network can expose you to opportunities you might never discover alone.

    Build genuine relationships with employers, entrepreneurs, skilled workers, former classmates, professional organizations, community leaders, and people working in industries you want to enter.

    Networking is not begging people for jobs.

    It means developing relationships in which information, experience, referrals, and opportunities can be shared.

    18. Find Mentors

    A good mentor can help you avoid expensive mistakes.

    Look for someone with genuine experience in the field you want to enter.

    Ask specific questions:

    What skills should I learn?
    What mistakes should I avoid?
    What would you do if you were starting today?

    Be cautious of anyone demanding large payments while promising guaranteed wealth.

    19. Consider Entrepreneurship Carefully

    Entrepreneurship can create income and assets, but it also carries risk.

    Start by solving a real problem.

    Instead of asking, “What business should I start?”, ask:

    “What problem are people willing to pay me to solve?”

    Test your idea inexpensively before investing substantial money.

    A small profitable business is better than an impressive business that constantly loses money.

    20. Start Small Before Borrowing Big

    Many businesses can initially be tested at small scale.

    A baker might begin with pre-orders. A designer can start freelancing. A tutor can find a few students. A farmer can test a higher-value crop on a limited area.

    Validate demand before taking significant debt.

    Revenue should prove the idea whenever possible.

    21. Explore Digital Opportunities

    he internet has expanded the geographic reach of employment and entrepreneurship.

    Potential opportunities include freelancing, remote customer support, online tutoring, e-commerce, digital marketing, software development, content creation, bookkeeping, translation, virtual assistance, and consulting.

    Digital financial services can also expand access to payments and financial products. The World Bank notes that such services can reduce costs and increase transaction speed and access, while also introducing risks including privacy, cybersecurity, and predatory lending.

    22. Learn How AI Can Increase Your Productivity

    Artificial intelligence is creating new ways to work faster and develop services.

    AI tools may assist with research, writing, translation, data organization, customer service, coding, marketing, design concepts, and administrative tasks.

    The opportunity is not simply “make money with AI.”

    Learn how to combine AI with a valuable human skill.

    For example:

    Marketing skill + AI
    Bookkeeping knowledge + AI
    Programming + AI
    Design + AI
    Research + AI

    AI should amplify useful skills rather than replace the need to develop them.

    23. Use Social Media as a Business Tool

    Social media does not have to be only entertainment.

    It can help you build professional visibility, demonstrate skills, attract customers, market a small business, develop a portfolio, or connect with employers.

    Choose a niche, publish useful content consistently, and build credibility.

    Do not assume followers automatically equal income.

    24. Protect Your Time

    Time is an economic resource.

    Entertainment and social media can consume hours that could otherwise be used for studying, job applications, building a side business, networking, exercising, or learning.

    You do not need to eliminate recreation.

    Simply become intentional about where your hours go.

    25. Start Investing Only When You Understand the Risk

    Investing can help build long-term wealth, but investments can lose money.

    Before investing, understand the product, fees, risks, liquidity, and time horizon.

    Investor.gov explains that asset allocation and diversification can help manage investment risk, although diversification cannot guarantee against losses.

    Never invest money needed for rent, food, emergencies, or immediate obligations in volatile assets.

    26. Start Small With Investments

    You do not necessarily need a large fortune to begin investing where suitable regulated options are available.

    A small regular contribution can develop the habit.

    Investor.gov summarizes long-term wealth building with the principle that regular investments plus time can create wealth, while emphasizing that all investments involve risk.

    The exact products available depend on your country and regulatory system.

    27. Avoid Get-Rich-Quick Schemes

    Financial desperation makes people especially vulnerable to scams.

    Be suspicious of:

    • Guaranteed investment returns
    • “Risk-free” high profits
    • Secret trading systems
    • Pressure to invest immediately
    • Unlicensed investment operators
    • Requests to recruit others primarily to earn money
    • Fake cryptocurrency opportunities

    Investor.gov identifies promises of high returns with little or no risk, urgency, FOMO, and suspicious payment methods as common fraud warning signs.

    Protecting your existing money is part of escaping poverty.

    28. Build Assets Instead of Only Buying Liabilities

    Ask whether your money is purchasing something that can improve your financial position.

    Assets may include appropriate investments, productive equipment, business inventory, intellectual property, education that improves earnings, or property depending on circumstances.

    Not every asset generates income, and not every purchase commonly called an “asset” will appreciate.

    Evaluate purchases based on their real economic value to you.

    29. Protect Yourself With Appropriate Insurance

    One serious event can erase years of financial progress.

    Depending on your country and circumstances, appropriate health, vehicle, property, disability, business, crop, or life insurance may protect against catastrophic losses.

    Insurance systems vary significantly worldwide, so understand exclusions, deductibles, coverage limits, and the reputation of the provider before purchasing.

    30. Use Financial Services Safely

    Bank accounts, credit unions, mobile money, digital wallets, and regulated financial services can make saving and payments easier.

    The World Bank describes access to affordable payments, savings, credit, and insurance as important to poverty reduction and economic growth.

    But always protect passwords, PINs, verification codes, and personal information.

    Never send money merely because an unexpected message claims you must act immediately.

    31. Invest in Your Health and Ability to Work

    Your ability to earn is one of your most important economic assets.

    Within your means, prioritize adequate sleep, nutrition, preventative care, exercise, workplace safety, and medical attention when necessary.

    Poor health can create expenses and reduce earning capacity, although many health circumstances are outside an individual’s control.

    Protect your ability to remain productive whenever possible.

    32. Measure Your Net Worth

    Income tells you what you earn.

    Net worth helps show what you are building.

    Calculate:

    Assets – Liabilities = Net Worth

    Do not panic if the number is initially negative.

    Use it as a starting point.

    Recalculate every six or twelve months. Progress might mean increasing savings, reducing debt, acquiring productive assets, or building investments.

    33. Create a Five-Year Financial Plan

    Ask yourself:

    Where do I want to be financially five years from now?

    Your plan might include:

    • A new professional qualification
    • Higher income
    • No high-interest consumer debt
    • A fully funded emergency reserve
    • A profitable side business
    • Regular investments
    • A home deposit
    • Education funding
    • Retirement contributions

    Then work backward and determine what must happen this year.

    34. Build a Long-Term Financial Plan

    Financial progress does not stop once your immediate situation improves.

    Think about retirement, housing, children’s education, healthcare, business succession, insurance, investments, taxes, and estate planning where applicable.

    Investor.gov emphasizes setting financial goals, creating a plan, regularly investing, controlling high-interest debt, and maintaining emergency savings as components of long-term wealth building.

    Your country’s financial system will determine which retirement and investment vehicles are available.

    35. Become Consistent Instead of Searching for Perfection

    The final habit connects everything else.

    Consistency matters more than occasional bursts of motivation.

    Save repeatedly.

    Learn repeatedly.

    Apply for opportunities repeatedly.

    Improve your skills repeatedly.

    Review your budget repeatedly.

    Invest carefully and consistently when financially ready.

    A person who makes small improvements for years may ultimately achieve more than someone constantly searching for one dramatic shortcut.

    Real-Life Example 1: From Low Income to a Marketable Skill

    Imagine Samuel earns the equivalent of $350 per month and struggles to cover expenses.

    Instead of borrowing money to start a large business, he studies job advertisements and discovers strong local demand for commercial electrical technicians.

    He saves gradually, completes affordable technical training, gains entry-level experience, and eventually moves into a higher-paying role.

    His transformation did not begin with investing.

    It began with increasing the market value of his labor.

    Real-Life Example 2: Turning a Small Skill Into Additional Income

    Amina already works full-time but enjoys baking.

    She begins accepting small weekend orders rather than immediately renting a commercial shop. She tracks ingredient, packaging, transportation, electricity, and marketing costs.

    As demand grows, she reinvests part of the profits into equipment.

    Eventually, the business creates a meaningful second income.

    The lesson is simple: test small, measure demand, control costs, and scale gradually.

    Real-Life Example 3: Using Digital Skills to Reach a Global Market

    Daniel lives in a country where local wages are relatively low.

    He learns video editing and creates a portfolio. Instead of depending exclusively on local clients, he begins offering services remotely.

    His first projects pay little, but reviews, experience, and better skills allow him to pursue higher-value work.

    The internet does not guarantee financial success, but digital skills can sometimes expand the market in which your labor competes.

    What Successful Financial Journeys Have in Common

    Success stories often appear dramatic when viewed from the end.

    What we do not see are the years of learning, rejection, small savings, unsuccessful applications, business experiments, disciplined spending, and gradual improvement that came first.

    Sustainable financial progress commonly involves several elements working together:

    Skills + Income + Financial Discipline + Savings + Productive Assets + Time

    Remove financial discipline and higher income can disappear.

    Remove income growth and saving may remain extremely difficult.

    Remove skills and opportunities may be limited.

    Remove time and people become vulnerable to unrealistic get-rich-quick promises.

    The goal is to strengthen all of these areas gradually.

    Conclusion

    Escaping Poverty Is a Journey, Not a Single Financial Decision

    There is no honest promise that 35 habits will automatically lift every person out of poverty. Economic circumstances differ dramatically around the world, and many barriers cannot be solved through personal budgeting alone.

    But you can focus on the areas where you have influence.

    Learn valuable skills. Pursue better income. Build multiple income sources carefully. Control unnecessary spending. Avoid destructive debt. Create emergency savings. Use digital opportunities intelligently. Build professional relationships. Explore entrepreneurship by solving real problems. Invest cautiously when financially ready. Protect yourself from scams. Develop assets and plan years—not days—ahead.

    You do not have to transform your financial life overnight.

    Choose three habits from this guide and begin there.

    Then add another.

    The objective is not instant wealth. It is to create a financial position that becomes progressively stronger, more resilient, and more capable of generating opportunities.

    Learn more. Earn more. Keep more. Build assets. Protect your progress. Give the process time.

    Educational disclaimer: This article provides general financial education and does not guarantee that any strategy will eliminate poverty or produce wealth. Income opportunities, investments, financial products, taxes, labor markets, regulations, and consumer protections vary by country. Investments involve risk, including possible loss of principal. Consider qualified local professional guidance where appropriate.