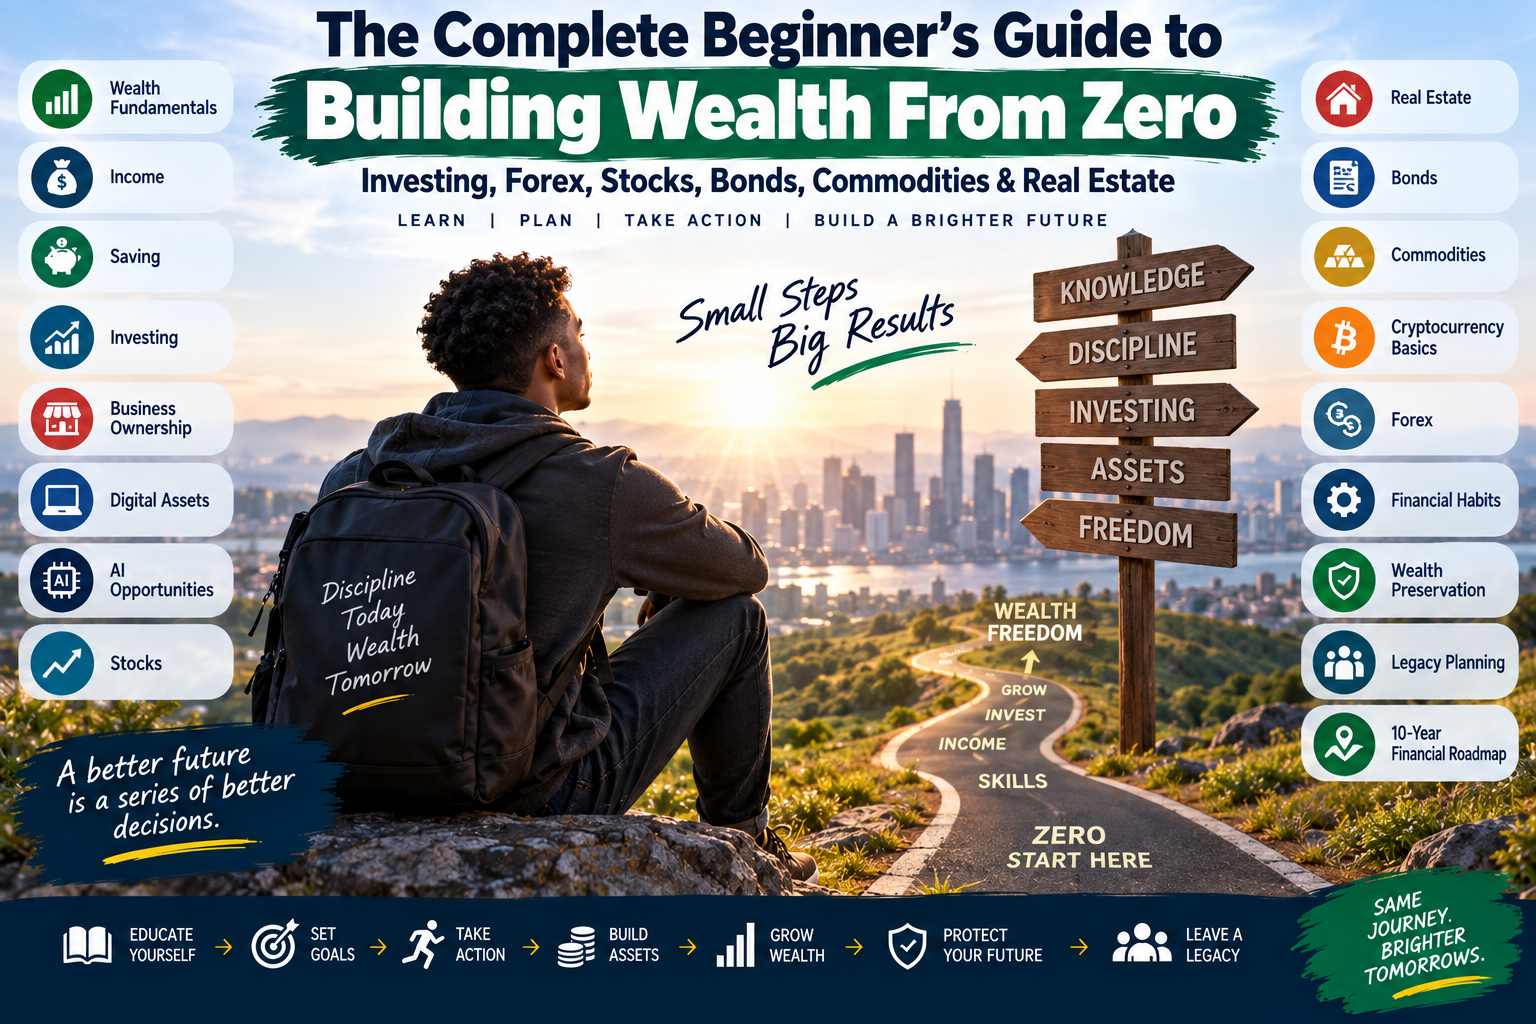
Building Wealth from Zero is possible. it depends on how you look at it
Introduction
Building wealth from zero can feel impossible when you have a small income, little savings, debt, or no investments.
But wealth usually does not begin with a million-dollar investment.
It begins with something much smaller:
Knowledge.
Then comes income.
Then saving.
Then investing.
Then productive assets.
Then time.
The basic wealth-building process can be summarized as:
Block 9 – After Paragraph 8
Learn → Earn → Save → Invest → Build Assets → Increase Income → Diversify → Protect → Reinvest → Repeat
Investor.gov explains that investing can help build wealth over time, while emphasizing that investment decisions should reflect your goals, time horizon and risk tolerance.
Investor.gov Introduction to Investing
This guide explains how someone starting with very little can begin building a stronger financial foundation through income, saving, investing, business ownership, stocks, bonds, real estate, digital assets and other opportunities—without pretending that any investment guarantees wealth.
1. Understand What Wealth Really Means
Wealth is not the same as income.
Someone can earn $150,000 annually and spend $160,000.
Another person might earn $70,000, control expenses, invest consistently and gradually accumulate productive assets.
Income tells you how much money comes in.
Wealth is more closely connected to what you own minus what you owe.
A simple calculation is:
Net Worth = Assets − Liabilities
Assets may include:
Cash + Savings + Investments + Retirement Accounts + Business Equity + Property
Liabilities can include:
Credit Cards + Personal Loans + Student Loans + Auto Loans + Mortgages + Other Debts
Your starting net worth might be $500.
It might be $0.
It might even be negative.
The important question is:
Can you improve it year after year?
2. Build Your Wealth Foundation Before Chasing Investments
People sometimes begin their wealth journey by asking:
“Which stock should I buy?”
or:
“Which cryptocurrency will make me rich?”
Those are usually the wrong first questions.
A stronger foundation begins with:
Reliable income
Controlled spending
Emergency savings
Manageable debt
Financial education
Clear goals
Only then does investing become part of a broader wealth-building strategy.
Think of your financial life as a house.
Your income is the ground.
Your budget is the foundation.
Emergency savings provide stability.
Investments and businesses build the upper floors.
Trying to build the roof first creates unnecessary risk.
3. Income: Your First Wealth-Building Engine
When you are starting from zero, your most valuable financial asset may be your ability to earn.
If you have $200 available to invest, finding a miraculous investment isn’t the most realistic path to major wealth.
Increasing your income by $10,000 annually could have a much larger impact.
Ways to increase income include:
Career advancement
Additional qualifications
Higher-value skills
Freelancing
Overtime
Consulting
Small businesses
Digital services
Entrepreneurship
Ask yourself:
What skill could I develop over the next 12 months that employers or customers would pay me more to perform?
Improving earning capacity gives you additional capital to save and invest.
4. Control Spending Without Making Yourself Miserable
Building wealth does not require eliminating everything enjoyable from life.
It requires making sure consumption does not absorb everything you earn.
Suppose your income rises by $500 per month.
If spending immediately increases by $500, your wealth-building capacity has not improved.
Instead, consider directing part of every raise toward:
Savings
Investments
Debt reduction
Business capital
Lifestyle improvement is fine.
Just make sure your net worth improves along with your lifestyle.
5. Saving: Create Your First Financial Safety Net
Before taking substantial investment risk, build emergency savings.
Unexpected expenses happen:
Car repairs
Medical bills
Job loss
Family emergencies
Home repairs
Urgent travel
Without savings, these events can become debt.
Start with an achievable milestone.
For example:
$500 → $1,000 → One month of essential expenses → Three months → Several months
The appropriate emergency reserve depends on your income stability, household responsibilities and other circumstances.
The Consumer Financial Protection Bureau provides guidance on establishing emergency savings.
6. Automate Your Wealth-Building Habits
Willpower is unreliable.
Systems are stronger.
Consider automatically transferring money when income arrives.
For example:
Paycheck → Bills → Emergency Savings → Investments → Other Goals → Spending
Automation makes wealth building part of your financial routine.
Even $25 or $50 per paycheck establishes the habit.
As your income increases, increase the amount.
7. Investing: Understand the Purpose Before You Begin
Saving and investing serve different purposes.
Savings are generally appropriate for emergencies and shorter-term needs where accessibility and capital preservation are priorities.
Investing involves accepting risk in pursuit of potential returns.
Investor.gov explains that investment returns can come from increases in asset value, interest or dividends, but also emphasizes that all investments involve risk.
Investor.gov Investment Products Guide
Your investment strategy should consider:
Financial goals
Time horizon
Risk tolerance
Diversification
Fees
Taxes
Liquidity
Never invest in something simply because it is popular.
8. Compound Growth: Give Your Money Time
Compound growth occurs when investment returns potentially generate additional returns over time.
Imagine investing $200 every month.
In one year, you contribute:
$2,400
In ten years:
$24,000
In thirty years:
$72,000
If those investments also generate positive returns over the period, the portfolio could potentially become substantially larger than your direct contributions.
This is why starting small can still matter.
Use the official Investor.gov Compound Interest Calculator to test different contribution, return and time assumptions.
Time can become one of your most powerful wealth-building resources.
9. Stocks: Own Part of a Business
A stock represents an ownership interest in a company.
If the business becomes more valuable, the stock price may increase.
Some companies also distribute part of their profits to shareholders through dividends.
But stocks can decline significantly.
A successful company today can struggle tomorrow.
Investor.gov provides a detailed beginner’s explanation of stocks and how investors can buy them.
The biggest beginner mistake is assuming:
Popular company = Guaranteed investment return
It doesn’t.
Business performance, valuation, economic conditions, competition and investor expectations all influence stock prices.
10. Individual Stocks vs. Diversified Funds
Buying one company means your result depends heavily on that company.
Diversified funds can spread exposure across many securities.
Mutual funds and exchange-traded funds can make diversification easier, although narrowly focused funds may still be concentrated. Investor.gov emphasizes diversification both between asset classes and within them.
Investor.gov Guide to Asset Allocation and Diversification
Diversification does not guarantee against losses.
It is a method of managing concentration risk
11. Bonds: Understand Lending as an Investment
When you buy certain bonds, you are essentially lending money to an issuer such as a government, municipality or company.
In return, the issuer generally promises interest and repayment according to specified terms.
Bonds are often considered less volatile than stocks, but they are not risk-free.
Risks can include:
Interest-rate risk
Inflation risk
Credit/default risk
Liquidity risk
Investor.gov notes that bonds generally have lower volatility and more modest return potential than stocks, although higher-yield bonds can carry substantially greater risk.
Investor.gov Investment Options
12. Real Estate: Build Wealth Through Property Carefully
Real estate has created wealth for many people, but property is not automatically a profitable investment.
Potential ways to participate include:
Primary residences
Rental properties
Commercial property
Real estate investment trusts
Real-estate-related funds
For rental property, calculate:
Rent − Mortgage − Taxes − Insurance − Maintenance − Vacancies − Management − Other Expenses = Approximate Cash Flow
Do not assume:
$2,000 monthly rent = $2,000 monthly profit.
Real estate can provide rental income and potential appreciation, but it can also create concentrated risk, debt, repair costs and illiquidity.
13. Business Ownership: Build an Asset You Control
Employment produces income.
Business ownership can potentially produce both income and equity.
A successful company may eventually become an asset that has value beyond the owner’s monthly salary.
You don’t necessarily need millions of dollars to start.
Small businesses can include:
Cleaning
Tutoring
Graphic design
Marketing
Baking
Photography
Consulting
Landscaping
Web development
Transportation
E-commerce
Digital services
The U.S. Small Business Administration provides extensive information about planning and launching businesses.
Business structure also matters because liability, taxation and ownership rules differ. The SBA notes, for example, that a sole proprietorship generally does not create a separate legal business entity, while other structures can have different liability characteristics.
Readers outside the United States should consult their local business-registration and tax authorities.
14. Digital Assets: Turn Knowledge and Creativity Into Products
Not every productive asset is physical.
You can create digital assets such as:
Websites
eBooks
Online courses
Templates
Software
Apps
Educational resources
Membership platforms
Original media libraries
A useful digital asset may continue producing revenue after the original work is completed, although maintenance, marketing and customer support are usually still necessary.
Think of digital wealth creation as:
Knowledge → Product → Audience → Distribution → Revenue → Reinvestment
The strongest digital products solve specific problems.
15. AI Opportunities: Use Technology to Increase Productivity
Artificial intelligence is creating opportunities for entrepreneurs and workers to perform certain tasks faster.
Potential applications include:
Business automation
Research assistance
Customer support
Data organization
Marketing workflows
Educational products
Software development
Content assistance
Design workflows
But don’t build a business around the phrase “AI.”
Build it around a customer problem.
Ask:
What valuable problem can I solve better, faster or more affordably using AI?
Also protect confidential business and personal information when using AI services.
AI should increase human productivity—not replace judgment where accuracy, privacy or professional expertise is required.
16. Forex: Understand the Risk Before Trading
Forex means foreign exchange—the trading of currencies.
Currencies constantly fluctuate relative to one another because of factors such as:
Interest rates
Inflation
Economic growth
Central-bank policies
Trade
Political developments
Market expectations
Forex is frequently promoted online as an easy wealth-building opportunity.
That framing can be dangerous.
The U.S. Commodity Futures Trading Commission warns that most customers at registered over-the-counter forex dealers lose money after costs, and leverage can amplify losses; in some circumstances, losses can exceed the initial deposit.
CFTC: Eight Things You Should Know Before Trading Forex
For a beginner building wealth from zero, forex trading should not be confused with a basic savings or diversified long-term investment plan.
Never trade essential household money, emergency savings or borrowed money.
17. Commodities: Gold, Oil, Agriculture and More
Commodities include physical resources such as:
Gold
Silver
Oil
Natural gas
Corn
Wheat
Coffee
Other agricultural and industrial products
Investors may gain exposure through different financial products.
Commodity futures are particularly specialized and can involve substantial risk.
Investor.gov explains that commodity futures involve agreements to buy or sell specified quantities at predetermined terms and notes that futures and forex are areas where regulators warn about fraudulent high-yield offers.
Investor.gov Commodities Guide
Beginners should understand exactly what product they are buying before gaining commodity exposure.
18. Gold and Precious Metals
Gold is sometimes used as a portfolio diversifier or store-of-value asset.
But gold does not automatically increase in value.
It can experience long periods of disappointing performance.
Precious metals also do not produce business earnings in the way a profitable company can.
If you include commodities in your portfolio, understand why they are there.
Do not buy simply because someone predicts economic collapse.
19. Cryptocurrency Basics
Cryptocurrency and other crypto assets use blockchain or related distributed-ledger technologies.
They can include:
Coins
Tokens
Stablecoins
Other blockchain-based assets
Crypto markets can experience extreme price movements.
The CFTC warns that virtual currencies can be highly volatile and that leverage can amplify both gains and losses.
Custody introduces additional considerations. Investor.gov explains that crypto wallets generally hold the private keys used to access crypto assets, making secure custody an important part of understanding ownership.
Investor.gov Crypto Asset Custody Basics
Never assume crypto accounts provide the same protections as insured bank deposits. Some crypto products carry materially different protections and risks.
For beginners, crypto should be approached as a high-risk area requiring substantial education, not as guaranteed wealth.
20. Never Build Your Wealth Plan Around Speculation
There is an important distinction between:
Building wealth
and
trying to get rich quickly.
Wealth building generally emphasizes:
Income
Saving
Productive assets
Diversification
Compounding
Patience
Speculation focuses heavily on predicting future price movements.
Speculative assets may rise dramatically.
They can also collapse.
The more your strategy depends on predicting tomorrow’s price, the more risk you may be taking.
21. Diversification: Don’t Let One Investment Determine Your Future
A diversified portfolio spreads exposure across multiple investments or asset categories.
Depending on the investor, these might include:
Cash
Stocks
Bonds
Real estate
Business interests
Other appropriate assets
Investor.gov explains that diversification cannot guarantee against losses, but it can reduce dependence on any single investment.
Investor.gov Diversification Guide
Your appropriate allocation depends on your goals, time horizon, financial position and tolerance for loss.
22. Understand Risk Before Thinking About Return
Beginners frequently ask:
“How much can I make?”
A better first question is:
“How much could I lose?”
Investor.gov emphasizes that higher potential returns generally come with higher risk and that investors should consider risk, fees, goals and time horizon when evaluating investments.
Before buying any investment, understand:
How it generates returns
What could make it lose value
How easily you can sell it
What fees you pay
What taxes may apply
Whether leverage is involved
Whether the provider is regulated
If you cannot explain how an investment works, continue learning before committing money.
23. Avoid High-Cost Consumer Debt
Compound growth can work for you through investments.
Interest can also work against you through debt.
High-interest credit-card or consumer debt can absorb money that could otherwise build assets.
A sensible wealth-building sequence often involves controlling expensive debt while establishing emergency savings and gradually preparing to invest.
Do not borrow at extremely high rates hoping to earn even higher investment returns.
That can transform investing into dangerous speculation.
24. Financial Habits Matter More Than Financial Motivation
Motivation comes and goes.
Habits remain.
Useful wealth-building habits include:
Tracking spending
Saving automatically
Investing regularly
Reviewing debt
Reading financial information
Increasing contributions with income
Avoiding emotional purchases
Reviewing net worth annually
A $100 monthly habit maintained for years can be more valuable than an ambitious financial plan abandoned after three months.
25. Build Multiple Income Streams Gradually
Your wealth journey may begin with one salary.
Eventually it might evolve into:
Salary + Freelancing + Business + Investment Income + Digital Assets
You don’t need seven side hustles.
Build one additional income stream.
Make it profitable.
Improve the system.
Then consider another.
Income diversification can reduce dependence on a single paycheck and provide additional capital for acquiring assets.
26. Reinvest Instead of Consuming Every Profit
Suppose your side business generates an additional $500 monthly.
You could immediately spend the entire $500.
Or you could divide it:
Emergency Savings
Business Reinvestment
Long-Term Investments
Debt Reduction
Personal Enjoyment
Reinvestment is how additional income can gradually become productive capital.
The goal is:
Income → Assets → More Potential Income → More Assets
27. Protect the Wealth You Build
Building wealth is only half the journey.
You must also protect it.
Wealth preservation may involve:
Emergency reserves
Diversification
Appropriate insurance
Cybersecurity
Fraud prevention
Responsible debt
Tax planning
Legal structures where appropriate
Estate planning
As your wealth grows, one preventable financial disaster becomes increasingly expensive.
28. Protect Yourself From Investment Scams
Wealth-building beginners are prime targets for scammers.
Warning signs include:
Guaranteed profits
No-risk returns
Secret investment opportunities
Pressure to act immediately
Unregistered forex brokers
Fake crypto platforms
Celebrity impersonations
Requests to transfer money privately
For forex, the CFTC specifically recommends researching dealers and checking regulatory registration before depositing money.
For securities investing, use Investor.gov and appropriate national securities regulators.
Never let fear of missing out replace due diligence.
29. Legacy Planning: Decide What Your Wealth Is For
Wealth is not only about what happens during your lifetime.
As assets grow, think about:
Who depends on you?
What happens if you die unexpectedly?
Who should receive your assets?
Who can manage important affairs if you cannot?
Depending on local law and your circumstances, legacy planning might involve:
Wills
Beneficiary designations
Insurance
Powers of attorney
Trusts
Business succession planning
Charitable giving
Estate and inheritance laws differ substantially by country, so obtain qualified local legal and tax guidance when needed.
The objective is to make sure the wealth you spent decades building is transferred according to your intentions
30. Your 10-Year Financial Roadmap From Zero
Building wealth becomes easier when you stop thinking only about next month.
Think in years.
Year 1 — Financial Stabilization
Focus on:
Budgeting
Tracking expenses
Initial emergency savings
High-cost debt
Financial education
Increasing employable skills
Goal:
Stop financial instability from controlling your decisions.
Year 2 — Increase Your Financial Capacity
Work on:
Increasing income
Improving skills
Building emergency reserves
Reducing expensive debt
Beginning basic investing education
Goal:
Create consistent monthly financial surplus.
Year 3 — Become an Investor
Once financially prepared, establish an appropriate long-term investment strategy.
Learn about:
Stocks
Bonds
Diversified funds
Retirement accounts
Risk
Fees
Taxes
Goal:
Begin acquiring productive financial assets consistently.
Year 4 — Build Your Second Income Stream
Choose one realistic opportunity:
Freelancing
Consulting
Digital products
Service business
Online business
Part-time enterprise
Goal:
Reduce dependence on one paycheck.
Year 5 — Increase Your Asset Ownership
Increase contributions as income improves.
Your financial picture might now include:
Emergency savings + Investments + Retirement assets + Business assets
Goal:
Make asset ownership a normal part of your financial life.
Year 6 — Explore Additional Asset Classes
Once you understand basic investing, learn about other opportunities such as:
Real estate
Bonds
Business equity
Digital assets
Appropriate alternative investments
This does not mean buying everything.
Goal:
Understand opportunities before deciding whether they belong in your plan.
Year 7 — Scale What Works
By now, you should have evidence about which income and investment strategies work for you.
Scale successful areas.
Stop wasting resources on unsuccessful ones.
Goal:
Concentrate effort without creating dangerous financial concentration.
Year 8 — Strengthen Wealth Protection
Review:
Insurance
Emergency reserves
Investment diversification
Cybersecurity
Taxes
Legal structures
Estate planning
Goal:
Protect accumulated assets from avoidable risks.
Year 9 — Build Greater Financial Independence
Calculate:
Annual expenses
Investment assets
Business income
Passive or portfolio income
Net worth
Debt
Ask:
How dependent am I on employment income today compared with nine years ago?
Goal:
Increase your financial options.
Year 10 — Review, Rebalance and Design the Next Decade
Measure your progress.
Compare:
Year 1 Income → Year 10 Income
Year 1 Savings → Year 10 Savings
Year 1 Investments → Year 10 Investments
Year 1 Debt → Year 10 Debt
Year 1 Net Worth → Year 10 Net Worth
Then build the next ten-year plan.
Your financial journey doesn’t end at Year 10.
You have simply built a stronger starting point for the next decade.
The Wealth-Building Pyramid
Think about wealth in layers.
Level 1 — Knowledge
Learn money fundamentals.
Level 2 — Income
Develop valuable skills and increase earnings.
Level 3 — Financial Stability
Budget, save and manage expensive debt.
Level 4 — Investing
Acquire diversified productive assets.
Level 5 — Ownership
Build business, property and other appropriate assets.
Level 6 — Diversification
Avoid depending on one income source or investment.
Level 7 — Wealth Preservation
Protect assets through appropriate risk management.
Level 8 — Legacy
Transfer wealth intentionally.
Trying to jump directly from Level 1 to speculative trading at Level 6 is not a shortcut.
It may simply expose you to risks you are not financially prepared to absorb.
A Beginner’s Wealth-Building Checklist
Before considering yourself ready for increasingly complex investments, ask:
Do I understand my monthly cash flow?
Do I have emergency savings?
Is expensive consumer debt under control?
Am I consistently saving?
Do I understand what I am investing in?
Do I understand potential losses?
Am I diversified appropriately?
Am I paying reasonable fees?
Am I investing for a defined goal?
Am I protecting myself from fraud?
Am I increasing my earning capacity?
Am I building productive assets?
Do I have a long-term financial plan?
If several answers are no, those areas may deserve attention before chasing higher-risk opportunities.
Conclusion
Building wealth from zero does not begin with finding the perfect stock, predicting currency markets, buying cryptocurrency or discovering the next investment sensation.
It begins with fundamentals.
Learn how money works.
Increase your income.
Control unnecessary spending.
Build emergency savings.
Manage destructive debt.
Invest consistently.
Diversify.
Build businesses and productive assets.
Protect what you accumulate.
Plan for the next generation.
Stocks can contribute to wealth.
Bonds can have a role.
Real estate can create opportunities.
Business ownership can become enormously valuable.
Digital assets can generate income.
AI can improve productivity.
Commodities may serve particular portfolio purposes.
Crypto assets may offer opportunities alongside substantial risks.
Forex exists as a massive global market—but leveraged retail forex trading should never be mistaken for a guaranteed wealth-building system.
There is no single asset that every person must own.
Your appropriate strategy depends on your income, goals, responsibilities, time horizon and ability to withstand losses.
The most important thing about starting from zero is understanding that zero does not have to be your permanent financial position.
Your first $100 matters.
Your first emergency fund matters.
Your first investment matters.
Your first profitable business matters.
Your first $10,000 matters.
And every responsible financial decision can move you further from dependence and closer to ownership.
The journey may take ten, twenty or thirty years.
That is not failure.
That is how long-term wealth is often built:
One skill.
One paycheck.
One saved dollar.
One investment.
One productive asset.
One disciplined decision at a time.


Leave a Reply